Ways to Save Money: 30 Simple Habits That Repeat Every Month
The best ways to save money are not dramatic one-time sacrifices; they are small, boring habits that repeat every month without much thought. Money feels tight for many ordinary households even when no single expense looks outrageous. Rent or a mortgage takes its share, utilities arrive on schedule, the car needs fuel and repairs, and small purchases fill the gaps between paychecks. When prices rise or income changes, it can feel as though you are always reacting instead of deciding.
This guide collects 30 practical ways to save money, grouped by where the money actually goes: food, home and utilities, transportation, bills and subscriptions, shopping, and the money systems that hold it all together. None of them require extreme coupon binders or eating rice for a month. Most take an afternoon to set up and then keep paying off quietly.
The Frugal Beans Mindset: Give Every Dollar a Job
Here at Frugal Beans, the whole idea fits in one sentence: treat every dollar as a useful resource and give it a clear job before it disappears. That does not mean buying the cheapest thing every time or refusing every pleasure. It means noticing where money goes, protecting what matters, and finding repeatable ways to make a limited income go further.
Frugality is different from being cheap. Being cheap focuses only on the lowest price, even when the result is poor quality, unsafe or wasteful. Being frugal considers total value: price, usefulness, durability, time, risk and enjoyment. A $12 item that sits unused is not a bargain, and a durable item that lasts for years may cost less in the long run.
Before trying any of the ways to save money below, ask three quick questions:
- What do we have? Income, savings, useful possessions, skills and support, without pretending any of them are bigger than they are.
- What do we need money to do? Housing, food, transportation, health, debt payments and goals.
- What can change? Expenses, habits, timing and income that can be adjusted without harming safety or dignity.
If you are brand new to this, our guide to frugal living for beginners walks through the first month step by step.
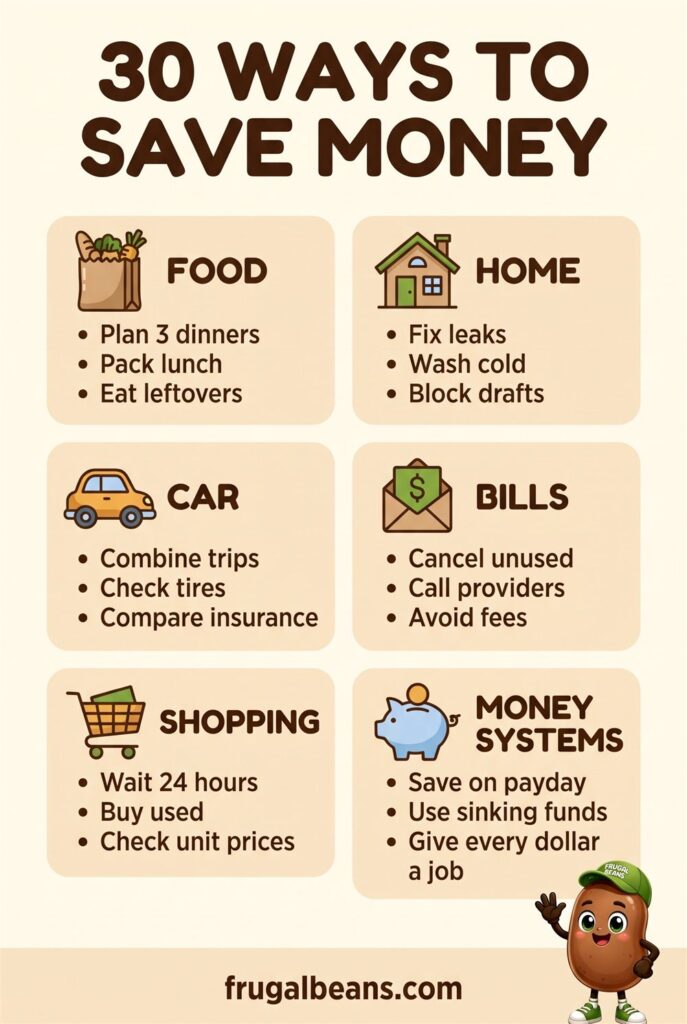
30 Ways to Save Money at a Glance
Use this one-page summary as a checklist. Pick three ideas that fit your household, try them for a month, and keep the ones that stick. The sections below explain the reasoning behind each habit and how to set it up.
Ways to Save Money on Food
Food is where many people look first, and for good reason: it is a frequent purchase, so a small improvement repeats dozens of times a month. Groceries are only one part of the picture, but they are a good place to build momentum.
1. Plan Three Dinners Before You Shop
You do not need a full weekly meal plan. Pick three flexible dinners, check what is already in the fridge, freezer and pantry, and build the list from there. Planning a few meals prevents the common cycle of buying ingredients for something new while older food quietly expires.
2. Pack Lunch Most Workdays
A packed lunch is one of the most reliable small ways to save money because it repeats every workday. Suppose a bought lunch costs $12 and a packed one costs about $4 in groceries. That is $8 a day, or roughly $160 over 20 workdays. Your numbers will differ, but the math is worth doing for your own routine.
Make it easy: cook a little extra at dinner, portion it straight into containers, and keep a few grab-and-go items such as fruit, carrots or boiled eggs ready for busy mornings.
3. Keep an “Eat First” Bin and Eat Leftovers
Put a clear bin on an eye-level fridge shelf for leftovers and produce that needs to be used soon. Food you throw away is money you already spent. Freeze extra portions in labeled containers rather than hoping everyone will want the same leftovers on the fourth day.
4. Keep Two Default Cheap Dinners for Tired Nights
Expensive takeout usually happens when everyone is exhausted and nothing is ready. Choose two low-effort meals you can always make, such as bean tacos, pasta with vegetables, or eggs and toast, and keep the ingredients on hand. If you are weighing paid convenience instead, see whether meal delivery services are worth it for your household.
5. Compare Unit Prices and Try Store Brands
The shelf tag often shows a unit price, the cost per ounce or per count. Use it to compare package sizes and brands. Store brands and seasonal produce can stretch a grocery budget, but a bigger package is only a bargain if you actually use all of it.
Ways to Save Money at Home on Utilities
Most households save money on utilities through behavior and maintenance rather than gadgets. These habits cost little or nothing and work in both owned and rented homes. For a deeper room-by-room walkthrough, read our guide on how to save money at home.
6. Fix Drips and Running Toilets Quickly
A small leak runs all day, every day. Replacing a worn washer or flapper is often a simple job, and fixing it promptly protects cabinets and floors from water damage too.
7. Wash Full Loads in Cold Water
Run the washer and dishwasher only when they are full, and use cold water for everyday clothes when the care label allows it. Air-dry when convenient, and clean the dryer lint screen after every load so air moves freely.
8. Nudge the Thermostat and Dress for the Season
Move the thermostat a few degrees toward the outdoor temperature, especially when you are asleep or away, and add a sweater or a fan instead. Close doors to rooms that do not need the same temperature.
9. Block Drafts Before Buying Upgrades
A draft stopper or rolled towel under an exterior door is a cheap first step. Before spending $200 on a device to save $20 a year, check how long it would take to pay for itself. Simple habits like this usually pay back faster than equipment.
10. Maintain What You Own
Clean filters on schedule, replace worn seals, and follow appliance care instructions. The biggest home bills come from the furnace, air conditioner, water heater and major appliances failing at the worst moment. Our free Homeowner Repair Cost Playbook lists typical lifespans and repair costs so you can plan a replacement instead of paying emergency rates.
Ways to Save Money on Transportation
Transportation is a structural expense, so when you save money here, the improvements tend to be larger than any single shopping trick. Start by calculating the full monthly cost of each vehicle: payment, fuel, insurance, maintenance, repairs, parking and registration. A low sticker price does not guarantee a low total cost.
11. Combine Errands Into One Trip
Group errands by location and do them in one loop instead of several separate drives. Fewer trips means less fuel and less wear on the car, and it often cuts impulse stops as well.
12. Keep Up With Basic Car Maintenance
Check tire pressure monthly, follow the oil-change schedule in your owner’s manual, and deal with small problems before they become big ones. Smooth driving helps too: the U.S. government’s fuel economy site explains how aggressive driving lowers gas mileage and what to do instead.
13. Compare Car Insurance Every Year
Get quotes at renewal, ask about discounts you may qualify for, and review your coverage levels. Keep the protection you genuinely need; becoming dangerously underinsured is not frugality.
14. Try One Car-Free Option
Where it is practical and safe, compare driving with public transit, cycling, walking or carpooling for one regular trip. Some households find they can share one vehicle instead of two. If a car is essential, prioritize reliability and reasonable operating costs over status.
Ways to Save Money on Bills, Subscriptions and Fees
Recurring bills deserve attention because a successful cut repeats automatically. Trimming a $60 monthly bill frees $720 over a year, more than skipping a long list of small purchases, and you only have to do it once.
15. Cancel Subscriptions You Did Not Use Last Month
Scroll through your bank and card statements and list every recurring charge: streaming, apps, software, memberships and boxes. Cancel or pause anything you did not use last month. Cancel through the company’s actual billing system, then check your next statement to confirm the charge stopped.
16. Turn Off Auto-Renew When You Start a Free Trial
Free trials are designed to roll into paid plans. Set a calendar reminder or switch off auto-renew on day one, then decide deliberately whether the service is worth keeping.
17. Call Providers and Ask for a Better Rate
Phone, internet and insurance companies often have lower plans than the one you are on. Ask what options exist, remove features you do not use, and compare competing offers. A 20-minute call can lower a bill for every month that follows.
18. Stop Paying Bank Fees
Check for monthly maintenance fees, overdraft charges, out-of-network ATM fees and paper-statement charges. Set up low-balance alerts and keep a small cushion in checking so a timing mistake does not set off a chain of fees. If your account keeps charging you, look for one that does not.
19. Line Up Due Dates With Payday
A household can earn enough over a month and still run short in a particular week because bills are due before payday. Put every bill on one calendar and ask providers to move due dates where possible. Autopay protects against late fees, but still review the account monthly for charges you do not recognize, renewals that went up in price, and duplicate services.
20. Review Housing at Renewal Time
Housing is usually the biggest bill. If rent or a mortgage takes too much of your income, options include a compatible housemate, moving at lease renewal, a smaller place, or living closer to work. Moving has its own costs, so compare the full picture rather than assuming a lower monthly payment is automatically better.
Smart Shopping: Small Ways to Save Money on Things You Buy
When you shop, you save money less by finding the perfect coupon and more about adding a little friction between the urge and the purchase.
21. Use a 24-Hour Pause
Wait a day before buying anything nonessential above a set amount, and keep a 30-day list for bigger purchases. During the pause, write down the problem the item solves and where it will live. If you cannot answer, the purchase may be a response to advertising rather than a need.
22. Remove Saved Cards and Unsubscribe From Promo Emails
One-click checkout and daily sale emails make spending effortless. Delete saved payment details from shopping apps and unsubscribe from promotional messages. These changes do not require willpower; they simply add a moment for a deliberate decision.
23. Buy Used When It Is Safe and Easy to Inspect
Clothing, furniture, tools, books and many household goods are good secondhand candidates. Buy used when the condition is clear and safety is not in question, and skip anything just because it is cheap.
24. Sell or Donate What You Do Not Use
Photograph items honestly, research a realistic price, and account for platform fees and your time. Bundle low-value items when that makes listing worthwhile. The goal is space and useful cash, not turning your home into a resale warehouse.
25. Borrow Before You Buy
Libraries, tool-lending programs, neighbors and friends can cover occasional-use items. Agree on return dates and who is responsible for damage so that saving money does not create conflict.
Money Systems That Make Saving Automatic
The first 25 habits free up money. These last five make sure that money actually goes somewhere useful instead of quietly disappearing into everyday spending. This is the “give every dollar a job” part of the Frugal Beans approach.
26. Take a Simple Cash-Flow Snapshot
Gather two or three months of bank statements and bills, and group spending into broad categories. You do not need to explain every coffee. A basic snapshot might look like this:
|
Category |
Question to ask |
|
Take-home income |
Is this a conservative, dependable number? |
|
Housing and utilities |
Is the home affordable for our current income? |
|
Transportation |
What is the full cost, including repairs and insurance? |
|
Food and household supplies |
Which purchases are planned, and which are rushed? |
|
Debt minimums |
Which balance costs the most interest? |
|
Flexible spending |
Which choices provide real value? |
|
Savings and extra debt payment |
What future problem is this money preventing? |
The basic equation is simple: take-home income minus essentials, flexible spending and goals equals what is left. If the result is negative, do not blame yourself. Look for the largest pressure points first, because a rent payment, car loan or high-interest balance can matter more than a dozen small cuts.
27. Move Savings on Payday, Automatically
Set an automatic transfer to savings for the day your paycheck lands. When saving is the default, you do not have to rely on whatever is left at the end of the month. Start with an amount you can sustain, even if it is small, and raise it when a bill goes away.
28. Build an Emergency Fund in Stages
An emergency fund is cash set aside for necessary, unexpected expenses or a loss of income. Start with a small starter goal, then work toward one month of essential expenses and eventually a larger cushion suited to your job stability and family. Keep it accessible but separate from everyday spending. The CFPB’s guide to building an emergency fund has practical tips for getting started.
29. Use Sinking Funds for Predictable Bills
A sinking fund is money set aside gradually for an expense you know is coming: annual insurance, car registration, school supplies, holiday gifts. Divide the yearly cost by twelve and save that amount each month. An emergency is unplanned; a yearly bill is not, even if it feels like a surprise.
30. Pay Down High-Interest Debt With a Clear Order
Keep every minimum payment current, then send extra money to one balance at a time. The debt avalanche method targets the highest interest rate first and usually saves the most interest. The debt snowball method targets the smallest balance first for quicker wins. Pick the one you will stick with.
For example, suppose a household can add $250 a month beyond the minimums. It applies the $250 to the top-priority balance, and when that balance is gone, it rolls the whole payment into the next one. The key is keeping the total payment the same as balances disappear, rather than treating freed-up money as permission to spend more.
Creative Ways to Save Money Without Feeling Deprived
Sustainable frugality is not built on constant refusal. A plan that cuts every enjoyable thing usually ends in a rebound spending spree. These creative ways to save money keep the plan livable.
Protect What You Value, Cut What You Forget
Sort your spending into three groups: needs that protect safety, health, housing and work; values you deliberately choose because they improve your life; and habits that are mostly automatic or forgettable. Cut the forgettable spending first; that is where you save money without missing anything. If a weekly dinner with friends matters to you, keep it and cancel the streaming service nobody watches.
Use a Replacement Ladder
Swap an expensive habit for a slightly cheaper one before going to the cheapest option. For example, move from frequent restaurant delivery to pickup, then from pickup to one planned restaurant meal a week, while keeping easy meals at home. Gradual steps are more likely to last than strict rules that clash with real schedules.
Watch Out for Lifestyle Inflation
When income goes up, it is easy for spending to follow: a bigger apartment, a nicer car, more upgrades. Enjoying part of a raise is reasonable. Decide before it arrives how much will go to savings or debt, how much to a meaningful improvement, and how much to everyday flexibility. When a loan ends, redirect the old payment to a goal for a few months before deciding what to do with it.
Earn a Little More
Frugality has a floor. You can only cut so far before it harms your health or work. Asking for a raise with evidence of your results, picking up a side project, or selling unused items can add more breathing room than eliminating another modest pleasure. Give that extra income a specific job so it does not dissolve into ordinary spending. For more ideas when the budget is already lean, see our ways to save money on a tight budget.
A Monthly Routine to Keep These Ways to Save Money Working
A short monthly check-in turns good intentions into a habit. Pick one evening or weekend morning and keep the review short enough that you will actually repeat it.
- Close last month. Check balances, confirm bills cleared, and compare actual spending with the plan. Look for patterns, not individual sins.
- List next month’s known costs. Rent, utilities, debt payments, insurance, birthdays, appointments and any annual bills coming due.
- Assign income before spending it. Fund essentials first, then debt minimums, savings, goals and flexible categories. If income varies, use a conservative estimate.
- Choose one fixed-cost action. Cancel a service, call a provider, compare insurance or change a phone plan. One finished action beats a long list of intentions.
- Choose one variable-cost experiment. Try a cheaper replacement, a no-buy week for one category, or packed lunches every day for a month.
- Direct extra money. Send any surplus, refund or bonus to the current priority, such as the emergency fund or the top debt.
- Talk it over. Share what is working and what feels too tight. A plan the whole household agrees on lasts longer than one imposed on everyone else.
Expect imperfect months. A sick child, a broken appliance or a family obligation can knock the plan off track. Note what happened, use your reserves if that is what they are for, and return to the routine without trying to make up for it through extreme cutbacks. For more everyday ideas to rotate into your routine, browse our frugal living tips.
Ways to Save Money: Frequently Asked Questions
What are the easiest ways to save money right away?
Cancel subscriptions you did not use last month, plan three dinners from what is already in your kitchen, and set up an automatic transfer to savings on payday. All three can be done in one afternoon and cost nothing to start.
How much money can small habits really save?
It depends on your starting point, so track your own numbers rather than chasing a headline figure. Small habits add up because they repeat: trimming a $60 monthly bill frees $720 over a year, and that is before counting groceries, fees or utilities.
Is it better to cut spending or earn more?
Both help you save money, and they work best together. Start by cutting low-value recurring costs because each cut repeats automatically. Once spending is reasonably lean, further cuts tend to hurt, and earning more usually adds more breathing room.
What should I do with the money I save?
Give it a job right away. A common order is a small starter emergency fund, then extra payments on high-interest debt, then sinking funds for predictable bills, then a larger emergency fund and long-term goals. Moving the money automatically keeps it from drifting back into everyday spending.
The Bottom Line
The most effective ways to save money are the ones you set up once and then repeat without thinking: a packed lunch, a canceled subscription, a full washer, a payday transfer. Each one helps you save money in a small way, but together they change how much room you have every month.
Start with visibility rather than perfection. Pick three habits from this list, try them for a month, and keep what works. Then give every dollar you free up a clear job, whether that is an emergency fund, a smaller debt or a goal that matters to you. That is the Frugal Beans approach: not spending the least, but making deliberate choices that turn a limited income into more freedom over time.
Leave a Reply
Get the free Homeowner Repair Cost Playbook
Which systems fail first, what they cost, the warning signs, and the repair-or-replace rule. 15 printable pages.
Free. No spam.
Free tool
Repair or replace?
Got a quote for your furnace, AC, water heater or an appliance? Check it in under a minute.
Free tool
What needs replacing next?
Enter the install years for your furnace, AC, water heater and appliances. See what is due first and what to save each month.
2 Responses to Ways to Save Money: 30 Simple Habits That Repeat Every Month