
admin
Barefoot Investor for Families Review: 7 Simple Lessons for Kids
This Barefoot Investor for Families review starts with a confession: an earlier version of this post mixed up two different books. Scott Pape’s first book, The Barefoot Investor, is about adult budgeting with “buckets” and bank accounts. The Barefoot Investor for Families is something else. It is a guide for parents on teaching children about money, built around jobs, pocket money and three simple jars. This rewrite fixes that and focuses on what the families book actually teaches.
Money is rarely just about money in a household. It is also about tired parents, children asking for treats at the checkout, and the quiet worry that kids are growing up without knowing what things cost. That is why a book about kids and money can be so appealing. It does not start with investment products or a lecture. It starts with a practical question: how can children learn the value of a dollar at home, one small habit at a time?
Below you’ll find the verified basics about the book, its seven key lessons in our own words, how a U.S. family might adapt them, a fair list of pros and cons, and who the book suits best. One thing to know up front: the book is Australian, so some details need translating for American readers.
Barefoot Investor for Families Review: What the Book Is
The Barefoot Investor for Families was written by Scott Pape, an Australian personal finance columnist best known for his 2016 bestseller The Barefoot Investor. The families book followed in 2018 and was published in Australia by HarperCollins. It is a paperback for parents (and grandparents), not a book for children to read on their own.
According to the author’s official books page, it covers ten things kids need to know about money before they leave home, and it presents a pocket money plan that is meant to take about three minutes a week. The same page lists an audiobook version. We could not find a newer revised edition of the families book; listings still point to the 2018 release.
Don’t confuse it with Pape’s later title, Barefoot Kids (2022). That one is written in a visual format for children themselves, with money stories from Australian kids. The 2018 families book is the parent’s playbook.
The Australian context
The book was written for Australian families. Its examples use Australian dollars, Australian banks, Australian schools and the Australian word “pocket money” where most American parents would say “allowance.” Some later lessons touch on superannuation, Australia’s compulsory workplace retirement savings system. The closest U.S. concept is an employer retirement plan such as a 401(k), although the rules are very different. Bank products mentioned in a 2018 book may also have changed since.
None of that makes the book less useful in the U.S. The core ideas are about behavior, not products. You just have to read it with a translator’s eye.
The Big Idea Behind the Barefoot Investor for Families
At its heart, the Barefoot Investor for Families argues that children learn about money by handling it, not by hearing about it. A child who earns a little money, divides it up, waits for something they want, and gives some away learns more than a child who is simply handed cash or told “we can’t afford that.”
The system has three working parts:
- Jobs: children do a few age-appropriate jobs around the house and are paid for them.
- Jars: the money goes into three physical jars, each with its own purpose.
- A weekly family money meal: a regular meal where parents check the jobs, pay the kids and talk about money.
The amount of pocket money is not the important part. The practice of earning, choosing and living with the result is the lesson. That idea carried over from the original version of this post, and it holds up well.
Barefoot Investor for Families Review: The 7 Simple Lessons
Here are the seven ideas that stood out most to us, summarized in our own words. They are not a list of the book’s chapters, and the book contains more detail, stories and age-by-age guidance than we cover here.
1. Pocket money should be earned
Pape’s position is that pocket money is pay for work, not a gift. Children are given a small number of age-appropriate jobs, and they are paid when the jobs are done. If a job is skipped, it isn’t paid. The point is to connect effort and money early, in a low-stakes setting where the “job” might be feeding the dog or unpacking the dishwasher.
2. Three jars give money a job
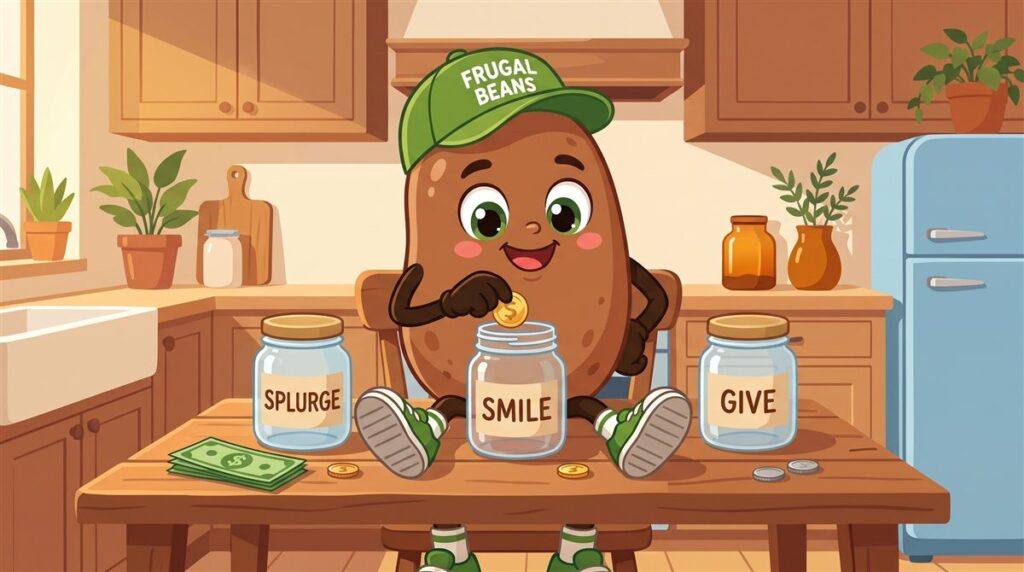
Each payday, children split their pocket money into three clear jars. The Splurge jar is for everyday spending. The Smile jar is for saving toward something bigger; Pape describes it as saving for “something that makes them smile.” The Give jar is for generosity toward people or causes in need.
This mirrors the adult idea of separating money by purpose. A child can see at a glance what is available to spend now and what is set aside for later.
3. Real cash comes before cards
The jars are physical for a reason. Watching coins and bills pile up, or disappear, makes money feel real in a way a balance on a screen does not. Moving to a bank account comes later, once the habit is in place.
4. Talk about money at a weekly family meal
The book’s routine centers on a weekly family meal where everyone sits down together. A few minutes go to checking jobs and paying the kids, and the rest of the time is simply family conversation, which naturally includes money stories and questions. Making money a normal dinner topic lowers the temperature. Children learn that money can be discussed calmly, not whispered about or argued over.
5. Waiting is a skill worth practicing
The Smile jar is really a lesson in delayed gratification. A child who wants a toy, a game or a day out has to save for it over weeks. That wait is the point. Kids learn to set a goal, track progress and decide whether the thing still matters by the time they can afford it.
6. Generosity is part of the plan
The Give jar builds kindness into the routine instead of leaving it to chance. Children choose where their giving goes, which turns generosity into something they own rather than something adults do on their behalf.
7. Aim for ten money milestones before kids leave home
The book frames the bigger goal as a set of ten milestones children should reach before adulthood. Reviewers’ summaries describe topics such as the value of hard work, opening a bank account, buying and selling second-hand items, cooking low-cost meals, volunteering and, for older teens, understanding Australian retirement savings. The milestones run from early childhood through the teen years, so the book grows with a family over time.
What the Book Does Especially Well
The first major strength is accessibility. The tone is direct, warm and energetic, and it is written for parents who may not feel financially confident themselves. You don’t need to understand compound interest to start; you need three jars and a few minutes a week.
The second strength is that it treats kids and money as a behavior problem rather than an information problem. A spreadsheet cannot teach a seven-year-old patience. Repeated small choices can. The jar system gives children those choices every single week.
The third strength is its permission to enjoy money. The Splurge jar exists on purpose. A child who never gets to spend anything learns that money is about guilt and restriction. A defined spending amount creates room for small pleasures without undermining the larger lessons.
Finally, the book treats financial capability as a family skill. Children participate in age-appropriate ways, and both parents can share responsibility. That makes money less mysterious at home and reduces the chance that one adult becomes the only person who understands it.
How U.S. Families Could Adapt the Barefoot Investor for Families
Important: this section is our Frugal Beans adaptation for American households. It is not advice from the book, and it is general information, not financial advice.
Most of the system translates easily. The jobs, the jars and the weekly meal work the same in Ohio as they do in Melbourne. The pieces that need adjusting are the Australian specifics: bank products, pocket money norms, and anything tied to superannuation or Australian tax rules.
Turn pocket money into a simple U.S. allowance
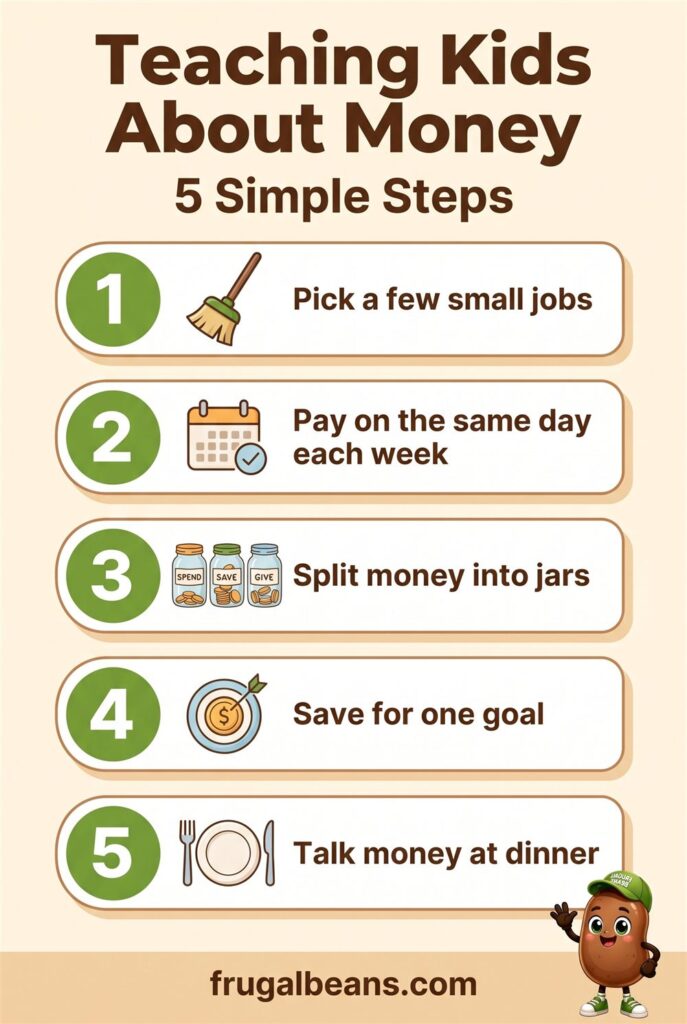
Call it an allowance, call it pocket money; what matters is consistency. Pick a fixed payday that matches your household rhythm, such as Sunday dinner or the day a parent gets paid. Keep the amount modest and predictable. A small, reliable amount teaches more than a large one that shows up only when a parent remembers.
Many American families also separate “helping because we live here” chores, like clearing your own plate, from paid jobs. That’s our suggestion, not a rule from the book, but it can stop kids from asking to be paid for every small task.
Choose your own jar labels
Some U.S. parents prefer plainer names such as Spend, Save and Give, especially with younger kids who may find “Splurge” confusing. The labels matter less than the separation. A clear jar, a strip of tape and a marker are all you need, which keeps this a genuinely frugal project.
Plan the step from jars to a bank account
When the jars are working, you can explore a youth savings account at a local bank or credit union. Look carefully at fees, minimum balances and who controls the account before opening anything. Product names and terms vary, so compare a few options rather than taking any one recommendation at face value.
Use a U.S. resource for age-by-age milestones
If you want an American companion to the book, the Consumer Financial Protection Bureau’s Money as You Grow program offers free money milestones, activities and conversation starters for parents, organized for young children, school-age kids and preteens, and teens to young adults. It pairs well with the jar system and is written for U.S. families.
Swap superannuation lessons for U.S. basics
When the book gets to Australian retirement savings, translate the idea rather than the details. For a U.S. teen, the closest equivalent conversation might be what a first paycheck stub shows, why taxes and payroll deductions appear on it, and what an employer retirement plan is. Keep it descriptive; the goal is understanding, not picking investments.
Kids and Money: Lessons Parents Can Use Too
One quiet benefit of the book is that it nudges parents to look at their own habits. If you ask a child to split pocket money three ways, you may start wondering how your own paycheck is divided. That is a good question to ask.
The original version of this post included several family budgeting habits that are worth keeping, as long as we’re clear they are ours, not the book’s:
- Hold a short weekly check-in. Ten minutes is enough to cover what has been paid, what is coming up and what needs a decision. Keep it neutral; it is not a courtroom.
- Create an irregular-expense fund. Divide annual costs by twelve and set aside that amount monthly. If school supplies and car registration together cost $1,200 a year, saving $100 a month turns a surprise into a planned bill.
- Build a starter emergency buffer. Even a few hundred dollars can stop a minor repair from becoming expensive debt.
- Give kids controlled choices. Let children compare prices and wait for a goal. Avoid rescuing them from every poor choice, while still protecting essentials such as food, safety and education.
- Adjust after real spending. Watch what actually happens for two or three months, then increase, rename or combine categories.
If you are just starting out, our guide to frugal living for beginners covers the household side, and our budgeting tips for a tight budget help you set realistic amounts. Children notice when a family’s money system actually works, and they copy it.
Barefoot Investor for Families Review: Pros and Cons
No book is perfect for every household. Here is a balanced view.
|
Pros |
Cons |
|
Simple, concrete system kids can see and touch |
Written for Australia; banks, pocket money norms and retirement rules don’t match the U.S. |
|
Warm, encouraging tone for parents who feel unsure about money |
Product references date from 2018 and may be out of date |
|
Builds generosity and patience, not just saving |
Paying for jobs may not fit families who see all chores as shared duties |
|
Very low cost to start: jars and a weekly routine |
Some parents find the jar names or the strong opinions take getting used to |
|
Grows with children through milestones up to the teen years |
Less useful for older teens who already earn and bank on their own |
Where readers should use judgment
The book works best as a framework, not a rigid formula. Every household has different income, schedules and values. A system that runs smoothly for a family with a steady paycheck may need loosening for a parent with irregular shifts or freelance income. If a fixed weekly payday is not realistic, pick a rhythm you can keep.
Parents should also apply their own judgment about chores. Some families are comfortable paying for jobs; others prefer that everyone helps without payment and that pocket money is given separately. Neither approach is wrong. The deeper lesson, that money is limited and choices have trade-offs, can be taught either way.
Who Should Read This Book?
The book is particularly suitable for:
- Parents of children from preschool through early teens who want a ready-made system.
- Couples who want a shared starting point for teaching kids and money.
- Grandparents and caregivers who want to support the same habits.
- Parents who feel overwhelmed by financial jargon and want something practical.
It may suit you less if your children are older teens who already have jobs and bank accounts, if you strongly prefer unpaid chores, or if you want a detailed U.S. guide to accounts and taxes. In that last case, the book is still a good source of habits, but pair it with U.S. resources. For more money-saving ideas for the whole household, browse our frugal living tips and our list of ways to save money.
Barefoot Investor for Families Review: FAQ
What is the Barefoot Investor for Families about?
It is a 2018 book by Australian author Scott Pape that shows parents how to teach children about money. The system uses paid, age-appropriate jobs, three jars (Splurge, Smile and Give) and a weekly family money meal, along with ten money milestones for kids to reach before leaving home.
What are the three jars in the Barefoot Investor for Families?
The jars are Splurge for everyday spending, Smile for saving toward a bigger goal, and Give for helping others. Children divide their pocket money between the three each time they are paid.
Is the Barefoot Investor for Families useful outside Australia?
Yes, for the habits. Jobs, jars and family money talks work anywhere. The Australian-specific parts, such as banks and superannuation, need translating; U.S. readers can pair the book with the CFPB’s free Money as You Grow resources.
How much pocket money should kids get?
There is no single right amount. What matters more is that pocket money is predictable, paid on a regular day and small enough that children have to make choices. Start modestly and adjust as your child takes on more responsibility.
The Bottom Line
Our Barefoot Investor for Families review comes down to this: the book succeeds because it makes kids and money a normal part of family life. Jobs connect work and pay, the three jars give every dollar a purpose, and a weekly meal keeps the conversation going.
Use it selectively. Keep the principles of earning, separating, waiting and giving. Translate the Australian details for your own country and bank. Treat the specifics as suggestions, not commandments. A good pocket money system won’t make every week easy, but it gives children something better than a lecture: practice.
Financial Independence Podcasts: 9 Essential Shows Worth Your Time
Financial independence podcasts are one of the easiest ways to learn about money without sitting down with a textbook. Financial independence sounds like a distant, all-or-nothing destination. In practice, it is a household project built from ordinary decisions: spending a little less than you earn, protecting your income, paying down expensive debt, and investing for the future. You do not need a perfect budget or a high salary to begin. You need useful information and a way to turn that information into manageable actions.
Podcasts bring personal-finance ideas into the parts of life where decisions actually happen. You can listen while walking, folding laundry, cooking dinner, or commuting. A good episode may explain an unfamiliar term, show how another family handled a tradeoff, or help you question a habit that no longer fits your goals. This list is a collection of resources, not a ranking. Each of these podcasts has a different voice and emphasis, so the best choice depends on what your household needs right now.
Updated October 2026: We checked every show on this list against its official site and podcast feed. All nine were publishing new episodes in October 2026. An earlier version of this post listed Afford Anything twice and included a show we could not verify, so we replaced those two entries with How to Money and Catching Up to FI, both of which are active and easy to find in any podcast app.
What Financial Independence Means (and Why Podcasts Help)
Financial independence usually means having enough savings and investments, or another reliable source of income, to cover your essential lifestyle without depending entirely on a paycheck. Some people want to leave full-time work early, which is the “RE” in FIRE (Financial Independence, Retire Early). Others want flexibility to change careers, work part time, care for family, or retire with less anxiety. The destination can vary. The useful first steps are similar.
That is where financial independence podcasts earn their place. They are free, they fit into time you already spend on chores, and they let you hear real people work through real decisions. Hearing a host explain a concept three different ways over a few months often sticks better than reading one article once.
Podcasts also have limits. A host does not know your taxes, your workplace benefits, your health, or your tolerance for risk. Treat every episode as a starting point for your own thinking, not personal advice. If you are brand new to managing money, our guide to frugal living for beginners is a gentle place to build the basics alongside your listening.
How to Choose Among Financial Independence Podcasts
Before you press play on any of these financial independence podcasts, identify the question you are trying to answer. If the question is “How do we stop overspending?” a show about behavior may be more useful than one about investing. If you have an emergency fund but do not know how to invest, choose a practical investing discussion. If money conversations cause tension at home, look for patient, judgment-free conversations.
It also helps to match a show to your stage. Some FIRE podcasts assume you already know what an index fund is. Others start from zero. Some lean toward real estate and side businesses, while others focus on mindset and behavior. Sample one or two episodes of any of these podcasts before deciding whether it fits.
The table below is a quick map. Use the right-hand column as a question to carry while you listen.
|
Podcast |
Especially useful for |
A question to carry while listening |
|
ChooseFI |
Building a flexible FI plan |
Which lever can we improve first? |
|
Afford Anything |
Understanding tradeoffs |
What are we willing to exchange for freedom? |
|
The Stacking Benjamins Show |
Broad financial education |
Which basic topic needs attention? |
|
So Money with Farnoosh Torabi |
Mindset and money behavior |
What belief is shaping our choices? |
|
Money Guy Show |
Saving and investing systems |
What should happen to each dollar? |
|
BiggerPockets Money |
Real estate and alternative routes |
What risks would this strategy bring? |
|
Earn & Invest |
Income, investing and purpose |
What is all this money for? |
|
How to Money |
Everyday money decisions |
What can we apply this week? |
|
Catching Up to FI |
Starting later in life |
What can we still change from here? |
9 Essential Financial Independence Podcasts
Each of the financial independence podcasts below is listed with who hosts the show, what it is good for, who it suits, and its status when we checked in October 2026. Links go to each show’s official page.
1. ChooseFI (Brad Barrett and Jonathan Mendonsa)
ChooseFI is a strong starting point if you have heard “financial independence” but are unsure what it means in daily life. The show was founded by Jonathan Mendonsa and Brad Barrett, and Jonathan returned as Brad’s full-time co-host in early 2026. Its central idea is that progress comes from several levers, not one dramatic trick: earning more, spending intentionally, reducing recurring costs, and investing consistently.
The useful lesson for an ordinary household is flexibility. You do not have to copy an extreme savings rate or make every purchase a test of discipline. You might compare insurance, cancel unused subscriptions, or direct a modest raise toward a retirement account. The show helps you see these choices as connected parts of one plan.
Good for: learning the core FI framework, cutting big recurring costs, and hearing from a large community of listeners. Suits: beginners and intermediate listeners who want an optimistic, practical tone. May not suit: anyone who wants deep technical investing analysis every episode. Status: publishing new weekly episodes as of October 2026.
2. Afford Anything (Paula Pant)
Afford Anything focuses on the decisions behind money. Its name comes from host Paula Pant’s idea that you can afford anything, but not everything. That framing helps households discuss priorities without pretending a spreadsheet can choose their values. The show’s description says it covers financial psychology, increasing income, investing, real estate, and entrepreneurship, with new episodes on Tuesdays and Fridays. Joe Saul-Sehy joins Paula for regular listener Q&A episodes.
This is useful when you are balancing travel, a car replacement, family support, and retirement. The answer is not automatically to eliminate every enjoyable expense. Decide which goals deserve money now, which need a sinking fund, and which can wait. A sinking fund is money set aside gradually for a known future expense. Saving $100 a month for a $1,200 annual bill makes it predictable instead of an emergency.
When listening, ask whether a suggested tradeoff fits your values, time horizon, and responsibilities. A financially independent life should contain freedom, not just a larger account balance.
Good for: decision-making frameworks, economics explained plainly, and thoughtful expert interviews. Suits: listeners who like to think through the “why” before the “how.” May not suit: people who want quick tips in under ten minutes. Status: publishing new episodes as of October 2026.
3. The Stacking Benjamins Show (Joe Saul-Sehy and Josh “OG” Bannerman)
The Stacking Benjamins Show takes a conversational, often silly approach to serious personal-finance subjects. Hosts Joe Saul-Sehy, a former financial advisor, and Josh “OG” Bannerman, a Certified Financial Planner, present the show as a chat around a card table in Joe’s mom’s basement. That breadth and humor help listeners who need general education rather than one narrow strategy.
Think of it as a tour of the financial neighborhood: taxes, insurance, retirement accounts, investing, and behavior. You may not need every topic today, but you can notice which one deserves a closer look. If an episode introduces asset allocation, pause and define it. Asset allocation is the way investments are divided among categories such as stocks, bonds, and cash. The mix affects both growth potential and the size of possible losses.
Good for: broad money literacy with a light touch. Suits: people who find most personal finance podcasts dry. May not suit: listeners who want a strictly early-retirement focus or no banter. Status: publishing several new episodes a week as of October 2026.
4. So Money with Farnoosh Torabi
So Money is hosted by Farnoosh Torabi, a financial strategist, TV host and bestselling author. It mixes interviews with authors, entrepreneurs, and public figures with “Ask Farnoosh” episodes that answer listener questions. It fits listeners whose financial questions are partly emotional. Money can represent safety, status, independence, family loyalty, or past hardship, and those meanings affect spending and saving even when the arithmetic is clear.
Consider a couple who repeatedly overspends on takeout. The problem may not be a lack of cooking knowledge. They may be exhausted by work and caregiving, or they may never have agreed on a realistic food budget. A useful response could be preparing two easy meals on the weekend, setting aside a specific convenience-food amount, and removing shame from the discussion.
Use this kind of conversation to identify your money scripts, the repeated beliefs you inherited or developed. Examples include “debt is normal,” “talking about money is rude,” and “spending proves success.” Naming a belief gives you room to choose a different behavior.
Good for: money mindset, careers, couples, and big life transitions. Suits: listeners who want empathy along with strategy. May not suit: people who want a step-by-step FIRE roadmap. Status: publishing new episodes as of October 2026.
5. Money Guy Show (Brian Preston and Bo Hanson)
The Money Guy Show is helpful for people who want an organized order of operations. Hosts Brian Preston and Bo Hanson are financial advisors (yes, our mascot Bo approves of the name). Their signature framework, the “Financial Order of Operations,” is a nine-step sequence for deciding what to do with each dollar next.
Financial independence becomes easier when money has assigned jobs. A household can decide how much to keep in cash, how to handle high-interest debt, how to use workplace retirement benefits, and how to invest additional savings. Suppose your household receives a $300 monthly raise. You could let it disappear into general spending, or split it deliberately: $150 toward a car-repair fund, $100 toward retirement, and $50 for enjoyment. There is no universal split, but deciding before the money is absorbed gives the raise a lasting effect.
Good for: clear priorities and savings-rate thinking. Suits: people who like checklists and want to know “what next.” May not suit: listeners who prefer open-ended philosophical discussions. Remember that the hosts run an advisory firm, so weigh any service mentions as you would any business. Status: publishing new episodes as of October 2026.
6. BiggerPockets Money (Mindy Jensen and Scott Trench)
BiggerPockets Money is one of the best-known FIRE podcasts, hosted by Mindy Jensen and Scott Trench. Many episodes feature listeners walking through their own numbers on the way to early retirement, alongside discussions of real estate, entrepreneurship, and side businesses. These approaches can create income or ownership, but they also require time, knowledge, capital, and tolerance for uncertainty. The lesson is not that every household should become a landlord. It is that financial independence can have more than one route.
Keep a risk checklist nearby. Ask how much money could be lost, how much unpaid work is involved, whether income is dependable, and what happens if the market changes. Rental property is not simply “passive income.” It can involve repairs, vacancies, insurance, taxes, legal requirements, and difficult tenant conversations. If you are weighing property, our free Homeowner Repair Cost Playbook shows how big-ticket repairs can affect the math.
Good for: real-life FI case studies and real estate perspectives. Suits: people curious about multiple paths to FI who like hearing actual numbers. May not suit: anyone who wants to avoid investing and property talk entirely. Status: publishing new episodes several times a week as of October 2026.
7. Earn & Invest (Jordan Grumet, “Doc G”)
Earn & Invest is hosted by Jordan Grumet, a physician known as Doc G, who has worked in hospice care and wrote the book Taking Stock. According to the show’s description, Monday episodes are panel discussions on financial topics and Thursday episodes are interviews with experts. It suits households that have focused on cutting costs and now want to think about the other side of the equation: earning, investing, and what the money is ultimately for.
There is a limit to how much spending can be reduced, but earning capacity may grow through skills, career moves, business income, or better use of workplace benefits. Extra income is most powerful when converted into durable progress. A $5,000 raise can improve life immediately, but directing part of it toward retirement, debt reduction, or a business reserve can improve future choices.
Do not treat higher income as a cure for every problem. More income can bring taxes, work stress, or pressure to spend more. Pair every earning goal with a destination for the money: current needs, security, and meaningful enjoyment. Doc G often brings the conversation back to purpose, which is a helpful counterweight to pure number-crunching.
Good for: investing ideas, career and income, and the meaning behind money. Suits: mid-career listeners and anyone who already has the basics covered. May not suit: complete beginners looking for budgeting fundamentals. Status: publishing new episodes twice a week as of October 2026.
8. How to Money (Joel Larsgaard and Matt Altmix)
How to Money is hosted by best friends Joel Larsgaard and Matt Altmix and distributed by iHeartPodcasts. It replaces a show from our earlier list that we could not verify. The tone is friendly and practical, and the show regularly answers listener questions alongside interviews and news discussion. Among the podcasts on this list, it is one of the more approachable personal finance podcasts for people who want everyday decisions explained, from car buying to retirement accounts.
A daily or near-daily listening habit works well for single concepts such as opportunity cost, lifestyle inflation, or negotiating. Opportunity cost means what you give up when you choose one use for money, time, or attention over another. If you spend $80, the cost may include the emergency-fund contribution that $80 could have supported. Lifestyle inflation is the tendency for spending to rise as income rises. These ideas become useful when you notice them in ordinary decisions, like the ones in our list of simple ways to save money.
Good for: everyday money choices and listener Q&A. Suits: people in their 20s to 40s building good habits, and anyone who likes a relaxed, funny format. May not suit: listeners who want an exclusive focus on early retirement. Status: publishing new episodes several times a week as of October 2026.
9. Catching Up to FI (Bill Yount and Jackie Cummings Koski)
Catching Up to FI is a podcast for late starters of any age. Co-host Bill Yount is an emergency medicine physician who reached financial independence later in life, and Jackie Cummings Koski is a Certified Financial Planner and Accredited Financial Counselor who wrote F.I.R.E. for Dummies. It replaces the duplicate Afford Anything entry from our earlier list.
Like the best FIRE podcasts, this show can encourage listeners who learn from relatable stories. Financial progress is often invisible for months or years, and starting at 45 or 55 can feel discouraging after hearing stories of people who retired at 35. Hearing how others handle debt, saving, career changes, and setbacks later in life can make the process feel attainable.
Borrow the process, not the person’s numbers. Someone else’s rapid debt payoff may make you feel behind. A better comparison is whether your own debt balance, cash reserve, savings rate, or investments are improving. Net worth is what you own minus what you owe. It is one measure, not a measure of your character.
Good for: mindset, catch-up strategies, and realistic stories. Suits: anyone who feels “too late” for FIRE. May not suit: young listeners who want content aimed at their stage. Status: publishing new episodes as of October 2026.
How to Get the Most From Money Podcasts
Listening alone will not change a balance sheet. The best financial independence podcasts give you ideas; your household turns them into results. Keep a note with three headings: idea, why it matters to us, and next step. This turns listening into learning instead of an endless stream of interesting advice.
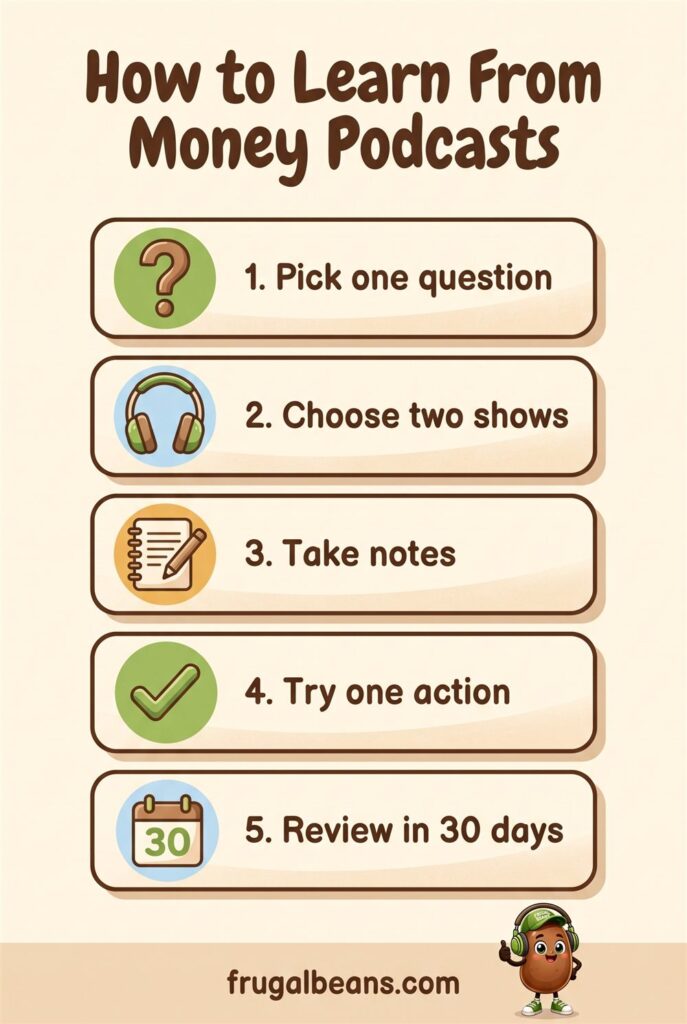
Use this process to turn ideas into household practice:
- Choose one current problem. Start with credit-card debt, an inconsistent emergency fund, or uncertainty about retirement savings.
- Select two contrasting shows. Compare a behavior-focused episode with a systems-focused one, such as So Money and the Money Guy Show.
- Write down one action, not ten. Check an employer match, list annual bills, or set up a $25 automatic transfer.
- Test it for thirty days. If a transfer causes overdrafts, reduce it and repair the system rather than abandoning saving.
- Discuss the decision together. Ask, “What do we want this money to do?” rather than “Why did you spend that?”
- Verify recommendations. Product, investment, tax, and legal details require checking before you act. Podcast discussion is education, not individualized advice.
- Keep an idea parking lot. Revisit interesting strategies during a quarterly review instead of acting on impulse.
The infographic below sums up the five core steps. Print it, or save it on your phone next to your podcast app.
Check the math with free, neutral tools
Many FIRE podcasts talk about compound growth. Instead of taking a host’s example at face value, plug in your own numbers. The SEC’s Investor.gov site offers a free compound interest calculator that shows how regular contributions could grow under the assumptions you choose. For retirement-timing questions, the CFPB’s retirement planning tools are a neutral place to start.
Make listening fit your life
Pair podcasts with tasks you already do: a walk, the dishes, meal prep, or a drive. Speed up playback if one of your podcasts feels slow, and skip episodes that do not apply to you. There is no prize for finishing a back catalog. If you listen while cooking, you are already practicing one of the best habits in our guide to saving money at home.
Hold a monthly money meeting
Use an episode as a prompt for a short monthly check-in. Review cash savings, high-interest debt, and long-term investments. Then name one win and one adjustment. A $400 debt reduction, a new automatic transfer, or a calm partner conversation all count. If money is tight right now, our budgeting tips for a tight budget can help you find the first dollars to work with.
Financial Independence Podcasts vs. Other Ways to Learn
Podcasts are not the only tool, and they work best in combination. Books go deeper on a single idea. Free government resources offer neutral, non-commercial explanations. A fee-only advisor can look at your specific situation. Personal finance podcasts sit in the middle: they are free, regular, and good at keeping money on your mind week after week.
Be aware that most podcasts are supported by advertising. A sponsor mention is not an endorsement of that product for your household. Compare any product against alternatives, read the fees, and decide on your own timeline. The same caution applies to guests who are promoting a book, course, or business.
Finally, remember that frugality and financial independence are partners. Lower recurring costs reduce how much you need to save, and every dollar saved can work toward your goals. Our collection of frugal living tips pairs well with almost any show on this list.
Financial Independence Podcasts: Frequently Asked Questions
What are the best financial independence podcasts for beginners?
ChooseFI, How to Money, and The Stacking Benjamins Show are approachable starting points because they explain terms as they go and cover a wide range of topics. If you are starting later in life, Catching Up to FI speaks directly to that situation. Try one episode of each and keep the one whose tone you enjoy.
Are FIRE podcasts only for people who want to retire early?
No. FIRE podcasts focus on building enough savings and investments to give you choices, and many listeners never plan to stop working entirely. The same habits help with changing careers, working part time, caring for family, or simply feeling less anxious about money.
Is it safe to follow investment advice from podcasts?
Treat podcast content as education, not personal advice. Hosts cannot see your taxes, debts, or goals. Use episodes to learn concepts, check numbers with neutral tools such as Investor.gov, and talk with a qualified professional before making big decisions.
How many money podcasts should I listen to?
One or two is plenty. Listening to many podcasts at once can create information overload and conflicting advice. Pick one show that matches your current problem and one with a contrasting viewpoint, then take one action at a time.
The Bottom Line
These nine financial independence podcasts offer different doors into the same goal. ChooseFI introduces the framework. Afford Anything clarifies tradeoffs. The Stacking Benjamins Show broadens your vocabulary. So Money examines behavior. The Money Guy Show supports systems. BiggerPockets Money explores real estate and alternative paths. Earn & Invest connects income, investing, and purpose. How to Money tackles everyday choices. Catching Up to FI shows that it is never too late to start.
You do not need to listen to all nine podcasts or follow every strategy. Start with one question, take one measured action, and review what happened. Financial independence is not a contest to imitate another household. It is the growing ability to make choices because your money supports your needs, priorities, and future.
Let the podcasts provide ideas. Let your household values set the direction. Let your own numbers decide the pace.
Types of Debt: 8 Essential Kinds Explained Simply
The types of debt you carry shape how much you pay, how flexible your payments are, and what you could lose if money gets tight. Debt is simply money you borrow now and promise to repay later, usually with interest or fees. Most households use some of it. A mortgage may make a home possible, an auto loan may get you to work, and a credit card may cover a bill before payday.
Debt is not automatically good or bad. The important questions are what it costs, what secures it, how flexible the payments are, and whether it fits your household budget. A credit card balance behaves differently from a fixed-rate mortgage. A medical bill may be negotiable, while a payday loan can become expensive within weeks.
This guide explains eight common types of household debt in plain language. It also covers good debt vs bad debt, the difference between secured and unsecured debt, and how to build a debt inventory so you can decide which balances deserve attention first. No judgment here: the goal is a clear list and a calm plan.
Types of Debt at a Glance: A Quick Comparison
Before digging into each one, here is how the eight most common types of debt compare. Use the table as a map, then read the sections below for the details that matter when you are planning a debt payoff.
|
Type of debt |
How it usually works |
Common cost pattern |
Main risk |
|
Credit card debt |
Borrow, repay, and borrow again up to a limit |
Variable interest; often high |
Minimum payments can prolong repayment |
|
Mortgage debt |
Long-term loan used to buy a home |
Fixed or adjustable interest |
The home secures the loan |
|
Auto loan debt |
Fixed loan used to buy a vehicle |
Regular payments for a set term |
The vehicle can be repossessed |
|
Student loan debt |
Borrowing for education |
Interest may accrue during pauses |
Payments can last for years |
|
Personal installment debt |
Lump sum repaid in installments |
Interest and possible fees |
Long terms can raise total cost |
|
Medical debt |
Balance owed for health care |
May start interest-free |
Billing errors and collections matter |
|
Payday or title debt |
Short-term loan based on income or a vehicle |
High fees and rollover costs |
A small emergency can become a cycle |
|
Buy now, pay later or retail debt |
Purchase split into several payments |
May be interest-free, with conditions |
Several plans can overwhelm cash flow |
Two ideas run through the whole table. First, is the debt secured by something you own? Second, is it revolving (reusable credit with no set end date) or installment (scheduled payments over a fixed term)? Once you can answer those two questions for every account, the rest of the plan gets much easier.
8 Types of Debt Explained
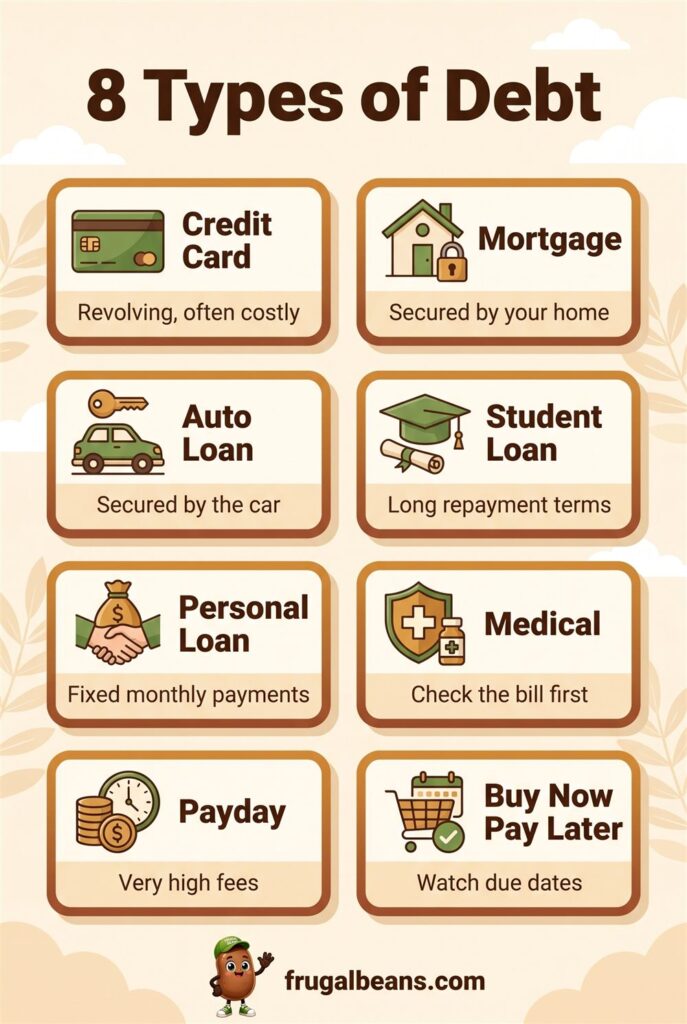
Here are the eight types of debt most U.S. households run into, with what each one is, how it costs you money, and what to check on your own statements.
1. Credit Card Debt
Credit card debt is revolving debt. You receive a credit limit, spend against it, repay some or all of the balance, and regain available credit as you pay. Unlike an installment loan, it has no fixed payoff date unless you create one.
Credit cards can be useful when you pay the statement balance in full each month. Once you carry a balance, interest can make ordinary spending much more expensive. The annual percentage rate, or APR, is the yearly cost of borrowing shown as a percentage. Card APRs are often variable, so the rate can change.
Here is a simple illustration. If a card balance is $4,000 and the APR is 24%, interest alone works out to roughly $80 in the first month ($4,000 × 24% ÷ 12), depending on how the issuer calculates it. A minimum payment may keep the account current but stretch repayment over years. Charging new purchases while paying down the balance makes the job harder.
Review the balance, APR, minimum payment, due date, annual fee, promotional deadline, and penalty rate. A balance transfer can lower interest temporarily, but it may include a fee and an expiration date. Treat the lower rate as a chance to finish the balance, not as room for new spending.
2. Mortgage Debt
A mortgage is an installment loan used to buy or refinance real estate. It is secured debt because the home is collateral. If payments stop and the default is not resolved, the lender may eventually pursue foreclosure under applicable rules.
Mortgage payments commonly include principal and interest. Principal reduces what you borrowed. Interest is the cost of using the lender’s money. A payment may also include property taxes, homeowners insurance, mortgage insurance, or association charges, although those items are not all part of the loan itself.
A fixed-rate mortgage keeps its rate steady for the agreed term. An adjustable-rate mortgage can change after an initial period according to the contract. A lower starting payment is not necessarily a lower long-term cost, so check when adjustments occur and whether the future payment could fit your budget.
Mortgage debt often has a lower rate than credit card debt, but it is much larger and lasts longer. Paying extra principal can reduce total interest, yet a household should usually maintain an emergency reserve and address more expensive debt first. Be careful about using home equity to pay off ordinary spending balances: unsecured debt becomes debt backed by your home.
3. Auto Loan Debt
An auto loan finances a car, truck, or motorcycle and is usually secured by the vehicle. You make fixed payments over a set term while the lender holds a legal interest in the vehicle until repayment.
The monthly payment is not the whole cost. Consider the vehicle price, down payment, taxes, fees, rate, loan term, and total repayment. A longer term lowers the payment but increases interest and may leave you owing more than the vehicle is worth. This is called being upside down, or having negative equity. If the car is totaled or sold early, you may need extra money to cover the gap.
Include fuel, maintenance, insurance, registration, parking, and repairs in the transportation budget. If the payment works only when nothing goes wrong, the loan is probably too large.
4. Student Loan Debt
Student loans pay for tuition, fees, books, living costs, or other education expenses. They may come from a government program, school, bank, or private lender. Terms differ, so identify who owns and services each loan and read the current repayment notice. Federal repayment programs have changed several times in recent years, so rely on your servicer’s latest information rather than older articles.
Some student loans have fixed rates and structured repayment options. Interest may accrue while you are in school, during a grace period, or during certain pauses. If unpaid interest is added to the principal, future interest is charged on a larger balance. That process is called capitalization.
Student debt may limit choices such as changing careers, working fewer hours, or saving for a home. Record the balance, rate, payment, repayment plan, and special terms. A temporary pause does not necessarily freeze the balance.
If you have several loans, compare their rates and protections before making extra payments. The highest-rate loan may be the mathematical priority, while a loan with valuable flexibility may deserve a different approach. Cost and stability both matter.
5. Personal Installment Debt
A personal loan gives you a lump sum that you repay through scheduled installments. People use these loans for renovations, emergencies, moving costs, large purchases, or debt consolidation. The loan is commonly unsecured, so approval is based largely on credit history and income.
Personal loans may have a fixed rate and predictable payoff date, which can be easier to manage than a credit card. Check the origination fee, late fee, prepayment terms, total repayment, and whether the advertised rate requires excellent credit.
Consolidation can simplify payments and reduce interest if the new loan is genuinely cheaper. The plan fails if old cards are used again or if the new term raises total repayment. Compare total dollars, not only the monthly payment. Loans marketed for poor credit may include high rates, automatic withdrawals, or add-on products, so read the agreement first.
6. Medical Debt
Medical debt is money owed to a hospital, clinic, physician, laboratory, ambulance provider, or medical financing company. It can come from an emergency, deductible, coinsurance, denied claim, or service that insurance did not cover.
Review a medical bill before placing it on a credit card or taking a loan. Compare it with your insurer’s explanation of benefits. Look for duplicate charges, services you did not receive, incorrect insurance information, and payments not credited. Ask the billing office to explain unfamiliar items.
Providers may offer payment plans, discounts, financial assistance, or hardship reviews. Ask before accepting a high-interest account, and confirm whether a missed payment cancels a no-interest arrangement. Rules on medical debt and credit reports have also shifted: a federal rule that would have removed most medical bills from credit reports was struck down by a court in 2025, while some states have their own limits. Check the current rules where you live.
Medical debt often comes from a necessary service rather than optional spending. Keep copies of conversations and confirm a collections balance in writing before agreeing to payment terms.
7. Payday and Title Debt
Payday loans are small, short-term loans usually repaid from a future paycheck. Title loans use a vehicle title as security. Both may appear convenient during an emergency, but their fees can translate into extremely high annualized costs. The Consumer Financial Protection Bureau’s explainer on payday loans notes that a typical two-week loan with a fee of $15 per $100 borrowed equates to an APR of almost 400 percent.
The timing creates much of the danger. If the full balance is due in two to four weeks, there may not be enough income left after essentials. Rolling the loan over adds another fee without fixing the cash shortage. A borrower may repay the original amount and still need another loan for rent, food, or utilities. With a title loan, nonpayment can put the vehicle at risk.
Before using this debt, ask about a bill extension, utility hardship plan, employer advance, or community assistance. If you already have one, calculate the exact payoff and rollover charges, then request a written repayment option.
8. Buy Now, Pay Later and Retail Financing
Buy now, pay later (BNPL) plans, store cards, furniture financing, and appliance financing divide a purchase into installments. According to the CFPB’s guide to buy now, pay later loans, many BNPL loans don’t charge interest, but most charge late fees, and a common plan splits the cost into four payments. Other retail financing may charge interest, deferred interest, or a high rate after a promotion ends.
The main risk is fragmentation. Several small plans can create a substantial monthly obligation, and withdrawals on different dates can cause overdrafts.
Check whether the plan reports to credit bureaus, what happens after a missed payment, whether interest is charged retroactively, and whether a return cancels the obligation. List each plan, balance, and final payment date. Treat the full purchase price as debt before accepting a split-payment option.
Good Debt vs Bad Debt: Which Types of Debt Help You?
You will often hear the phrase good debt vs bad debt. The usual idea is that “good” debt helps you build something lasting, like a home or an education, while “bad” debt pays for things that lose value quickly at a high interest rate. It is a useful starting point, but real life is messier than two labels.
What usually makes debt “good”
Debt tends to work in your favor when the cost is reasonable, the payments fit comfortably in your budget, and the thing you bought keeps its value or raises your earning power. A mortgage on a home you can afford, or a modest loan for training that leads to steadier work, often fits this description.
What usually makes debt “bad”
Debt tends to work against you when the cost is high, the term drags on, or it pays for everyday spending that is gone long before the balance is. A credit card balance from last year’s groceries, a payday loan rolled over several times, or a stack of split-payment plans for small purchases usually lands here.
Why the labels are not the whole story
The good debt vs bad debt line can blur in real life. A “good” mortgage becomes a burden if the payment leaves no room for repairs. An expensive degree that does not lead to higher income can feel heavy for decades. And a credit card paid in full every month is a convenient tool, not bad debt at all. So when you weigh good debt vs bad debt, ask three plain questions: What does it cost in total? Can I make the payment in a bad month? Will I still be glad I borrowed once the money is spent? The honest answers matter more than the category.
Secured and Unsecured Debt: Two Types of Debt Compared
The split between secured and unsecured debt is one of the most practical ways to sort what you owe, because it tells you what is at stake if you fall behind.
Secured debt
Secured debt is backed by collateral, something of value the lender can claim if the loan is not repaid. Mortgages (backed by the home), auto loans (backed by the vehicle), and title loans (backed by the vehicle title) are the classic examples. Because the lender has that backup, secured loans often carry lower rates. The trade-off is serious: missed payments can eventually cost you the house or the car.
Unsecured debt
Unsecured debt has no specific collateral. Most of the types of debt people juggle every month sit here: credit cards, most personal loans, medical bills, many student loans, and most BNPL plans fall in this group. Lenders rely on your credit history and income instead, so rates are often higher. Falling behind will not lead straight to repossession, but it can bring late fees, a damaged credit report, collection calls, and, in some cases, a lawsuit.
Why it matters for your plan
Understanding secured and unsecured debt helps you set priorities when money is short. Keeping the mortgage or rent and the car you need for work current usually comes first, because losing those assets creates new, bigger problems. It also explains why turning unsecured debt into secured debt, such as using a home equity loan to pay off credit cards, deserves careful thought: a lower rate can help, but your home is now on the line for spending that used to be unsecured.
How Home Repairs Turn Into High-Interest Debt
One of the most common ways households slide into high-interest debt has nothing to do with shopping. It is the surprise repair, and it can push even careful households into the costliest types of debt. A furnace quits in January, the water heater leaks, or the roof starts dripping, and the bill lands on a credit card or a quick loan because there is no other option that week.
Before you borrow for a big repair, check whether the repair is worth making at all. Our free repair or replace calculator compares the quote with the cost of a new unit and the unit’s age, which can keep you from taking on new types of debt for a system that is about to fail anyway.
Those balances are easy to underestimate, and they can quietly stall a debt payoff plan you already started. The repair is necessary, so it does not feel like “spending,” yet it can sit on a card for months at a high rate. The best defense is knowing what is coming. Major home systems wear out on fairly predictable schedules, so a small monthly set-aside can turn a future emergency into a planned expense.
Our free Homeowner Repair Cost Playbook lists typical lifespans and repair costs for the big systems in a house, so you can see which ones are getting close and start a repair fund before they fail. For everyday ways to free up that money, see our guide on how to save money at home.
How to Identify the Types of Debt You Have
Knowing the definitions is helpful, but the real work is sorting your own accounts. Start a debt inventory using statements, loan portals, collection notices, and paper agreements. A notebook or simple spreadsheet is enough. For each account, record:
- The lender, provider, or collector, and the account type.
- The balance, interest rate, minimum payment, and due date.
- Whether the rate is fixed or variable, and when it can change.
- The remaining term and estimated payoff date.
- Any collateral, fees, promotional deadline, or late-payment consequence.
- Whether the account is current, past due, deferred, or in collections.
Next, run two tests on every line. Ask whether the debt is secured: if a home, vehicle, or title backs it, missed payments can put that asset at risk. Then ask whether it is revolving or installment. Revolving debt offers reusable credit and often no natural end date. Installment debt has scheduled payments and a defined term.
Once each account carries those two labels, you can see the shape of your debt at a glance. Sorting by secured and unsecured debt also shows you which accounts carry the most at stake. Many people find this step alone lowers their stress, because one confusing pile becomes a short list of specific accounts with specific rules. If your budget is already stretched, our tips for saving money on a tight budget can help you find room for extra payments.
Debt Payoff Priorities: Which Debt to Pay First
With the inventory done, you can choose a debt payoff order. Different types of debt call for different priorities. There is no single right answer, but there is a sensible sequence that protects your household while you make progress.
Step 1: Protect essentials
Keep secured accounts current when losing the asset would threaten housing, transportation, or work. Cover the minimum payment on every current account before sending extra money anywhere, so you avoid late fees and credit damage while you plan.
Step 2: Deal with the most urgent costs
Payday and title loans, and any promotional balance about to switch to a high rate or deferred interest, usually deserve early attention because their costs climb fastest. Ask about written repayment options before the next rollover.
Step 3: Choose one payoff method
The avalanche method sends extra money to the highest-rate balance first and usually minimizes total interest. The snowball method targets the smallest balance first and builds momentum through quick wins. Either one beats repeatedly changing plans, because a steady debt payoff method is what actually shrinks balances.
Step 4: Keep going and roll payments forward
When one balance is gone, add its payment to the next target. That rolling effect is what makes a debt payoff plan speed up over time, whichever method you choose.
Practical Tips for Managing All Types of Debt
Protect cash flow. Set reminders or automatic minimum payments, but check the account before withdrawals. Keep a small buffer so one timing error does not create a fee.
Do not confuse consolidation with deletion. A new loan may simplify payments, but compare total repayment, fees, and the risk of running up old accounts again.
Ask questions early. Lenders, medical providers, and servicers are often more willing to discuss options before an account is seriously delinquent. Request changes in writing and keep records.
Build a small emergency reserve. Even a modest cushion can reduce the need for payday loans or credit card borrowing when a tire fails, a child needs care, or a utility bill arrives unexpectedly. Our list of ways to save money is a good place to find the first few dollars, and frugal living for beginners covers the habits that keep that cushion growing.
Stop adding to the pile, whatever types of debt you carry. While you pay down balances, pause new split-payment plans and keep cards out of easy reach for everyday spending. Progress is much faster when the balance is only moving in one direction.
Types of Debt: Frequently Asked Questions
What are the main types of debt?
The most common types of debt for U.S. households are credit cards, mortgages, auto loans, student loans, personal loans, medical debt, payday and title loans, and buy now, pay later or retail financing. They can also be grouped by whether they are secured or unsecured and whether they are revolving or installment.
Is a mortgage good debt?
A mortgage is often considered good debt because it is usually lower-cost and helps you build home equity. It stays “good” only if the payment, taxes, insurance, and repairs fit your budget with room to spare. A house that leaves no margin for emergencies can push other spending onto high-interest cards.
What is the difference between secured and unsecured debt?
Secured debt is backed by collateral, such as a home or car, that the lender can claim if you stop paying. Unsecured debt, like credit cards and most medical bills, has no collateral, so it often costs more, but falling behind does not lead directly to losing a specific asset. Knowing which of your accounts are secured and unsecured debt helps you decide what to protect first.
How do I decide which debt to pay off first?
Keep essential secured accounts and all minimum payments current first. Then tackle the fastest-growing costs, such as payday loans or expiring promotions. After that, pick either the avalanche method (highest rate first) or the snowball method (smallest balance first) and stick with it.
The Bottom Line
The types of debt you have affect interest cost, payment flexibility, payoff timeline, and what you could lose after a default. Credit cards are revolving and often costly. Mortgages and auto loans are secured by property. Medical bills may be negotiated, while payday, title, and split-payment plans carry their own distinct risks.
Whether you are weighing good debt vs bad debt or sorting secured and unsecured debt, make a complete list before choosing a debt payoff strategy. Know each balance, rate, payment, due date, and consequence. Keep essential accounts current, use extra money deliberately, and build a small cushion so the next surprise does not land on a card. Understanding your debt turns one confusing burden into a set of specific, manageable decisions.
Ways to Save Money: 30 Simple Habits That Repeat Every Month
The best ways to save money are not dramatic one-time sacrifices; they are small, boring habits that repeat every month without much thought. Money feels tight for many ordinary households even when no single expense looks outrageous. Rent or a mortgage takes its share, utilities arrive on schedule, the car needs fuel and repairs, and small purchases fill the gaps between paychecks. When prices rise or income changes, it can feel as though you are always reacting instead of deciding.
This guide collects 30 practical ways to save money, grouped by where the money actually goes: food, home and utilities, transportation, bills and subscriptions, shopping, and the money systems that hold it all together. None of them require extreme coupon binders or eating rice for a month. Most take an afternoon to set up and then keep paying off quietly.
The Frugal Beans Mindset: Give Every Dollar a Job
Here at Frugal Beans, the whole idea fits in one sentence: treat every dollar as a useful resource and give it a clear job before it disappears. That does not mean buying the cheapest thing every time or refusing every pleasure. It means noticing where money goes, protecting what matters, and finding repeatable ways to make a limited income go further.
Frugality is different from being cheap. Being cheap focuses only on the lowest price, even when the result is poor quality, unsafe or wasteful. Being frugal considers total value: price, usefulness, durability, time, risk and enjoyment. A $12 item that sits unused is not a bargain, and a durable item that lasts for years may cost less in the long run.
Before trying any of the ways to save money below, ask three quick questions:
- What do we have? Income, savings, useful possessions, skills and support, without pretending any of them are bigger than they are.
- What do we need money to do? Housing, food, transportation, health, debt payments and goals.
- What can change? Expenses, habits, timing and income that can be adjusted without harming safety or dignity.
If you are brand new to this, our guide to frugal living for beginners walks through the first month step by step.
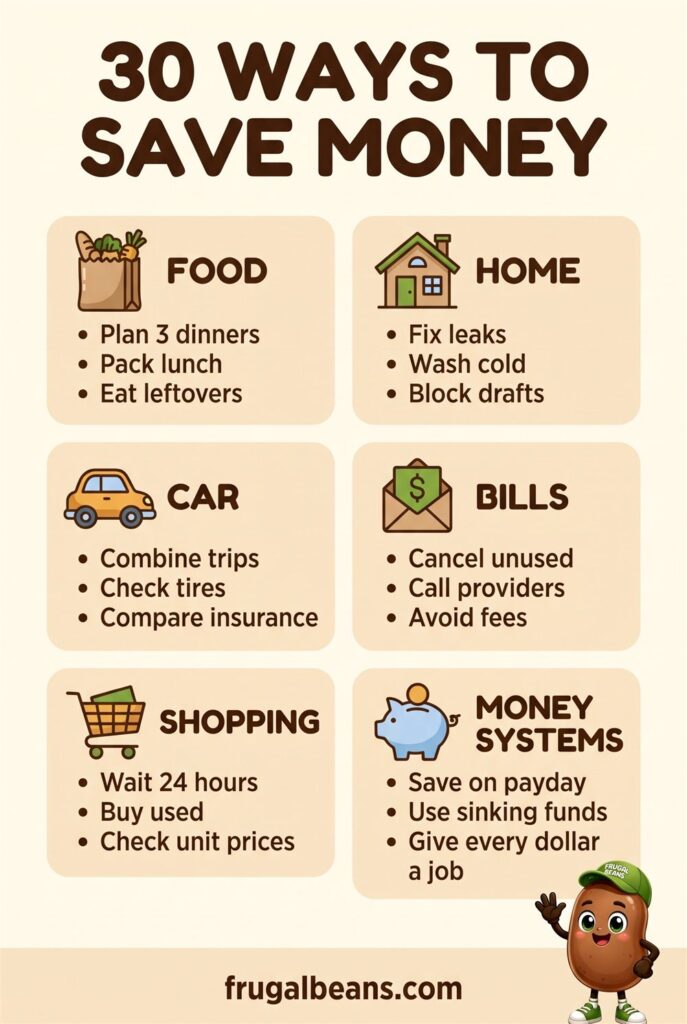
30 Ways to Save Money at a Glance
Use this one-page summary as a checklist. Pick three ideas that fit your household, try them for a month, and keep the ones that stick. The sections below explain the reasoning behind each habit and how to set it up.
Ways to Save Money on Food
Food is where many people look first, and for good reason: it is a frequent purchase, so a small improvement repeats dozens of times a month. Groceries are only one part of the picture, but they are a good place to build momentum.
1. Plan Three Dinners Before You Shop
You do not need a full weekly meal plan. Pick three flexible dinners, check what is already in the fridge, freezer and pantry, and build the list from there. Planning a few meals prevents the common cycle of buying ingredients for something new while older food quietly expires.
2. Pack Lunch Most Workdays
A packed lunch is one of the most reliable small ways to save money because it repeats every workday. Suppose a bought lunch costs $12 and a packed one costs about $4 in groceries. That is $8 a day, or roughly $160 over 20 workdays. Your numbers will differ, but the math is worth doing for your own routine.
Make it easy: cook a little extra at dinner, portion it straight into containers, and keep a few grab-and-go items such as fruit, carrots or boiled eggs ready for busy mornings.
3. Keep an “Eat First” Bin and Eat Leftovers
Put a clear bin on an eye-level fridge shelf for leftovers and produce that needs to be used soon. Food you throw away is money you already spent. Freeze extra portions in labeled containers rather than hoping everyone will want the same leftovers on the fourth day.
4. Keep Two Default Cheap Dinners for Tired Nights
Expensive takeout usually happens when everyone is exhausted and nothing is ready. Choose two low-effort meals you can always make, such as bean tacos, pasta with vegetables, or eggs and toast, and keep the ingredients on hand. If you are weighing paid convenience instead, see whether meal delivery services are worth it for your household.
5. Compare Unit Prices and Try Store Brands
The shelf tag often shows a unit price, the cost per ounce or per count. Use it to compare package sizes and brands. Store brands and seasonal produce can stretch a grocery budget, but a bigger package is only a bargain if you actually use all of it.
Ways to Save Money at Home on Utilities
Most households save money on utilities through behavior and maintenance rather than gadgets. These habits cost little or nothing and work in both owned and rented homes. For a deeper room-by-room walkthrough, read our guide on how to save money at home.
6. Fix Drips and Running Toilets Quickly
A small leak runs all day, every day. Replacing a worn washer or flapper is often a simple job, and fixing it promptly protects cabinets and floors from water damage too.
7. Wash Full Loads in Cold Water
Run the washer and dishwasher only when they are full, and use cold water for everyday clothes when the care label allows it. Air-dry when convenient, and clean the dryer lint screen after every load so air moves freely.
8. Nudge the Thermostat and Dress for the Season
Move the thermostat a few degrees toward the outdoor temperature, especially when you are asleep or away, and add a sweater or a fan instead. Close doors to rooms that do not need the same temperature.
9. Block Drafts Before Buying Upgrades
A draft stopper or rolled towel under an exterior door is a cheap first step. Before spending $200 on a device to save $20 a year, check how long it would take to pay for itself. Simple habits like this usually pay back faster than equipment.
10. Maintain What You Own
Clean filters on schedule, replace worn seals, and follow appliance care instructions. The biggest home bills come from the furnace, air conditioner, water heater and major appliances failing at the worst moment. Our free Homeowner Repair Cost Playbook lists typical lifespans and repair costs so you can plan a replacement instead of paying emergency rates.
Ways to Save Money on Transportation
Transportation is a structural expense, so when you save money here, the improvements tend to be larger than any single shopping trick. Start by calculating the full monthly cost of each vehicle: payment, fuel, insurance, maintenance, repairs, parking and registration. A low sticker price does not guarantee a low total cost.
11. Combine Errands Into One Trip
Group errands by location and do them in one loop instead of several separate drives. Fewer trips means less fuel and less wear on the car, and it often cuts impulse stops as well.
12. Keep Up With Basic Car Maintenance
Check tire pressure monthly, follow the oil-change schedule in your owner’s manual, and deal with small problems before they become big ones. Smooth driving helps too: the U.S. government’s fuel economy site explains how aggressive driving lowers gas mileage and what to do instead.
13. Compare Car Insurance Every Year
Get quotes at renewal, ask about discounts you may qualify for, and review your coverage levels. Keep the protection you genuinely need; becoming dangerously underinsured is not frugality.
14. Try One Car-Free Option
Where it is practical and safe, compare driving with public transit, cycling, walking or carpooling for one regular trip. Some households find they can share one vehicle instead of two. If a car is essential, prioritize reliability and reasonable operating costs over status.
Ways to Save Money on Bills, Subscriptions and Fees
Recurring bills deserve attention because a successful cut repeats automatically. Trimming a $60 monthly bill frees $720 over a year, more than skipping a long list of small purchases, and you only have to do it once.
15. Cancel Subscriptions You Did Not Use Last Month
Scroll through your bank and card statements and list every recurring charge: streaming, apps, software, memberships and boxes. Cancel or pause anything you did not use last month. Cancel through the company’s actual billing system, then check your next statement to confirm the charge stopped.
16. Turn Off Auto-Renew When You Start a Free Trial
Free trials are designed to roll into paid plans. Set a calendar reminder or switch off auto-renew on day one, then decide deliberately whether the service is worth keeping.
17. Call Providers and Ask for a Better Rate
Phone, internet and insurance companies often have lower plans than the one you are on. Ask what options exist, remove features you do not use, and compare competing offers. A 20-minute call can lower a bill for every month that follows.
18. Stop Paying Bank Fees
Check for monthly maintenance fees, overdraft charges, out-of-network ATM fees and paper-statement charges. Set up low-balance alerts and keep a small cushion in checking so a timing mistake does not set off a chain of fees. If your account keeps charging you, look for one that does not.
19. Line Up Due Dates With Payday
A household can earn enough over a month and still run short in a particular week because bills are due before payday. Put every bill on one calendar and ask providers to move due dates where possible. Autopay protects against late fees, but still review the account monthly for charges you do not recognize, renewals that went up in price, and duplicate services.
20. Review Housing at Renewal Time
Housing is usually the biggest bill. If rent or a mortgage takes too much of your income, options include a compatible housemate, moving at lease renewal, a smaller place, or living closer to work. Moving has its own costs, so compare the full picture rather than assuming a lower monthly payment is automatically better.
Smart Shopping: Small Ways to Save Money on Things You Buy
When you shop, you save money less by finding the perfect coupon and more about adding a little friction between the urge and the purchase.
21. Use a 24-Hour Pause
Wait a day before buying anything nonessential above a set amount, and keep a 30-day list for bigger purchases. During the pause, write down the problem the item solves and where it will live. If you cannot answer, the purchase may be a response to advertising rather than a need.
22. Remove Saved Cards and Unsubscribe From Promo Emails
One-click checkout and daily sale emails make spending effortless. Delete saved payment details from shopping apps and unsubscribe from promotional messages. These changes do not require willpower; they simply add a moment for a deliberate decision.
23. Buy Used When It Is Safe and Easy to Inspect
Clothing, furniture, tools, books and many household goods are good secondhand candidates. Buy used when the condition is clear and safety is not in question, and skip anything just because it is cheap.
24. Sell or Donate What You Do Not Use
Photograph items honestly, research a realistic price, and account for platform fees and your time. Bundle low-value items when that makes listing worthwhile. The goal is space and useful cash, not turning your home into a resale warehouse.
25. Borrow Before You Buy
Libraries, tool-lending programs, neighbors and friends can cover occasional-use items. Agree on return dates and who is responsible for damage so that saving money does not create conflict.
Money Systems That Make Saving Automatic
The first 25 habits free up money. These last five make sure that money actually goes somewhere useful instead of quietly disappearing into everyday spending. This is the “give every dollar a job” part of the Frugal Beans approach.
26. Take a Simple Cash-Flow Snapshot
Gather two or three months of bank statements and bills, and group spending into broad categories. You do not need to explain every coffee. A basic snapshot might look like this:
|
Category |
Question to ask |
|
Take-home income |
Is this a conservative, dependable number? |
|
Housing and utilities |
Is the home affordable for our current income? |
|
Transportation |
What is the full cost, including repairs and insurance? |
|
Food and household supplies |
Which purchases are planned, and which are rushed? |
|
Debt minimums |
Which balance costs the most interest? |
|
Flexible spending |
Which choices provide real value? |
|
Savings and extra debt payment |
What future problem is this money preventing? |
The basic equation is simple: take-home income minus essentials, flexible spending and goals equals what is left. If the result is negative, do not blame yourself. Look for the largest pressure points first, because a rent payment, car loan or high-interest balance can matter more than a dozen small cuts.
27. Move Savings on Payday, Automatically
Set an automatic transfer to savings for the day your paycheck lands. When saving is the default, you do not have to rely on whatever is left at the end of the month. Start with an amount you can sustain, even if it is small, and raise it when a bill goes away.
28. Build an Emergency Fund in Stages
An emergency fund is cash set aside for necessary, unexpected expenses or a loss of income. Start with a small starter goal, then work toward one month of essential expenses and eventually a larger cushion suited to your job stability and family. Keep it accessible but separate from everyday spending. The CFPB’s guide to building an emergency fund has practical tips for getting started.
29. Use Sinking Funds for Predictable Bills
A sinking fund is money set aside gradually for an expense you know is coming: annual insurance, car registration, school supplies, holiday gifts. Divide the yearly cost by twelve and save that amount each month. An emergency is unplanned; a yearly bill is not, even if it feels like a surprise.
30. Pay Down High-Interest Debt With a Clear Order
Keep every minimum payment current, then send extra money to one balance at a time. The debt avalanche method targets the highest interest rate first and usually saves the most interest. The debt snowball method targets the smallest balance first for quicker wins. Pick the one you will stick with.
For example, suppose a household can add $250 a month beyond the minimums. It applies the $250 to the top-priority balance, and when that balance is gone, it rolls the whole payment into the next one. The key is keeping the total payment the same as balances disappear, rather than treating freed-up money as permission to spend more.
Creative Ways to Save Money Without Feeling Deprived
Sustainable frugality is not built on constant refusal. A plan that cuts every enjoyable thing usually ends in a rebound spending spree. These creative ways to save money keep the plan livable.
Protect What You Value, Cut What You Forget
Sort your spending into three groups: needs that protect safety, health, housing and work; values you deliberately choose because they improve your life; and habits that are mostly automatic or forgettable. Cut the forgettable spending first; that is where you save money without missing anything. If a weekly dinner with friends matters to you, keep it and cancel the streaming service nobody watches.
Use a Replacement Ladder
Swap an expensive habit for a slightly cheaper one before going to the cheapest option. For example, move from frequent restaurant delivery to pickup, then from pickup to one planned restaurant meal a week, while keeping easy meals at home. Gradual steps are more likely to last than strict rules that clash with real schedules.
Watch Out for Lifestyle Inflation
When income goes up, it is easy for spending to follow: a bigger apartment, a nicer car, more upgrades. Enjoying part of a raise is reasonable. Decide before it arrives how much will go to savings or debt, how much to a meaningful improvement, and how much to everyday flexibility. When a loan ends, redirect the old payment to a goal for a few months before deciding what to do with it.
Earn a Little More
Frugality has a floor. You can only cut so far before it harms your health or work. Asking for a raise with evidence of your results, picking up a side project, or selling unused items can add more breathing room than eliminating another modest pleasure. Give that extra income a specific job so it does not dissolve into ordinary spending. For more ideas when the budget is already lean, see our ways to save money on a tight budget.
A Monthly Routine to Keep These Ways to Save Money Working
A short monthly check-in turns good intentions into a habit. Pick one evening or weekend morning and keep the review short enough that you will actually repeat it.
- Close last month. Check balances, confirm bills cleared, and compare actual spending with the plan. Look for patterns, not individual sins.
- List next month’s known costs. Rent, utilities, debt payments, insurance, birthdays, appointments and any annual bills coming due.
- Assign income before spending it. Fund essentials first, then debt minimums, savings, goals and flexible categories. If income varies, use a conservative estimate.
- Choose one fixed-cost action. Cancel a service, call a provider, compare insurance or change a phone plan. One finished action beats a long list of intentions.
- Choose one variable-cost experiment. Try a cheaper replacement, a no-buy week for one category, or packed lunches every day for a month.
- Direct extra money. Send any surplus, refund or bonus to the current priority, such as the emergency fund or the top debt.
- Talk it over. Share what is working and what feels too tight. A plan the whole household agrees on lasts longer than one imposed on everyone else.
Expect imperfect months. A sick child, a broken appliance or a family obligation can knock the plan off track. Note what happened, use your reserves if that is what they are for, and return to the routine without trying to make up for it through extreme cutbacks. For more everyday ideas to rotate into your routine, browse our frugal living tips.
Ways to Save Money: Frequently Asked Questions
What are the easiest ways to save money right away?
Cancel subscriptions you did not use last month, plan three dinners from what is already in your kitchen, and set up an automatic transfer to savings on payday. All three can be done in one afternoon and cost nothing to start.
How much money can small habits really save?
It depends on your starting point, so track your own numbers rather than chasing a headline figure. Small habits add up because they repeat: trimming a $60 monthly bill frees $720 over a year, and that is before counting groceries, fees or utilities.
Is it better to cut spending or earn more?
Both help you save money, and they work best together. Start by cutting low-value recurring costs because each cut repeats automatically. Once spending is reasonably lean, further cuts tend to hurt, and earning more usually adds more breathing room.
What should I do with the money I save?
Give it a job right away. A common order is a small starter emergency fund, then extra payments on high-interest debt, then sinking funds for predictable bills, then a larger emergency fund and long-term goals. Moving the money automatically keeps it from drifting back into everyday spending.
The Bottom Line
The most effective ways to save money are the ones you set up once and then repeat without thinking: a packed lunch, a canceled subscription, a full washer, a payday transfer. Each one helps you save money in a small way, but together they change how much room you have every month.
Start with visibility rather than perfection. Pick three habits from this list, try them for a month, and keep what works. Then give every dollar you free up a clear job, whether that is an emergency fund, a smaller debt or a goal that matters to you. That is the Frugal Beans approach: not spending the least, but making deliberate choices that turn a limited income into more freedom over time.
How to Save Money at Home: 25 Easy Habits That Really Work
Learning how to save money at home starts with a simple idea: a frugal home is not a home where every purchase is a struggle or every room feels deprived. It is a home designed to use money, time, energy, and possessions with care. Frugality means choosing what matters most and reducing waste around it. That might mean cooking a simple meal instead of ordering takeout, repairing a dripping tap before it damages a cabinet, or waiting a day before buying something that only looked appealing in a shop.
The goal is to make your spending support your life reliably. A household that saves on routine expenses can redirect money toward debt payments, an emergency fund, family activities, a future move, or simply less financial pressure at the end of each month. Small decisions compound because they repeat. Saving $12 on a weekly grocery trip is not just a $12 win; over a year, it can become more than $600.
A practical frugal home begins with observation rather than guilt. Notice where money leaves the household, decide which comforts matter, and build systems that make good choices easier. This guide walks through the habits that work best, room by room, and ends with 25 easy changes you can try this month.
What Frugality Really Means at Home
Frugality is the practice of getting useful value from the money and resources you already have. It is different from being cheap. Being cheap focuses only on the lowest price, even when a low-quality item fails quickly or creates more work. Frugality considers the full cost, including repairs, replacements, time, energy, and stress.
For example, buying a $15 pair of shoes that falls apart in two months may cost more than buying a durable $60 pair that lasts two years. The durable pair is not automatically the right choice, but it deserves comparison. A frugal decision asks, “What will this cost me over its useful life, and will it solve a real problem?”
Frugality also leaves room for generosity and enjoyment. A household can spend freely on a favorite tradition while cutting waste elsewhere. If Saturday breakfast at a local café is important to you, keep it and examine unused subscriptions or poorly planned grocery trips instead. A sustainable budget is one you can follow. For more ways to save money at home with this mindset, see our frugal living tips, or start with frugal living for beginners.
Start with a Home Money Map
The first step in learning how to save money at home is to create a simple map of household spending. Review the last month of bank and card activity and group purchases into broad categories such as housing, utilities, food, transportation, household supplies, health, entertainment, and unexpected costs. The purpose is to see patterns.
Mark each expense as essential, useful, optional, or wasteful. Essential covers rent, basic food, and medication. Useful covers spending that saves time or supports health. Optional covers choices you value but could pause. Wasteful covers forgotten memberships, duplicate purchases, late fees, and discarded food.
Then choose one or two categories for a first adjustment. Trying to change everything at once often creates enthusiasm followed by fatigue. Reducing food waste and canceling two unused subscriptions may accomplish more than an overhaul of every expense.
A home money map might look like this:
|
Area |
Question to ask |
First useful action |
|
Food |
What do we buy and fail to use? |
Plan three flexible dinners before shopping |
|
Utilities |
Which usage is automatic or unnoticed? |
Check heating, cooling, and standby power |
|
Household goods |
Do we own duplicates? |
Make a “use before buying” shelf |
|
Subscriptions |
What did we use last month? |
Cancel or pause anything unused |
|
Repairs |
What is becoming more expensive? |
Schedule one small repair this week |
|
Convenience |
Which purchase happens when we are rushed? |
Prepare a low-effort backup option |
How to Save Money at Home on Food
Food is where most people first learn how to save money at home, because small planning changes affect many meals. Start by checking what you already have. A pantry, freezer, and refrigerator inventory prevents the common cycle of buying ingredients for a new recipe while older food quietly expires. A clear “eat first” bin in the fridge keeps the food that needs attention in plain sight.
Plan meals around ingredients that can appear in more than one dish. A roast chicken might become dinner, sandwiches, and soup. A pot of beans can serve as filling for wraps, a base for chili, or part of a rice bowl. Freeze extra portions in labeled containers rather than hoping everyone will want leftovers on the fourth day.
Keep a short list of reliable, low-effort meals for busy nights. Pasta with vegetables, eggs and toast, bean tacos, rice with frozen vegetables, or soup from leftover ingredients can protect the budget from expensive last-minute orders. Convenience is not a character flaw; it is a predictable need. The frugal solution is to plan affordable convenience before you are exhausted. If you are weighing paid convenience, our look at whether meal delivery services are worth it walks through the real cost.
Shop with a list, but allow substitutions. If the planned vegetable is expensive, choose a similar one on sale. Compare unit prices, which show the cost per standard amount. A larger package is not a bargain if part will be discarded. Saving money never requires eating food that looks or smells unsafe.
Save Money at Home on Utilities
When you save money at home on utilities, the savings usually come from behavior and maintenance. Turn off lights in empty rooms, but remember that heating, cooling, water heating, and large appliances often have a greater effect. Use a schedule when practical, close doors to rooms that do not need the same temperature, and wash full loads.
Hot water deserves special attention. Shorter showers, fixing a dripping faucet, and using cold water for suitable laundry loads can reduce both water and energy use. Air-dry clothing when convenient. Clean appliance filters and vents according to their instructions because blocked airflow can make equipment work harder.
Do not spend $200 on a gadget to save $20 without checking the numbers. A low-cost draft stopper may be worthwhile, while a costly upgrade may take years to repay. For rented homes, ask the landlord before changing wiring, plumbing, windows, or heating equipment. ENERGY STAR keeps a practical list of energy savings at home, and its heating and cooling guide covers thermostats, filters, and when equipment is worth replacing.
Save Money at Home by Maintaining What You Own
Many household purchases are responses to inconvenience. A drawer is messy, so a person buys an organizer. A shirt is missing a button, so a person buys another shirt. A meal feels difficult, so a person buys specialized equipment. Before buying, pause and ask whether the problem can be solved with something already in the home.
Create a waiting rule for nonessential purchases. A 24-hour pause may be enough for a small item, while a 30-day list suits expensive purchases. During the pause, write down the problem, storage location, and expected use. If you cannot answer, the purchase may be responding to advertising rather than need.
Maintenance is one of the quietest ways to save money at home. Clean dryer lint, replace worn seals, and follow appliance care instructions. Keep basic screwdrivers, tape, spare batteries, thread, and a measuring tape. Learn which repairs are safe to do yourself and which require a qualified professional. A frugal home does not treat safety as an experiment.
The biggest maintenance bills come from the systems that run the house: the furnace, air conditioner, water heater, and major appliances. Knowing their age and warning signs lets you plan a replacement instead of paying emergency rates. Our free home system lifespan tracker shows which one is likely to need replacing first and how much to set aside each month. Our free Homeowner Repair Cost Playbook lists typical lifespans and repair costs for each one.
When a technician quotes a big repair, run the numbers through our free repair or replace calculator before you agree. Knowing whether to fix or replace a major system is one of the quickest ways to save money at home.
Borrowing and sharing can also reduce ownership costs. A library, tool-lending program, neighborhood group, or collection of resources among friends can provide occasional-use items without requiring every household to store and maintain them. Agree in advance about return dates and responsibility for damage so that saving money does not create conflict.
Ways to Save Money at Home, Room by Room
For a frugal home, walking through the house one room at a time is one of the simplest ways to save money at home, because each room has its own habits and its own leaks. Use the infographic as a checklist, then read the notes below for the reasoning behind each habit.
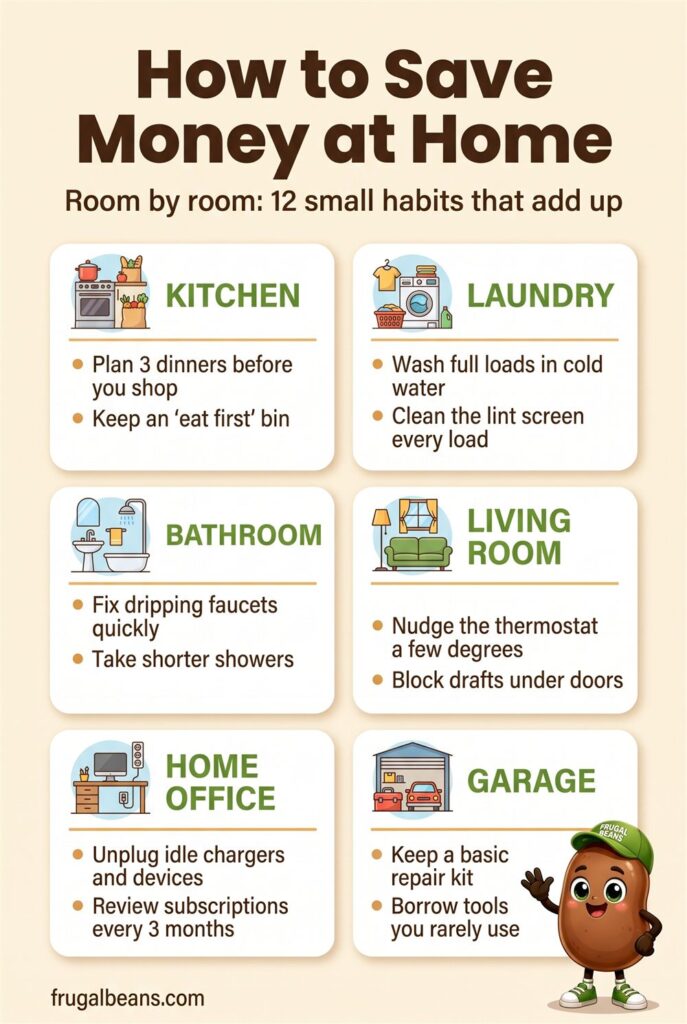
Kitchen
Plan three dinners before you shop and build the list from what is already in the cupboards. Keep an “eat first” bin so leftovers and soft produce get used before they spoil. Food you throw away is money you already spent.
Laundry
Wash full loads and use cold water for everyday clothes when the care label allows it. Clean the dryer lint screen after every load; it keeps air moving, shortens drying time, and reduces a common fire risk.
Bathroom
Fix dripping faucets and running toilets quickly, since a small leak runs all day, every day. Shorter showers cut both the water bill and the energy used to heat that water.
Living Room
Nudge the thermostat a few degrees toward the outdoor temperature and dress for the season. Block drafts under exterior doors with a simple draft stopper or a rolled towel before considering larger upgrades.
Home Office
Unplug idle chargers and switch off devices at a power strip when you finish for the day. Set a reminder to review subscriptions every three months and cancel anything you did not use.
Garage and Storage
Keep a basic repair kit so small fixes do not turn into service calls. Borrow tools you rarely use instead of buying them, and store what you own where you can find it, so you never buy a duplicate.
Make a Frugal Home Budget That Is Easy to Use
A budget is a plan for money, not a punishment for spending. Begin with reliable income, then list fixed costs, flexible costs, savings, and debt payments. Include irregular expenses such as insurance, school costs, gifts, maintenance, and travel. Divide an annual cost by twelve and set aside that monthly amount when possible.
Give every category a realistic amount. If groceries usually cost $500, writing down $250 will not make the difference disappear; it will only make the budget look unsuccessful. Use recent spending as a starting point, then reduce one area gradually. A budget helps you decide before the money is gone, and it turns small habits into a steady plan to save money at home. Our 11 budgeting tips cover how to set those amounts.
Try a weekly household check-in that lasts fifteen minutes. Review upcoming bills, meals, appointments, and any planned purchases. Confirm what is in the checking account and what must remain available. Keep the discussion neutral. The question is not “Who spent too much?” but “What does the household need to prepare for next?”
25 Easy Habits to Save Money at Home
These are the most practical ways to save money at home. Use them as experiments rather than rules. Pick three, try them for a month, and keep the ones that stick.
- Keep a visible “eat first” box in the refrigerator for food that needs attention soon.
- Plan three flexible dinners before every grocery trip.
- Make one weekly grocery trip and use a short top-up list for genuinely missing essentials.
- Compare unit prices instead of package prices.
- Prepare one inexpensive meal component, such as cooked rice, washed vegetables, or boiled eggs, for the next few days.
- Freeze extra portions in labeled containers.
- Keep two default low-cost dinners for nights when you are too tired to cook.
- Wash full loads and use cold water when the care label allows.
- Clean the dryer lint screen after every load.
- Air-dry clothing when it is convenient.
- Fix dripping faucets and running toilets quickly.
- Take shorter showers.
- Nudge the thermostat a few degrees and dress for the season.
- Block drafts under exterior doors.
- Turn off lights and unplug idle chargers in empty rooms.
- Clean or replace HVAC and appliance filters on schedule.
- Store cleaning products together and check existing supplies before buying replacements.
- Use a 24-hour pause for small nonessential purchases and a 30-day list for big ones.
- Set a calendar reminder to review subscriptions every three months.
- Turn off automatic renewal when starting a trial, then decide deliberately whether to continue.
- Keep a basic repair kit and learn the safe, simple fixes.
- Borrow tools you rarely use instead of buying them.
- Place a donation box in a closet and remove items when it is full instead of letting clutter spread.
- Use cloths, towels, and washable containers when practical, without buying a whole new set of products to pursue zero waste.
- Keep a small emergency fund for home repairs so a broken appliance does not automatically become high-interest debt.
The best habits remove decisions. A labeled freezer, a default low-cost dinner, and an automatic transfer to savings reduce willpower. If a system fails, adjust it rather than blaming its users.
How to Save Money at Home When You Rent or Share
Renters and roommates can still create a frugal home without replacing windows or installing major equipment. Focus on reversible actions: efficient lighting, draft control that does not damage surfaces, sensible thermostat settings, careful water use, and organized shared supplies. Ask about utility billing rules before changing habits that affect other residents.
In a shared home, agree on systems. Decide how groceries, shared replacements, and repairs will be handled. A shared list can prevent three people from buying dish soap in one week. If one roommate uses most of an item, a contribution rule may be fairer than an equal split.
Do not sacrifice privacy, safety, or basic comfort to meet an arbitrary target. A cheaper home may not be cheaper if it creates a long commute, poor sleep, or frequent emergency expenses. Consider total housing cost, not just advertised rent.
Use Savings for Security First
Once you start to save money at home and frugal changes create room in the budget, give the savings a job. A small starter emergency fund can cover a minor repair or urgent trip without relying on a credit card. After that, work toward several weeks or months of essential expenses, depending on your income stability and responsibilities. High-interest debt may deserve priority because interest can grow faster than ordinary savings.
Keep savings separate from spending money but accessible for real emergencies. Track progress clearly. Paying off a $300 balance or setting aside the first $500 is meaningful even if the long-term goal is much larger.
Avoid turning every saving into permission for immediate consumption. Some rewards are healthy, but decide in advance how much of a windfall or monthly surplus will go to security, goals, and enjoyment. This balance helps frugality feel like progress rather than permanent restriction.
How to Save Money at Home: Frequently Asked Questions
What is the fastest way to save money at home?
The fastest way to save money at home is to start with food waste and unused subscriptions. Both can be fixed in an afternoon: take a fridge and pantry inventory, plan three dinners from what you have, and cancel anything you did not use last month. These changes need no equipment and no upfront cost.
How much can a household save with frugal habits?
It depends on your starting point, so track your own numbers rather than chasing a headline figure. Small repeat savings add up: trimming $12 from a weekly grocery trip is more than $600 over a year, before counting any utility or subscription changes.
Is it worth buying energy-saving gadgets to save money at home?
Only when the numbers work. Habits such as shorter showers, full laundry loads, and thermostat adjustments cost nothing. Before buying a device, compare its price with a realistic monthly saving and check how many years it would take to pay for itself.
How can renters save money at home?
Focus on reversible changes: draft stoppers, careful thermostat use, efficient bulbs you can take with you, shorter showers, and shared-supply systems with roommates. Ask the landlord before changing anything permanent.
The Bottom Line
A frugal home is built through ordinary choices that protect what the household values. It starts with seeing the flow of money clearly, then reducing waste in food, utilities, purchases, and convenience spending. It uses maintenance, planning, and shared systems to make savings repeatable. It also recognizes that the cheapest option is not always the best option when quality, safety, time, and stress are included.
Choose one small change today: inspect the pantry, cancel an unused subscription, plan a low-effort dinner, or schedule a repair. Keep what works and revise what does not. If you want to know how to save money at home without feeling deprived, this is the answer: start small and keep going. Over time, these decisions can turn a home into a steadier financial base—one that supports comfort, resilience, and the life you actually want to live.
Frugal Living Tips: 21 Simple Ways to Live Well on Less
The best frugal living tips are not about making life small; they are about making your money useful on purpose. Ms Frugal Quaker, the plain-spoken voice behind the original version of this post, would put it simply: before you spend, ask whether the purchase supports the life you are trying to build. That one question can help a household spend less without turning every grocery trip or family outing into a test of willpower.
Frugal living means using what you have carefully, choosing value over appearance, and leaving room for the future. It is not a contest to see who can spend the least. It is a set of habits that keeps money flowing toward what your household actually values and away from waste, impulse, and forgotten charges.
This guide collects the habits that work best in real households. You will find the mindset behind them, a simple spending map, practical ideas for food, clothing, repairs, and borrowing, a numbered list of 21 tips you can try this month, and a short plan for the months when money is tighter than usual.
What Frugal Living Really Means
Frugality is different from being cheap. Being cheap focuses only on the lowest price, even when a poor-quality item costs more over time. Frugal living considers the total cost of a choice: the price, how long it lasts, what it costs to maintain, and the effect it has on your household’s peace of mind.
A $20 pair of work boots that splits in three months is not a bargain if a sturdier pair would have lasted for years. The sturdier pair is not automatically the right answer either, but it deserves a fair comparison. The frugal question is, “What will this cost me over its useful life, and does it solve a real problem?”
Enough Before More
The heart of a frugal lifestyle is learning to define “enough.” Enough does not mean refusing every improvement. It means recognizing when something already meets your needs.
A phone that makes calls, runs the apps you need, and holds a charge may be enough even if a newer model has a better camera. A packed lunch may be enough even if coworkers order delivery. A clean, well-fitting jacket may be enough for another winter after a small repair. When you notice “enough,” the pressure to upgrade loses much of its pull.
Frugal, Not Deprived
People who live frugally for years usually keep a few things they love. If Saturday breakfast out is a family tradition, keep it, and trim the subscriptions nobody opens instead. A plan you can follow beats a perfect plan you abandon in two weeks. If you are just getting started, our guide to frugal living for beginners walks through the first steps in more detail.
Start With a Clear Reason to Live Frugally
It is much easier to live frugally when you know what the savings are for. A budget is easier to follow when it serves a purpose. “Spend less” is vague and discouraging. “Save $600 for car repairs by December” gives every small choice a connection to a real need.
Write down three priorities for the next six to twelve months. One might be an emergency fund, which is money set aside for an unexpected cost such as a broken appliance or a short stretch without work. Another might be paying down a credit card. A third could be something positive, such as a family visit or replacing an unreliable laptop.
Next, list your monthly take-home income and your essential expenses: housing, utilities, basic food, transportation, insurance, minimum debt payments, and necessary medical costs. Then list flexible spending, such as restaurants, subscriptions, clothing, hobbies, and convenience purchases. Do not criticize the list. Accuracy is more useful than shame.
A short weekly check-in keeps the plan realistic. Look at what was spent, compare it with the plan, and adjust the next week. If the household spent too much on takeout because everyone was exhausted, the fix may be two easy freezer meals, not a lecture about discipline.
Build a Household Spending Map for Frugal Living
Many budgets fail because their categories do not match real life. A household might have a “food” category but no way to see the difference between groceries, coffee runs, school lunches, and delivery fees. A spending map should be detailed enough to reveal patterns but simple enough to keep up.
Here is an illustrative monthly map for a household with $4,000 in take-home income. The amounts are examples, not rules.
|
Spending group |
Example amount |
Frugal focus |
|
Housing and basic utilities |
$1,450 |
Review renewals and reduce avoidable energy use |
|
Transportation and insurance |
$600 |
Combine errands and maintain the vehicle |
|
Groceries and household supplies |
$600 |
Plan meals around what is already on hand |
|
Debt payments |
$400 |
Pay minimums first, then target one balance |
|
Savings and future needs |
$450 |
Automate a manageable amount each payday |
|
Health, school, and necessary care |
$250 |
Plan for recurring costs before they arrive |
|
Personal spending and fun |
$250 |
Spend freely within a visible limit |
|
Total |
$4,000 |
Adjust categories to fit your priorities |
The point of a table like this is not to make every month identical. It is to reveal tradeoffs. If there is no cushion for irregular costs, an unexpected $300 repair has to come out of another category or go on a credit card. Seeing that risk in writing is often the motivation a household needs to make a gradual change. For more ideas on trimming each line, see our list of practical ways to save money.
Frugal Living Tips for Food Without the Misery
Food is one of the easiest places to put frugal living tips to work because small routines repeat many times a month. The goal is not to eat the cheapest possible meals. The goal is to waste less and make convenient, satisfying food easy to reach at home.
Keep a Use-First Shelf
Choose one shelf in the refrigerator for leftovers, opened produce, and items close to their date. Plan one flexible meal each week that can absorb them, such as fried rice, soup, pasta, grain bowls, or omelets. This turns random odds and ends into dinner instead of trash.
Cook With Overlapping Ingredients
Pick a few dependable meals that share ingredients. A roast chicken can become dinner, sandwiches, and soup. A pot of beans can fill tacos, top a salad, or start a simple stew. Frozen vegetables make it easier to cook when fresh produce has run out.
Store brands are often a sensible choice, but compare the unit price rather than the package price. The unit price shows the cost per ounce, pound, or item, which makes different package sizes easier to compare. A bigger package is not a bargain if half of it ends up in the bin.
Plan for Tired Nights
Keep a short list of backup meals: oatmeal with fruit, eggs and toast, canned soup with a sandwich, or pasta with frozen vegetables. They may not be exciting, but they can prevent a costly delivery order. Frugal living works best when it prepares for tired days instead of pretending they will not happen. If you are weighing paid convenience, our look at whether meal delivery services are worth it breaks down the real cost.
Frugal Living Tips for Clothes, Laundry and Repairs
Clothing and household goods rarely blow up a budget in one purchase, which is why these frugal living tips focus on small, repeat savings. They leak money through small replacements, and that is exactly where steady frugal habits pay off. Before buying, check what you already own. Many households discover they have three of something they thought they needed.
Wash Smarter, Dry for Free
Wash full loads, use cold water for everyday clothes when the care label allows, and air-dry when the weather and your schedule cooperate. A clothesline or a folding drying rack costs little and can take some of the load off the dryer. Clothes that are not tumbled every week also tend to keep their shape and color longer, which means fewer replacements.
Mend Before You Replace
The same thinking applies to the big systems in your home. When a furnace, air conditioner or appliance breaks, our free repair or replace calculator shows whether fixing it is the frugal choice for a unit that age, one of the most practical frugal living tips for homeowners. To see which system is likely to need replacing next, and what to save for it, try our free home system lifespan tracker.
A missing button, a loose hem, or a small seam tear is often a ten-minute fix with a needle and thread. Keep a small sewing kit with a few colors of thread, spare buttons, safety pins, and small scissors. If sewing is not your thing, a local tailor or a handy friend may still cost less than a new garment.
The same thinking applies around the house. Tighten the loose cabinet hinge, replace the worn washer in a dripping faucet, and clean the dryer lint screen after every load. Small maintenance keeps small problems from becoming expensive ones. For larger systems such as the furnace, water heater, and major appliances, our free Homeowner Repair Cost Playbook lists typical lifespans and warning signs so you can plan instead of paying emergency rates.
Know When to Call a Pro
Frugality never means treating safety as an experiment. Electrical work, gas appliances, and anything structural belong with a qualified professional. Get more than one estimate, and ask whether a safe temporary fix exists while you save for the full job.
Borrow Before You Buy: A Frugal Living Tip That Adds Up
Borrowing is one of the most overlooked frugal living tips. Ms Frugal Quaker liked to talk about building a collection of “many resources”: the places and people that help a household solve problems before spending money. That collection might include a public library, a community swap group, a tool-lending program, a free local events calendar, a food pantry, workplace benefits, or a trusted neighbor.
A library can offer books, movies, classes, internet access, and in some areas, museum passes or even tools. A community group may help someone find a used crib, spare moving boxes, or a recommendation for an honest repair person. A pantry can support a tight month so a household does not have to choose between food and another bill. Using available help is not a personal failure. These resources exist to make communities stronger and household money less fragile.
Make a note on your phone or a page in a household folder. Add each resource’s name, what it offers, opening hours, any eligibility rules, and the date you last checked. Include informal resources too, like a neighbor who lends a ladder or a friend who trades babysitting. The list is most valuable when it is ready before you need it.
21 Frugal Living Tips to Try This Month
These 21 frugal living tips are grouped into six themes: plan, cook, repair, borrow, wait, and save. Do not try them all at once. Pick two or three, use them for a month, and keep the ones that fit your household.
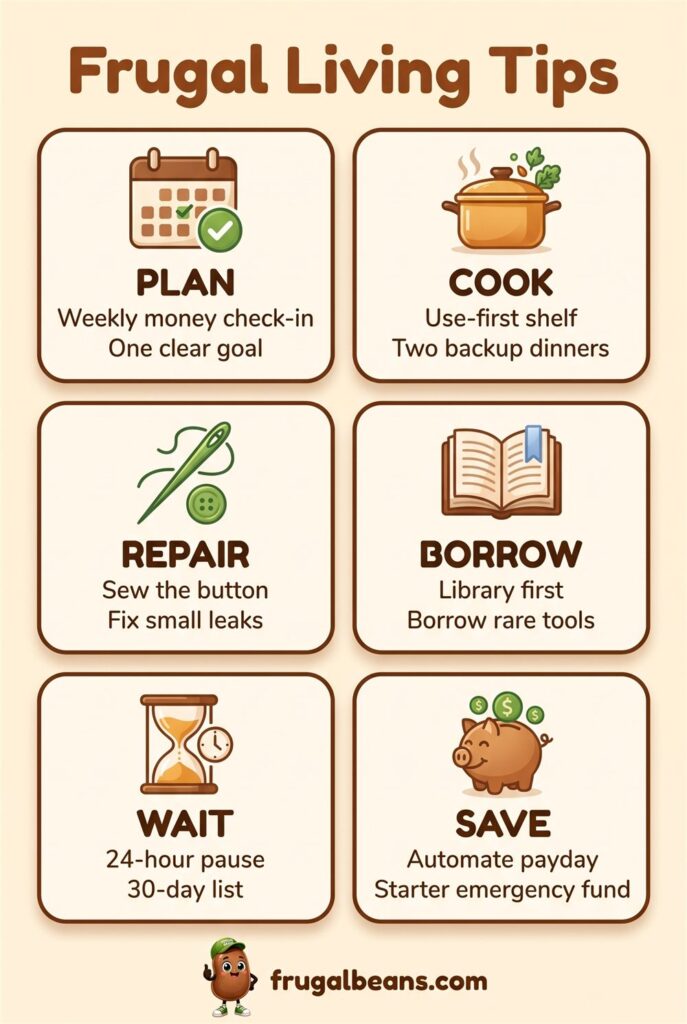
- Hold a weekly money check-in. Spend fifteen minutes reviewing upcoming bills, meals, and planned purchases.
- Name one clear savings goal. Give it a dollar amount and a date so small choices have a purpose.
- Review the last 30 days of transactions. Circle the three purchases that surprised you most.
- Combine errands into one trip. Fewer trips mean less fuel, less time, and fewer impulse stops.
- Keep a use-first shelf in the fridge. Put leftovers and soft produce where everyone sees them.
- Plan dinners from what you already have. Check the pantry and freezer before writing a grocery list.
- Keep two backup dinners on hand. Simple meals for tired nights protect the budget from takeout.
- Pack a drink and snack before you leave home. Small convenience purchases add up quickly.
- Sew the button and fix the hem. A basic sewing kit extends the life of clothes you already like.
- Fix small leaks quickly. Dripping faucets and running toilets waste water every hour they run.
- Wash full loads in cold water and air-dry when you can. Follow care labels and let the sun do some of the work.
- Check the library first. Books, movies, classes, and sometimes passes or tools are free to borrow.
- Borrow rare-use tools instead of buying them. Ask a neighbor, a tool library, or a community group.
- Use swap groups for kids’ gear and seasonal items. Children outgrow things long before they wear out.
- Use a 24-hour pause for small extras. If you still want it tomorrow, it may be a planned choice.
- Keep a 30-day list for big purchases. Write down the problem it solves and compare alternatives.
- Review subscriptions every three months. Cancel anything you did not use and note annual renewal dates.
- Automate a small transfer on payday. Even $10 a paycheck builds the habit before the amount grows.
- Build a starter emergency fund. A few hundred dollars can keep a minor surprise off a credit card.
- Call one provider about a lower rate. Ask about a cheaper plan, a fee waiver, or a better renewal price.
- Give every adult a no-questions allowance. A small, guilt-free amount keeps the whole plan sustainable.
These actions are deliberately modest. A habit that survives a busy week is worth more than an ambitious plan that lasts three days.
Frugal Living Tips That Survive a Bad Month
Every household has months when the paycheck is short, a medical bill arrives, or the car needs work at the worst possible time. The frugal living tips that matter most are the ones that still function when you are stressed and tired.
Protect the Essentials First
List the bills that keep the household safe and running: housing, utilities, food, transportation to work, insurance, and necessary medicine. Pay those first. If something has to slip, call the company before the due date and ask about a payment plan or a later date. Many will work with you if you ask early.
Switch to a Bare-Bones Budget for a While
Pause the flexible categories, not forever, just for this stretch. Eat from the pantry and freezer, skip nonessential shopping trips, and lean on the resource list you built earlier. A library card, a pantry, and a neighbor with a ladder are exactly what a bad month calls for. Our guide to saving money on a tight budget has more ideas for these weeks.
Use Savings Without Guilt
If you built an emergency fund, this is what it is for. Using it is not failure; it is the plan working. Once the month passes, restart the automatic transfer, even at a smaller amount, and rebuild gradually.
Keep One Small Comfort
Cutting everything at once often leads to a rebound spending spree. Keep one inexpensive comfort, such as a favorite coffee at home or a free outing with family, so the tight stretch feels survivable rather than punishing.
Use a Frugal Lifestyle to Pay Down Debt and Grow Savings
When money is tight, saving and paying debt at the same time can feel impossible. A balanced plan usually protects a small starter emergency fund while making every required debt payment. After that, direct extra money toward one priority at a time.
A starter fund of even a few hundred dollars can stop a minor emergency from becoming new credit card debt. The Consumer Financial Protection Bureau’s guide to building an emergency fund explains how to set a goal and make saving automatic.
Once that buffer exists, choose a debt strategy. The debt avalanche sends extra money to the balance with the highest interest rate, which can reduce the total interest you pay. The debt snowball sends extra money to the smallest balance first, which can create faster emotional wins. Either method works if payments are made consistently.
When a frugal lifestyle change frees up money, give it a job right away. If you cancel a subscription, move the same amount to savings or a debt payment that day. Money without a job tends to drift back into everyday spending.
Keep Your Frugal Lifestyle Kind and Sustainable
The people who live frugally for the long haul tend to share one trait: they leave room for joy. A household budget should include some enjoyment. If every purchase is treated as evidence of failure, people tend to abandon the plan and spend reactively. Set a reasonable personal allowance for each adult and, when it fits, a small amount for children. Money inside that boundary can be spent without debate.
Do not use frugality as a reason to ignore health, safety, or dignity. Skipping needed medicine, driving on worn tires, or refusing necessary professional help is not a bargain. The lowest price today can create a much bigger cost later. A sustainable plan protects essentials first and looks for savings around them.
Households also move through seasons. A new baby, a job change, or caring for a parent may require spending in new ways for a while. That is not failure. The purpose of a financial plan is to help you respond calmly, not to produce a perfect record. Many of the habits in this guide also work room by room; our guide on how to save money at home covers the kitchen, laundry room, and more.
Frugal Living Tips: Frequently Asked Questions
What are the easiest frugal living tips to start with?
Start with food waste and unused subscriptions. Both can be handled in an afternoon: check the fridge and pantry, plan a few dinners from what you have, and cancel anything you did not use last month. Neither change requires any upfront cost.
How do I live frugally without feeling deprived?
Keep a few things you truly value and cut waste around them. Give each adult a small allowance that can be spent without explanation, and focus first on spending that brings little joy, such as late fees, forgotten subscriptions, and food that spoils.
Is frugal living the same as being cheap?
No. Being cheap looks only at the lowest price. Frugal living looks at the total cost, including how long something lasts, what it takes to maintain, and whether it solves a real problem. Sometimes the frugal choice costs more up front.
How much money can frugal living save?
It depends on where you start, so track your own numbers rather than chasing a headline figure. Small repeat savings add up: cutting $10 a week from takeout is $520 over a year, before counting any subscription or utility changes.
The Bottom Line
A frugal lifestyle is thoughtful use, not constant deprivation. Start with a reason for saving, map the money you already spend, and change a few defaults that create repeat costs. Plan food for tired days, mend and maintain what you own, borrow before you buy, and give your savings a clear job.
Pick two or three of these frugal living tips today and try them for a month. Keep what works and adjust what does not. Over time, a pause before buying, a dinner made from what is on hand, and a small automatic transfer add up to breathing room: more control, fewer emergencies, and a clearer path toward the life your household values.
Are Meal Delivery Services Worth It? 7 Smart Ways to Decide
Are meal delivery services worth it for your household, or are they just an expensive way to answer the question “what’s for dinner?” A box arrives with measured ingredients and a recipe card, or a tray arrives ready to heat. The convenience can be real, especially for a busy family, a new parent, or someone who wants to cook more often without planning every meal. The price can also be much higher than it first appears.
Whether meal delivery services pay off depends less on the advertised price per serving and more on how they fit your actual habits. You need to count delivery fees, skipped boxes, unused ingredients, grocery spending, takeout, food waste, and the value of your own time. A service can be a sensible purchase if it replaces expensive last-minute meals and food that would otherwise spoil. It can be a poor deal if it adds another food expense without replacing anything.
This guide gives you a simple way to decide using your own numbers. You will work out a real cost per serving, compare meal kits with prepared meals, groceries, and takeout, spot the hidden charges, and then run through seven smart questions that tell you whether a subscription has earned a place in your budget.
What You Are Paying For with Meal Delivery Services
Meal delivery services fall into two broad categories, and the money trade-offs are different for each. Some companies offer both types, so it helps to know which one you are actually comparing.
Meal Kits
Meal kits send measured ingredients and step-by-step instructions that you cook at home. The bill usually covers the ingredients, recipe development, portioning, packing, insulated shipping, and delivery. You are also paying for the planning work that a grocery trip normally requires: someone else picked the recipes, wrote the shopping list, and bought exactly the amounts you need.
Prepared Meals
Prepared-meal services send food that is fully cooked or mostly cooked, so you only need to heat and serve it. Here you are paying for cooking labor, packaging, refrigeration, and the convenience of skipping the stove entirely. Prepared meals usually save more time than meal kits, but the portions and variety may feel more limited.
The Two Options You Are Really Competing With
Every delivered meal is competing with two familiar alternatives: groceries you cook yourself, and takeout or restaurant delivery. Cooking from groceries is usually the cheapest per serving but takes the most planning and time. Takeout is fast and requires no cleanup but is usually the most expensive. Meal kits and prepared meals sit somewhere in between, and that middle position is exactly why the answer is different for every household.
In every case, the listed price rarely tells the whole story. A weekly order might advertise eight servings at $10 each, or $80. After a delivery fee, the total might be $95. If one meal is too spicy, another is not filling enough, and two servings end up in the freezer, your effective cost is far higher than $10 per serving. The useful number is the cost of food you actually eat, not the number printed in the promotion.
The Real Meal Kit Cost: Hidden Charges to Count
Before deciding, calculate the full meal kit cost of a typical order. Include every recurring charge and the costs that the order itself creates. A meal kit may require cooking oil, salt, spices, butter, or other pantry items. A prepared meal may require side dishes, drinks, or extra portions for a bigger appetite. Use this table as a checklist when you look at your first few orders.
|
Expense to check |
Why it matters |
Question to ask |
|
Menu price |
The advertised price is usually only the starting point. |
What is the price before and after discounts? |
|
Delivery fee |
A weekly charge can materially change the cost of small orders. |
Can I combine orders or qualify for free delivery? |
|
Taxes and surcharges |
These may appear at checkout rather than on the menu page. |
What is the final charge on my statement? |
|
Pantry add-ons |
Missing oil, spices, or staples create extra grocery trips. |
Do I already have the required basics? |
|
Unused servings |
Food that is never eaten is part of the cost. |
How many portions will realistically be eaten? |
|
Replacement meals |
A kit may not replace takeout if it is inconvenient. |
Will this prevent another food purchase? |
|
Subscription waste |
Forgotten skips can create unwanted boxes. |
How easy is it to pause or cancel? |
Shipping and Delivery Fees
Many services charge a flat delivery fee per box. On a large order, that fee is spread across many servings and barely moves the math. On a small order, it can add a noticeable amount to each plate. Always divide the fee into your per-serving number rather than treating it as a separate, forgettable line.
Skipped Boxes and Missed Deadlines
Most subscriptions ship automatically unless you skip a week before a cutoff date. If you travel, work irregular shifts, or simply forget, a box can arrive that nobody has time to cook. That box still counts toward your real meal kit cost, even if half of it goes in the trash.
Auto-Renew and Introductory Discounts
Welcome offers can make the first box look like a bargain, while later boxes cost the full price. Decide whether the regular price works before the discount runs out, and set a reminder for the date the subscription renews. If you want to stop a recurring charge, the Consumer Financial Protection Bureau explains how to stop automatic payments from your bank account, including telling the company in writing and keeping records of the date you asked. Remember that stopping a payment is not the same as canceling the service, so cancel the subscription itself, too.
Portions and Pantry Add-Ons
Check serving sizes against the people you are feeding. A box marketed for a family may provide smaller portions than active teenagers or hungry adults expect. If you routinely add bread, rice, salad, or a second main dish, add those costs to the order before you calculate anything.
Are Meal Delivery Services Worth It Compared with Groceries and Takeout?
The fairest way to compare options is one number: effective cost per serving. Use this simple calculation for every option you are considering:
Total cost ÷ servings actually eaten = effective cost per serving.
Here is a worked example using made-up numbers. Suppose a two-person household orders three meal kits with two servings each. The food costs $66, delivery costs $10, and the household spends $4 on missing pantry ingredients. The order total is $80 for six planned servings, or about $13.33 per serving. If one serving is thrown away and one portion is too small to count as a full meal, the order provides only four satisfying meals. The effective cost is then $20 per satisfying meal.
A Four-Way Example (Illustrative Numbers Only)
To see how the comparison works, here is the same week of six dinner servings priced four ways. These figures are examples to show the arithmetic, not real prices from any company or store. Replace them with what you actually pay.
|
Option |
Example weekly cost |
Servings eaten |
Cost per serving |
|
Meal kit |
$80 (food, delivery, pantry add-ons) |
6 |
About $13.33 |
|
Prepared meals |
$75 (six trays at $11 plus $9 delivery) |
6 |
$12.50 |
|
Groceries |
$30 in ingredients |
6 |
$5.00 |
|
Takeout |
$90 (two orders for two at $45 each) |
4 |
$22.50 |
In this example, groceries win easily on price, and takeout loses badly. The meal kit and prepared meals land in the middle. That is the key insight: whether meal delivery services save money depends almost entirely on which column they are replacing. If the kit replaces the grocery column, it costs more. If it replaces the takeout column, it may cost less.
Be Honest About Your Real Alternative
Do not compare a meal kit only with the cheapest possible grocery basket. Compare it with what you actually buy when you are tired, rushed, or out of ingredients. For a grocery benchmark, the USDA publishes USDA Food Plans, which estimate the cost of a healthy diet at four levels, from the Thrifty plan up through the Low-Cost, Moderate-Cost, and Liberal plans, along with monthly cost-of-food reports. They can give you a rough sense of where your own grocery spending sits.
Time matters, too. Consider a household that spends $25 on groceries for a home-cooked dinner for four, or $6.25 per serving. If preparing it takes 90 minutes, the household may still prefer a $55 kit, or $13.75 per serving, on a stressful evening. That preference puts a value on time, which is fine, but it still needs a spending limit.
Meal Kit or Groceries? A 6-Step Cost Check
If you want a quick routine instead of a spreadsheet, use these six steps after your first two or three deliveries. The infographic below follows the same steps, so you can save it and keep it handy.
- Add up the full order. Use the final charge on your statement, plus delivery, tax, and any pantry items you had to buy.
- Count the servings you actually eat. Leave out anything thrown away, frozen and forgotten, or too small to count as a meal.
- Divide the total by those servings. That is your effective cost per serving.
- Price the grocery version. After cooking a favorite recipe, write down what the same ingredients would cost at your usual store.
- Name what it replaces. Write down the specific takeout order, restaurant lunch, or wasted grocery run the box is supposed to prevent.
- Try one month, then decide. Track every food charge for four weeks, compare the totals, and keep, shrink, or cancel the plan.
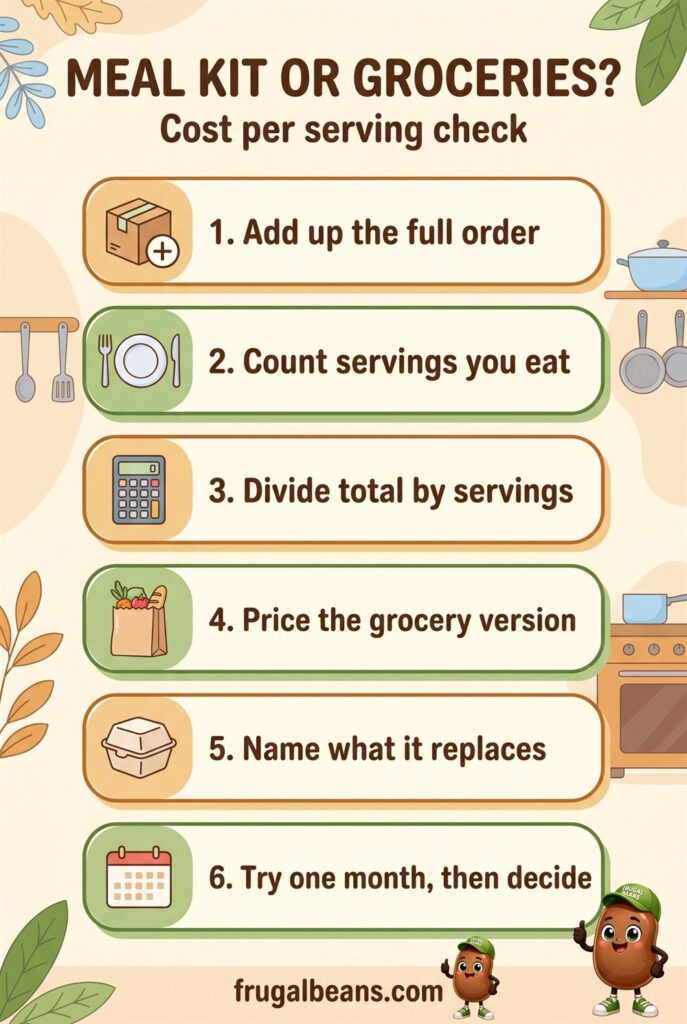
The one-month check is where the truth shows up. Record meal kit charges, grocery purchases, restaurant orders, convenience foods, and food thrown away. A service that replaces four takeout meals and reduces grocery waste may earn its cost. A service that replaces one planned grocery dinner while adding another charge probably does not.
Are Meal Delivery Services Worth It? 7 Smart Questions to Decide
Once you know your cost per serving, these seven questions turn the numbers into a decision. Answer them honestly, ideally with whoever else eats at your table.
1. Which Existing Spending Will It Replace?
This is the most important question. If your grocery bill stays the same and you keep ordering takeout, meal delivery becomes a new expense rather than a replacement. Name the specific spending it will cut, such as Friday takeout or the lunch you buy near work.
2. Will Your Household Eat Most of What Arrives?
Picky eaters, small appetites, and unexpected dinner invitations all reduce the servings you actually eat. Every uneaten serving raises the cost of the ones you do eat.
3. Does the Price Still Fit After the Discount Ends?
Judge the service on its regular price, not the welcome offer. If the full price only works by squeezing groceries or savings, it does not really fit.
4. Is Your Schedule Predictable Enough?
Weekly boxes work best for steady routines. Frequent travel, rotating shifts, or a busy social calendar make it more likely that food sits in the refrigerator until it spoils.
5. Do the Portions Match Your Appetites?
If one adult routinely eats one and a half servings, budget for that reality instead of trusting the label. Extra sides and second dinners quietly erase the advertised price.
6. Can You Skip, Pause, and Cancel Easily?
Read the skip deadlines and cancellation steps before you sign up. A subscription that is hard to control can turn convenience into recurring waste.
7. Is the Time You Save Worth the Premium?
You may decide that saving 30 minutes on a hard evening is worth $12 extra per serving. That can be a valid choice if it is planned and affordable. The problem is not paying for convenience; it is paying for it by accident, repeatedly, or with money you need for higher priorities.
A simple rule of thumb: if you can answer yes to most of these questions, try the service for one month and track it. If you answer no to two or more of the first three, the service is probably a lifestyle luxury rather than a useful part of your food budget.
When Are Meal Delivery Services Worth It? Who They Suit Best
Meal delivery services are most worthwhile when it solves a specific, expensive problem. These are the situations where the numbers most often work.
Busy Households That Rely on Takeout
Suppose a couple spends $45 on takeout twice a week because nobody wants to plan dinner after work. That is $90 a week. A three-meal kit costing $75 may be cheaper if it reliably replaces those orders and all six servings are eaten. The kit is not cheaper than cooking from the least expensive ingredients, but it may be cheaper than the household’s real alternative.
People Who Overbuy Groceries
Meal kits may help households that regularly buy produce with good intentions and then throw it away. Buying ingredients for one or two planned recipes reduces the temptation to purchase a large bundle that spoils. The savings are not automatic, because packaging can be substantial and per-serving prices are usually higher than bulk grocery prices. Still, measured portions may cut waste for people who struggle to use full-size packages.
One-Person Households
Buying a wide range of ingredients for one person often means repeated leftovers or spoiled food. A prepared meal can be a reasonable middle ground when the alternative is a restaurant lunch or a skipped meal followed by convenience-store snacking.
Short, Demanding Seasons
A new baby, recovery from surgery, a move, or a stretch of long workdays can make cooking feel impossible. A short, deliberate run of meal kits or prepared meals during that season can be cheaper and calmer than a month of takeout. Set an end date when you start.
New Cooks Building Confidence
Meal kits can work like a paid cooking class. If a few weeks of kits teach you a handful of dinners you can then shop for yourself, the service may pay for itself in the skills you keep.
When Meal Delivery Services Are Probably Not Worth It
Meal delivery is less attractive when you already plan and cook efficiently. A household that buys affordable staples, uses leftovers, and enjoys cooking may pay a large premium for tasks it can do easily. The service may still be enjoyable, but treat it as a convenience purchase rather than a savings strategy.
Meal delivery services are also a poor fit for unpredictable schedules, as the questions above showed. Large households should look carefully at portion sizes, and households with allergies or strict diets may find that the affordable menu choices are limited. And if money is tight right now, a premium dinner subscription is usually one of the first things to pause. Our guide to saving money on a tight budget covers where to focus first.
Cheaper Ways to Get Meal Kit Convenience
Much of what meal kits sell is planning, not food. You can copy that planning at grocery prices with a few simple habits.
Build Your Own Kit
On the weekend, choose three dinners and write a list for just those meals. Bag or box the ingredients for each dinner together in the refrigerator, so weeknight cooking feels like opening a kit. Plan to cook the most perishable dinner first.
Keep Two Default Dinners
Keep the ingredients for two low-effort meals on hand at all times, such as pasta with frozen vegetables, eggs and toast, bean tacos, or rice bowls. These protect the budget on nights when you would otherwise order takeout. Our list of ways to save money at home includes more food habits like this.
Cook Once, Eat Twice
Double a recipe and freeze labeled portions. A freezer full of your own meals works much like a prepared-meal delivery, without the shipping fee. If you are new to this kind of planning, our frugal living for beginners guide is a gentle place to start.
Tips for Getting Better Value from Meal Kits
If you decide to subscribe, these habits make meal kits and prepared meals more useful without turning them into a complicated project:
- Start with the smallest practical order. Try one or two weeks before committing to a large plan, and measure what your household eats, not what the menu promises.
- Set a calendar reminder before the menu deadline. Review the upcoming box, skip weeks you do not need, and check the final charge.
- Give each box a clear job. If Friday takeout is your regular splurge, choose a meal that works on Friday.
- Use every ingredient. Cook the most perishable produce first, and use leftover herbs, sauces, or vegetables in another meal.
- Keep basic pantry supplies on hand. Oil, salt, pepper, rice, and common seasonings prevent emergency grocery runs.
- Treat discounts as a trial, not the permanent price. Decide whether the regular price works before you continue.
- Pause or cancel promptly. Read the service’s rules for skips and cancellations, and keep a note of the date you canceled.
- Set a monthly ceiling. Treat delivery as part of the food budget. For example, you might allow two boxes a month while leaving room for groceries and an occasional restaurant meal.
For more ideas on trimming everyday costs without feeling deprived, browse our frugal living tips.
Are Meal Delivery Services Worth It? Frequently Asked Questions
Is a meal kit cheaper than buying groceries?
Usually not, when you compare it with cooking the same recipe from your own groceries. A meal kit can still save money if it replaces takeout or prevents you from buying groceries you would otherwise throw away. Price the grocery version of one favorite kit recipe to see the gap for yourself.
How do I calculate meal kit cost per serving?
Add up the final charge for the order, including delivery, tax, and any pantry items you had to buy. Then divide by the number of servings your household actually ate. That effective cost per serving is the number to compare with groceries and takeout.
What hidden costs come with meal delivery services?
The common ones are delivery fees, taxes added at checkout, boxes that ship because you missed a skip deadline, the jump from an introductory price to the regular price, pantry add-ons, extra sides for small portions, and servings that go uneaten.
Is meal delivery worth it for one person?
It can be. Cooking for one often leads to spoiled ingredients or repeated leftovers, so prepared meals or a small kit can be reasonable if they replace restaurant lunches or wasted groceries. Run the cost-per-serving check for a month before committing to a long plan.
The Bottom Line
Meal delivery services are worth it for some households, but they are not automatically a money-saving solution. Their value comes from what they replace and how consistently the food gets eaten. A service can cut takeout, limit grocery waste, simplify a demanding week, or provide manageable portions for one person. It can also create forgotten charges, uneaten food, and a bigger monthly food bill.
So, are meal delivery services worth it for you? Calculate the full meal kit cost or delivered price, use realistic serving counts, and compare the result with your actual alternatives. Start small, track one month, and set a clear spending limit. If the service buys meaningful time without undermining your budget, keep it as a deliberate convenience. If it only adds another food expense, cancel it and put the money toward groceries, savings, or a meal plan that works better for your household.
Frugal Living for Beginners: 15 Simple Money Habits to Start
Frugal living for beginners is not a contest to see who can live with the least. It is the practical habit of directing limited money toward what matters most. Done well, it helps an ordinary household keep more of its income, cut avoidable costs, prepare for surprises, and move toward goals that are bigger than this month’s bills.
This guide is for people with paychecks, irregular income, children, caregiving responsibilities, debt, rising bills, or simply a wish to feel less financial pressure. You do not need a finance degree or a perfect spreadsheet. You need a clear view of your choices and a system simple enough to use when life is busy.
Below you will find where to start, a simple plan for your first 30 days, and 15 money habits that cover every major part of household finances. Work on one habit at a time. Each one is a stream of attention pointed at one part of your financial life, and together they form a complete beginner’s system.
What Frugal Living Really Means
Frugal living means getting real value from the money, time, and things you already have. It is different from being cheap. Cheap focuses only on the lowest price, even when a flimsy item breaks quickly or creates more work. Frugality looks at the full cost, including repairs, replacements, interest, time, and stress.
It also leaves room for enjoyment. A frugal household can spend happily on a favorite tradition while cutting waste somewhere else. The point is not to remove every pleasure; it is to stop paying for things you do not use, do not value, or did not really choose.
For a beginner, the most useful shift is this: frugality is a system, not a mood. Willpower runs out at the end of a long day. A bill calendar, an automatic transfer, and a short shopping list keep working when you are tired. That is why this guide focuses on money habits rather than one-time cuts, and why frugal living for beginners works best when you build one habit at a time.
Where to Start with Frugal Living for Beginners
Most people who try frugal living for the first time make the same mistake: they try to change everything in one weekend. They cancel every subscription, start a strict grocery budget, and promise never to order takeout again. By week three, the plan feels like punishment and the old habits return.
A better start has three steps:
- See your money clearly. Look at the last month of bank and card activity. Group spending into broad categories such as housing, food, transportation, bills, debt, and “everything else.” You are looking for patterns, not passing judgment.
- Protect the basics first. Make sure shelter, utilities, food, essential transportation, and minimum debt payments are covered before you set any savings target.
- Pick one or two habits. Choose the areas below that would make the biggest difference right now. Small, repeated wins build confidence faster than a dramatic overhaul.
The table below gives you a one-glance view of all 15 money habits, the question each one answers, and a first action that takes less than an hour.
|
Habit |
Question it answers |
First useful action |
|
1. Budgeting and cash flow |
Where will money go before it arrives? |
Map income and bills by date |
|
2. Emergency savings |
How will we handle an unexpected cost? |
Open a separate savings space |
|
3. Debt repayment |
Which balances should get extra money? |
List rates, balances, and minimums |
|
4. Banking fees and interest |
Is our bank charging us unnecessarily? |
Check fees and account rates |
|
5. Insurance and recurring bills |
Are we paying for the right things? |
Audit policies and subscriptions |
|
6. Groceries and household goods |
How can routine purchases cost less? |
Set a realistic category limit |
|
7. Utilities and home costs |
Which home expenses can be lowered? |
Review usage and services |
|
8. Housing affordability |
Is our housing cost sustainable? |
Calculate the full housing cost |
|
9. Transportation |
What does getting around really cost? |
Add payments, fuel, repairs, and insurance |
|
10. Mindful spending |
How can we interrupt impulse buys? |
Add a waiting period for wants |
|
11. Secondhand buying and selling |
When can used goods save cash? |
Build a safe buying checklist |
|
12. Family money routines |
How can the household decide together? |
Create one weekly check-in |
|
13. Earning extra income |
Can we improve the income side? |
Identify one sellable skill or asset |
|
14. Investing basics |
How can money grow over time? |
Learn account, risk, and fee basics |
|
15. Meaningful goals |
What is the money meant to make possible? |
Name one specific, measurable goal |
The habits overlap, but they are not interchangeable. Cutting spending cannot replace emergency savings. A higher income cannot fix borrowing for routine expenses. Investing is valuable, but it should rest on accessible savings and manageable debt. If you want a longer list of quick wins to pair with this system, our frugal living tips collect dozens of small, practical ideas.
Frugal Living for Beginners: Your First 30 Days
For a beginner, a month is long enough to see real results and short enough to stay motivated. This 30-day plan touches the habits that matter most for a beginner, two small actions per week. Nothing on it costs money to start.
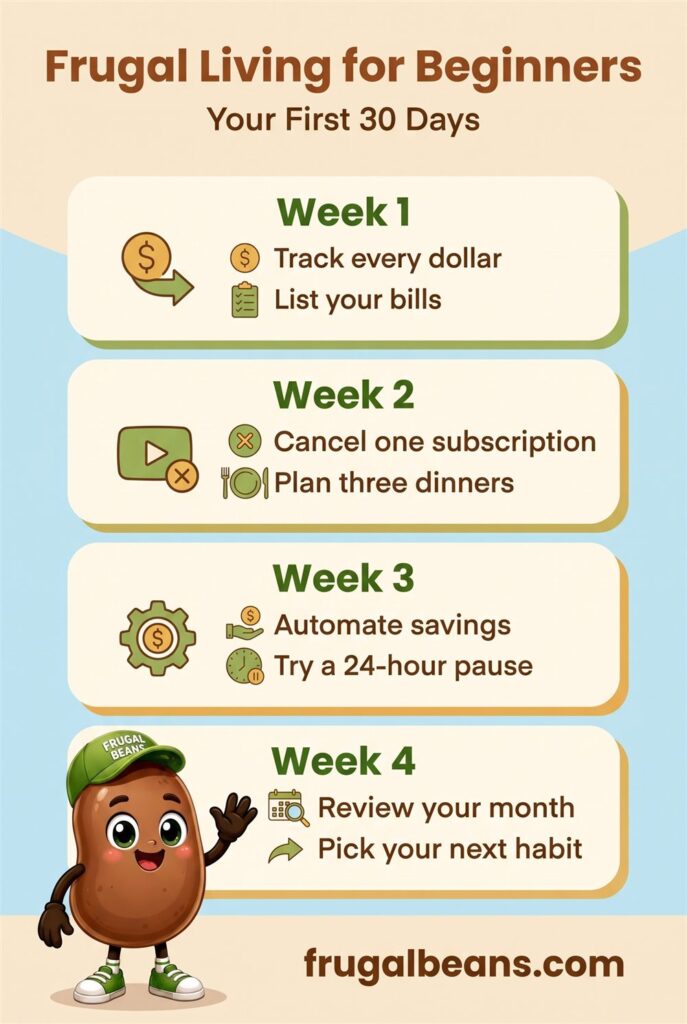
Week 1: Track Every Dollar and List Your Bills
Write down every purchase for seven days, including small ones like coffee, snacks, and app charges. At the same time, list every bill with its amount and due date. By Sunday you will know where money actually goes and which week of the month is tightest.
Week 2: Cancel One Subscription and Plan Three Dinners
Look through your statements for recurring charges and cancel or pause one you did not use last month. Then plan three simple dinners before your next grocery trip, built around what is already in the pantry. These two moves attack the two most common beginner leaks: forgotten charges and last-minute food spending.
Week 3: Automate Savings and Try a 24-Hour Pause
Set up an automatic transfer to a separate savings account the day after payday, even if the amount is small. Then adopt a 24-hour pause on any nonessential purchase. If you still want the item tomorrow and it fits the plan, buy it without guilt.
Week 4: Review Your Month and Pick Your Next Habit
Compare this month’s spending with your Week 1 notes. Celebrate what worked, adjust what did not, and choose the next habit from the list below. Frugal living for beginners is a cycle: notice, decide, act, and review.
15 Simple Money Habits for Frugal Living Beginners
These are the core money habits of frugal living for beginners. Each habit below explains what it covers, why it matters, what to do first, and a mistake to avoid. The small examples use simple numbers so you can see the arithmetic. Your own numbers will differ, and that is fine.
1. Budgeting and Cash-Flow Planning
Budgeting assigns income to needs, goals, debt, and flexible spending. Cash-flow planning adds timing, showing when pay arrives and when bills leave. A household can have enough income for the month and still come up short during one week, so the calendar matters as much as the totals.
Start here: List reliable take-home income, record bills by due date, and divide annual expenses into monthly “sinking fund” amounts. Give the remainder a job, including a modest amount for enjoyment. Review weekly and adjust without treating changes as failure.
Avoid: Budgeting from an ideal month, forgetting irregular expenses, and creating so many categories that the plan becomes exhausting.
Example: If rent is due on the first and insurance on the twentieth, a calendar budget reserves part of the first paycheck for the later bill, preventing a credit card balance even when monthly income is adequate.
2. Emergency Savings
Emergency savings is cash for unplanned, necessary costs such as a car repair, urgent travel, a short income gap, or a major home problem. It is separate from predictable annual expenses. A reserve keeps a shock from becoming expensive credit, a missed payment, or a forced sale of long-term investments.
Start here: Begin with a small starter goal, such as $500 or one week of essential expenses, then build toward several months of core costs as your situation allows. Keep the money separate but accessible, automate a transfer after payday, and refill the account after you use it. The Consumer Financial Protection Bureau’s guide to building an emergency fund walks through setting a goal and finding money to save.
Avoid: Investing emergency money, counting a credit limit as savings, or setting a target so large you never begin. A reserve being used does not mean it failed.
Example: Jordan saves $35 each payday. Six months later, a $420 water-heater repair is paid from savings instead of a card, and the automatic transfer restarts afterward.
3. Debt Repayment
This habit covers credit cards, personal loans, medical balances, vehicle loans, and student debt, plus the routines that keep new debt from replacing old debt. Interest turns yesterday’s purchase into tomorrow’s obligation, and every minimum payment is part of a future paycheck that is already spent.
Start here: List each balance, rate, minimum, and due date. Pay every minimum on time, then send extra money using either the avalanche method, which targets the highest rate first, or the snowball method, which targets the smallest balance first. Keep a small cash buffer, and contact lenders early if payments are becoming unmanageable.
Avoid: Switching methods every month, treating a balance transfer as repayment, and sending every spare dollar to debt while leaving nothing for predictable expenses.
Example: Maya pays all minimums and sends an extra $150 to the highest-rate card. When it is paid off, she rolls that payment into the next balance instead of increasing lifestyle spending.
4. Banking Fees and Interest
Banking includes checking and savings accounts, overdraft charges, ATM fees, account minimums, transfer fees, card interest, and the rate paid on your cash. Fees may be small, but they repeat. Interest earned on safe cash and interest avoided on debt both improve results without extra work hours.
Start here: Review two or three months of statements for fees. Choose accounts whose requirements fit your habits, set low-balance and due-date alerts, and compare savings rates once in a while. Pay card balances in full when you can; otherwise follow a clear repayment plan.
Avoid: Chasing a high rate without understanding access rules, and ignoring repeated small fees because each one looks minor.
Example: Priya pays two $15 overdraft fees each month. An alert and a small buffer stop the fees, returning $360 a year to her budget.
5. Insurance and Recurring Bills
Recurring charges are easy to forget: subscriptions, memberships, software, service contracts, and automatic renewals. Insurance belongs here too, because it protects against losses that would overwhelm a household. The goal is the right protection at a fair price, with no paid-for services you never use.
Start here: Inventory recurring charges at least once a year. For insurance, understand limits, deductibles, and exclusions. Compare quotes after life changes, cancel unused services, and set reminders before promotional rates expire.
Avoid: Dropping essential coverage to save a few dollars, paying for duplicate protection, or assuming an automatic renewal is still the best price.
Example: A household finds three subscriptions and an old roadside membership totaling $62 a month. It keeps the most useful service and redirects $50 to savings.
6. Groceries and Household Goods
Groceries, cleaning supplies, personal-care items, and paper goods are small purchases that repeat constantly. That makes them one of the best places for a beginner to practice frugal living, because a weekly change adds up without touching rent or your job.
Start here: Set a limit based on your actual history, keep a short inventory, compare unit prices, shop with a list, choose store brands when quality is acceptable, and plan for busy nights so takeout does not become the default.
Avoid: Buying bulk without storage space, chasing every discount, and confusing the lowest price with the lowest total cost. An unused cheap item is not a bargain.
Example: A household finds $90 a month going to duplicate toiletries and forgotten cleaning products. A quick inventory before shopping cuts that category by $40.
7. Utilities and Home Costs
This habit covers electricity, heating, water, internet, phone service, and home maintenance. A lower bill, a better service plan, or a timely repair saves money month after month, and preventive care can head off expensive damage. Our guide on how to save money at home goes room by room through the details.
Start here: Compare bills across seasons, investigate unusual increases, seal drafts, change filters, and remove services you do not need. Ask providers about lower plans when promotions end, and keep maintenance records. If you own your home, our free Homeowner Repair Cost Playbook shows typical repair costs and lifespans for major systems so you can plan ahead instead of paying emergency rates.
Avoid: Spending hundreds on an upgrade without calculating payback, or cutting heating and cooling so far that it creates a health risk.
Example: A family drops an unused premium internet feature and changes a phone plan. The $48 monthly reduction goes into a home-repair fund.
8. Housing Affordability
Housing affordability includes rent or mortgage payments, property taxes, insurance, utilities, maintenance, required fees, and the commuting a location creates. Housing is usually the largest fixed expense. If it is too high, small frugal tactics cannot fully repair the budget.
Start here: Calculate the total monthly cost rather than the advertised payment, and stress-test it against income changes and repairs. When comparing homes, include moving costs and commuting. If you are thinking about selling, count the full costs of selling a house before deciding a move will save money.
Avoid: Stretching for a bigger home because the payment is technically possible, ignoring maintenance, and treating a temporary raise as permanent affordability.
Example: A home costs $250 less each month but adds $130 in commuting. The true saving is $120, and the move only makes sense if it does not require another vehicle.
9. Transportation Costs
Transportation means vehicle payments, fuel, maintenance, repairs, registration, parking, insurance, depreciation, transit, and the occasional rental. The payment is only one part of the cost. A car may be essential for work or caregiving, but transportation debt can crowd out every other goal.
Start here: Add up a year of transportation spending and divide by twelve. Keep up with maintenance, compare insurance, combine errands, and use transit, walking, biking, or car-sharing where practical. Before replacing a vehicle, compare repair costs with the full cost of owning the replacement.
Avoid: Shopping by monthly payment, skipping maintenance, and assuming a newer vehicle is automatically cheaper.
Example: Sam’s $410 payment hides another $260 a month for fuel, insurance, repairs, and registration. Seeing the $670 total encourages maintenance and delays an upgrade.
10. Mindful Spending and Impulse Purchases
Mindful spending connects each purchase to a real need, value, or goal. It applies to online shopping, convenience spending, upgrades, social pressure, and emotional purchases. Budgets rarely fail because of one dramatic mistake; they fail through many small unplanned decisions.
Start here: Use a 24-hour or seven-day waiting rule, remove saved payment details from shopping sites, unsubscribe from promotional emails, and keep a running want list. Set aside a small amount of fun money so enjoyment is allowed rather than forbidden.
Avoid: Relying on willpower while keeping triggers everywhere, and labeling every pleasure irresponsible. Mindfulness should support satisfaction, not eliminate joy.
Example: Alex puts a $120 purchase on a seven-day list. A week later, Alex realizes it duplicates something already owned and moves the money to a travel goal.
11. Secondhand Buying and Selling
Secondhand habits include buying used furniture, tools, clothing, electronics, and vehicles, and selling things you no longer need. Used goods can lower purchase prices and keep useful items in circulation. Selling can turn clutter into cash, though skipping the purchase entirely is often the bigger win.
Start here: Decide on required features before browsing, research typical prices, inspect condition, check safety recall information, and count transport and repair costs. When selling, describe items honestly, protect personal information, and use safe meeting and payment practices.
Avoid: Buying something only because it is cheap, ignoring missing parts, and spending hours selling an item worth very little.
Example: Noor buys a sturdy used desk for $70, pays $20 for transport, and saves $190 compared with a $280 new desk, after confirming its condition and dimensions.
12. Family Money Routines
Family routines are shared practices that make good money behavior normal: a weekly planning talk, a repair-first rule, a library habit, or an agreement about gifts. One person cannot carry every financial decision forever. Shared routines reduce conflict and teach children that money is a tool rather than a secret.
Start here: Hold a 15-minute weekly check-in about upcoming bills and plans. Give age-appropriate responsibilities, build low-cost traditions, and agree on spending limits and how to handle exceptions.
Avoid: Making frugality feel like punishment, criticizing a partner’s every purchase, or passing adult money stress on to children.
Example: Every Sunday, a family checks the calendar, picks two free activities, and confirms upcoming bills. Fifteen minutes prevents several last-minute purchases.
13. Earning Extra Income
Frugal living is not only about cutting. There is a limit to how far expenses can fall, while a useful skill or asset can bring in more money. This habit covers raises, job changes, freelance work, small services, and selling skills.
Start here: Begin with a skill, asset, or available hour you already have. Calculate net income after taxes, supplies, travel, platform fees, and time. Ask for a raise with evidence of results, and set aside part of any irregular income for taxes.
Avoid: Treating revenue as profit, underpricing your time, or buying expensive equipment before testing demand. Extra work also has a health and family cost.
Example: Lee earns $300 from tutoring but spends $45 on travel and supplies. The $255 net amount goes toward debt, with a tax reserve set aside.
14. Investing Basics and Long-Term Wealth
Investing puts money into assets that may grow or produce income over time. For a beginner, the essentials are time horizon, diversification, risk, account types, fees, and the difference between investing and speculation. Consistent contributions often matter more than trying to predict short-term prices.
Start here: Build emergency savings and deal with high-interest debt before taking on significant risk. Learn each account’s purpose, fees, tax treatment, and withdrawal rules. Match investments to your time horizon, diversify, and automate a contribution you can afford.
Avoid: Investing emergency money, following unverified tips, trading often, ignoring fees, and expecting guaranteed returns. Do not invest in something you cannot explain plainly.
Example: After building a cash reserve, Elena sets up a modest automatic contribution to a diversified long-term option and reviews it twice a year instead of reacting to daily market news.
15. Financial Independence and Meaningful Goals
Financial independence means having enough control over income, savings, and expenses to make important choices without being trapped by every paycheck. The goal might be a career change, caregiving, fewer work hours, school, travel, or simply a calmer buffer. Frugal habits are much easier to keep when they serve a clear purpose.
Start here: Write three goals with a time frame, an amount, and a reason. Separate short-term goals from long-term ones, track progress, celebrate milestones, and revise plans when work, health, or family changes.
Avoid: Copying someone else’s definition of success, postponing all enjoyment, or chasing a savings rate that harms your health or relationships.
Example: Instead of saying “retire early,” Chris aims to work four days a week in five years. The specific target makes saving, debt, and skill-building decisions concrete.
Turn the 15 Money Habits into a Simple Routine
You do not need to work on all 15 habits every day. Each week, spend 15 to 30 minutes checking balances, due dates, flexible spending, and one chosen habit. Write down one action, one decision, and one question. A system that produces decisions is more useful than paperwork that produces guilt.
- Weekly: Check balances, upcoming bills, and the next seven days of plans.
- Monthly: Compare spending with the budget, move money to savings, update debt balances, and question one recurring cost.
- Quarterly: Review insurance, transportation, income opportunities, and your main goals.
- Annually: Recalculate fixed costs and decide which habits deserve more attention next year.
Rotate the deeper topic each month: transportation one month, insurance the next, family routines after that. Over a year, every habit gets a proper look without any single week feeling overloaded.
Adapting Frugal Living to Your Income and Household
Frugal living for beginners looks different in every household, so adjust these money habits to fit your situation. On a low or unstable income, start with cash-flow visibility, essential bills, assistance programs, and protection from high-cost debt. A budget is not a moral judgment when income is not enough. It can show whether the real solution is benefits, negotiation, community resources, or a job change rather than another tiny cut. Our guide to saving money on a tight budget focuses on exactly that situation.
For a moderate-income household, the largest gains usually come from fixed costs, debt strategy, insurance, transportation, and automatic savings. Send part of every raise to goals before lifestyle creep absorbs it.
For a higher-income household, focus on intentional spending, appropriate risk, taxes, fees, and long-term goals. A bigger paycheck can hide waste, but it does not remove the need for a reserve or a plan.
Single adults may want a larger reserve because one income carries more risk. Couples should talk about shared and separate money without turning differences into a scorecard. Families with children need room for care, school, and activities. Older adults and caregivers may put more weight on health costs, housing safety, and reliable cash flow. The right version of frugality protects your household’s actual weak spots.
How to Choose Trustworthy Money Advice
Prefer information that explains its assumptions, separates facts from opinions, discloses costs, and admits risk. Be cautious when a claim promises fast wealth, guaranteed returns, effortless debt elimination, or a product that is right for everyone.
Compare more than one credible source before a major decision, and favor sources that encourage questions rather than pressure you to act today. Government resources are a good neutral starting point; the CFPB’s Start Small, Save Up page has free tools for building a savings habit. For major tax, legal, insurance, or investment decisions, consider qualified professional advice and ask what it costs up front.
Frugal Living for Beginners: Frequently Asked Questions
What is the first step in frugal living for beginners?
Track your spending for one week and list every bill with its due date. You cannot cut what you cannot see. Once you know where money goes and when bills land, choose one habit, such as canceling an unused subscription or planning three dinners, and build from there.
How much money can a beginner save with frugal living?
It depends entirely on your starting point, so track your own numbers instead of chasing a headline figure. Small repeated changes add up: stopping two $15 overdraft fees a month returns $360 a year, before counting any grocery, subscription, or utility savings.
Is frugal living the same as being cheap?
No. Being cheap focuses only on the lowest price, even when that item breaks quickly or costs more over time. Frugal living looks at total cost and value, and it leaves room to spend on the things you truly care about.
How long does it take to build frugal money habits?
Most people notice a difference within the first month if they focus on one or two habits at a time. Use the 30-day plan above, then add a new habit each month. Expect setbacks; a missed week is information, not failure.
The Bottom Line
The 15 money habits in this guide are not 15 rules for living a smaller life. They are 15 ways to make your money more intentional. Budgeting gives income direction. Emergency savings absorbs shocks. Debt repayment frees future paychecks. Smarter choices about bills, food, home, housing, and transportation protect the biggest parts of the budget. Mindful spending, family routines, extra income, investing, and clear goals turn today’s decisions into long-term freedom.
The best approach to frugal living for beginners is to start small: pick one habit this week, follow the 30-day plan, and give each new habit a place in your monthly routine. You do not need to be perfect. You need a system that helps you notice, decide, and act before small problems become expensive ones. For more everyday ideas once you have the basics in place, browse our full list of ways to save money.
This guide is for general education and planning. Apply the ideas to your own circumstances and verify important account and policy details.
FIRE Movement Explained: 7 Simple Steps to Financial Independence
The FIRE movement—short for Financial Independence, Retire Early—can sound like a club reserved for high earners, spreadsheet experts, or people willing to live on almost nothing. In practice, it is less about escaping work on a particular birthday and more about gaining control over your choices. You build enough financial strength that a job becomes a tool rather than your only source of security.
Think of yourself as the pilot of an ordinary household financial plan. A good pilot does not stare only at the final airport. The pilot checks fuel, watches the instruments, adjusts for weather, and keeps everyone on board informed. Your household can use the same approach: a clear destination, reliable information, sensible controls, and a willingness to make small corrections before a minor problem becomes an emergency.
This guide lays out that system in plain language. You will learn what financial independence really means, how to estimate a FIRE number, how lean FIRE differs from other versions, and seven simple steps you can start this month. Nothing here is personal financial advice; it is a framework to help you ask better questions about your own situation.
A quick note on the name: this post was originally titled “Captain FI: The FIRE Personal Finance Pilot,” and “Captain FI” was our metaphor for a household steering its own money. There is also a real personal finance blog and podcast called Captain FI, run by an Australian pilot under that pen name, which is still publishing in 2026. This article is not about that creator, and we are not affiliated with it. We mention it in the resources section below for readers who go looking.
What the FIRE Movement Really Means
At its core, the FIRE movement is about financial independence: your essential life can be funded without depending entirely on a paycheck. That funding might come from investments, a pension, a business, rental income, or a combination of sources. Retiring early is only one possible use of that independence. You might leave a stressful career, work part time, care for family, study, volunteer, or start a less lucrative but more meaningful business.
Financial independence, retire early is therefore not a single finish line. It is a range of milestones. An emergency fund makes you less vulnerable to an unexpected bill. Paying off high-interest debt gives you breathing room. Saving enough to cover a year of expenses can let you take a sabbatical. Full independence provides the broadest set of options.
A useful distinction is between savings rate and net worth. Your savings rate is the portion of income you keep for future use. Net worth is what you own minus what you owe. A high savings rate helps, but a household also needs cash access, insurance, and a plan for near-term bills. Followers of the FIRE movement tend to watch both numbers, because one shows your habits and the other shows your progress.
Why Frugality Is the Engine
Every dollar you do not need to spend does two jobs at once. It can be saved and invested today, and it lowers the amount you will need to fund your life later. That double effect is why frugal habits sit at the heart of the FIRE movement. You do not need to be extreme; you need to cut waste around the things you genuinely value. Our guide to frugal living for beginners is a good place to start if this part feels new.
Lean FIRE, Fat FIRE and Other Paths
People in the FIRE movement use a handful of informal labels to describe different destinations. These are community nicknames, not official categories, and the dollar lines between them are fuzzy. Still, they help you decide what kind of independence you are aiming for.
Lean FIRE
Lean FIRE means reaching independence on a deliberately modest budget, roughly covering essentials with little room for extras. Because the spending target is lower, the savings target is lower too, so lean FIRE can be reached sooner. The trade-off is a thinner cushion: an unexpected health cost, a major home repair, or a long market slump can put real pressure on the plan.
Fat FIRE
Fat FIRE is the opposite end: independence that funds a comfortable or generous lifestyle, with travel, hobbies, and family support built in. It usually takes longer to reach, but it leaves more margin for surprises.
Coast FIRE and Barista FIRE
Coast FIRE describes a point where you have saved enough early that, if left to grow, your investments could plausibly cover a traditional retirement, so you only need to earn enough to pay current bills. Barista FIRE describes a mix: investments cover part of your costs and part-time or lower-stress work covers the rest, sometimes along with workplace benefits. Both versions treat work as optional in intensity rather than eliminating it.
None of these paths is better than the others. Lean FIRE suits people who truly enjoy simple living; fat FIRE suits people who would rather work longer for a wider margin. Most households in the FIRE movement end up somewhere in between, and many change their minds along the way.
The FIRE Movement in 7 Simple Steps
The rest of this guide walks through the steps one by one. Here is the full flight plan at a glance:
- Define your destination with three versions of your future budget.
- Know your cash flow by tracking real spending.
- Build a strong cockpit: emergency reserves, debt control, and insurance.
- Raise your savings rate gradually.
- Invest simply and consistently.
- Estimate your FIRE number.
- Review the route every year and correct course.
Step 1: Define Your Destination
Start with a destination specific enough to guide decisions. “Be rich” is too vague. “Have the flexibility to work four days a week within eight years while keeping our current housing and health coverage” is far more useful.
Write down three versions of your future budget:
- Essential spending: housing, food, utilities, basic transportation, insurance, taxes, health care, and minimum debt payments.
- Comfortable spending: essentials plus ordinary travel, hobbies, gifts, dining out, clothing, and home maintenance.
- Abundant spending: comfortable spending plus larger goals such as frequent travel, generous family support, or an expensive hobby.
These categories prevent a common mistake: treating every current purchase as permanent while pretending future life will be free. A household might spend $4,500 per month today, but perhaps $3,600 is essential and $5,200 is the life it wants. Each number produces a different savings target, and roughly speaking, the essential budget is your lean FIRE line.
Review the plan with the people affected by it. A partner may value predictable travel more than an especially early retirement date, while children create changing costs. Include these preferences rather than labeling them as obstacles.
Step 2: Know Your Cash Flow
Cash flow is the movement of money into and out of your household. Track it for at least one ordinary month, preferably three that include irregular expenses. Use bank statements, credit card records, and annual bills. Do not rely on memory; people forget subscriptions, insurance premiums, school costs, and gifts.
Sort expenses into three groups. Fixed expenses are difficult to change quickly, such as rent or a mortgage. Flexible expenses can move up or down, such as groceries, restaurants, and entertainment. Irregular expenses arrive periodically, such as car repairs, property taxes, and holiday travel. Divide annual irregular costs by twelve and set that amount aside monthly. This turns surprises into planned bills.
A simple cash-flow review should answer four questions:
- How much income reliably arrives after taxes and payroll deductions?
- What must be paid before the next payday?
- Which expenses are recurring but not essential?
- How much can be directed automatically toward reserves and long-term goals?
The objective is not to judge every purchase. It is to make the route visible so you can reduce costs, increase income, or accept a longer timeline. If you need help setting category amounts, our budgeting tips for a tight budget walk through it step by step.
Step 3: Build a Strong Cockpit Before Investing
Before taking substantial investment risk, establish a basic safety structure. Keep a starter emergency reserve in an accessible account. Then expand it until it can cover several months of essential expenses, with the amount depending on job stability, health, dependents, and how quickly you could replace your income.
Pay particular attention to high-interest debt. Credit card balances and similar debt can grow faster than a reasonable investment return. Make minimum payments on every debt, direct extra money toward the highest interest rate, and then roll the freed payment toward the next balance. The smallest-balance-first approach can also work if it keeps you motivated and consistent.
Insurance is financial protection. Health, disability, auto, renters or homeowners, and liability coverage can prevent one event from undoing years of progress. Review coverage when income, housing, dependents, or assets change.
Homeowners should also plan for the big-ticket systems that eventually wear out, such as the roof, furnace, and water heater. Our free Homeowner Repair Cost Playbook lists typical lifespans and repair costs so you can build them into your budget instead of being surprised.
Keep short-term money separate from long-term investments. Money needed within the next few years generally deserves stability and access rather than exposure to a sharp market decline. The emergency reserve is not failing to grow; it is doing its job by being available.
Step 4: Raise Your Savings Rate
In the FIRE movement, your savings rate is the single lever that most shapes your timeline, because it affects both sides of the equation: how fast your investments grow and how much you will eventually need. Raising it does not have to mean deprivation. It usually means trimming waste, avoiding lifestyle creep, and directing new income on purpose.
Here is simple arithmetic to show why small changes matter. If a household takes home $5,000 a month and saves 10%, that is $500 a month. Raising the rate to 15% means $750 a month—an extra $3,000 a year directed at the future, without counting any investment growth.
Good places to look first are the everyday leaks: groceries that get thrown out, unused subscriptions, and convenience purchases made when you are rushed. Our list of practical ways to save money and our guide on how to save money at home are full of low-effort ideas. Earning more counts too: a raise, a side project, or a career move can lift the rate faster than cutting alone.
Step 5: Invest Simply and Consistently
Investing means putting money into assets that can grow or produce income over time. A diversified portfolio spreads money across many companies, bonds, or other assets instead of depending on one investment. Diversification cannot prevent all losses, but it reduces single-investment risk.
For many households, broad, low-cost funds are easier to maintain than individual stocks. The right mix depends on time horizon, risk tolerance, tax situation, and account types. Risk tolerance means how well you can stick to the plan after a large temporary decline, not merely how comfortable you feel when markets rise.
Use available tax-advantaged workplace and individual accounts when they fit your situation. These accounts may offer deductions, tax-deferred growth, or tax-free withdrawals under specific rules. Understand the contribution limits, withdrawal conditions, and employer matching policy before making decisions. Early retirees in particular should learn the rules for accessing retirement accounts before the standard age, because some withdrawals can trigger taxes and penalties.
Automate contributions on payday. Automation removes a fresh monthly decision. Increase the amount after a raise, a debt payoff, or an ended expense. Rebalance occasionally if the mix drifts, but avoid constant tinkering. A boring plan you can follow is stronger than a clever plan that causes panic. To see how steady contributions can add up over time, the SEC’s compound interest calculator on Investor.gov lets you try your own numbers.
Step 6: Estimate Your FIRE Number
Your FIRE number is a rough estimate of how much you would need invested so that your portfolio could fund your yearly spending. The most commonly cited shortcut is to multiply your expected annual expenses by 25. That shortcut comes from the so-called 4% rule, because 4% is the same as one twenty-fifth.
Where the 4% Rule Comes From
The 4% rule traces back to research by financial planner William Bengen, published in the Journal of Financial Planning in the mid-1990s. Using historical U.S. market data, he looked at how much a retiree could withdraw in the first year, then adjust for inflation each year after, without running out of money over about 30 years. A 4% starting withdrawal held up across the historical periods he tested.
In 1998, three Trinity University professors—Philip Cooley, Carl Hubbard, and Daniel Walz—published a related analysis, often called the Trinity study, in the AAII Journal. You can read their article, “Retirement Savings: Choosing a Withdrawal Rate That Is Sustainable”, on the AAII website. Together, this research made the 4% figure a popular rule of thumb.
A Worked Example
Go back to the three budgets from Step 1 and turn each monthly figure into a yearly one, then multiply by 25:
|
Budget |
Monthly |
Yearly |
Yearly x 25 |
|
Essential (lean FIRE) |
$3,600 |
$43,200 |
$1,080,000 |
|
Current |
$4,500 |
$54,000 |
$1,350,000 |
|
Desired (comfortable) |
$5,200 |
$62,400 |
$1,560,000 |
These are illustrative examples, not targets. Notice how much the FIRE number moves with spending: every $100 of monthly spending you can comfortably live without lowers the target by $30,000 ($1,200 a year times 25). That is the frugality engine at work.
Why Your FIRE Number Is Only an Estimate
The 4% rule is a starting point, not a promise. The original research looked at roughly 30-year retirements, while someone who stops working at 40 may need money to last much longer, so some early retirees plan around a lower withdrawal rate and a larger target. Future returns, inflation, and taxes may also look different from the past.
Other income changes the math. Social Security, a pension, rental income, or part-time work can cover part of your spending, which lowers the amount your portfolio has to supply. Health insurance before Medicare eligibility is a major cost for U.S. early retirees and belongs in the essential budget. Treat your FIRE number as a direction on the map, revisit it every year, and consider getting help from a fee-only professional for complicated situations.
A Note on Australian FIRE Content
Much popular FIRE material comes from Australia, including the Captain FI blog. Australian guides often discuss superannuation, the compulsory workplace retirement system there, along with Australian brokers, taxes, and pension rules. The broad ideas carry over, but the details do not. U.S. readers should look at U.S. account types such as 401(k) plans and IRAs, U.S. tax rules, and Social Security instead of copying Australian strategies.
Step 7: Review the Route and Correct Course
A FIRE plan should change with reality. The following dashboard turns broad goals into manageable checks. The figures are examples, not universal rules.
|
Area |
Pilot’s question |
Example action |
|
Cash reserve |
Could we handle a large essential bill without new debt? |
Build a $12,000 reserve in stages |
|
Debt |
Which balance costs us the most each month? |
Pay extra toward a 24% credit card balance |
|
Savings rate |
What portion of take-home pay serves future goals? |
Raise saving from 10% to 15% after a raise |
|
Investing |
Is the portfolio diversified and suited to our timeline? |
Use a simple allocation and review annually |
|
Protection |
What event could damage our plan most? |
Check disability and liability coverage |
|
Lifestyle |
Which spending creates genuine value? |
Keep weekly family meals; cut unused subscriptions |
|
Flexibility |
What choice would money make possible? |
Build a six-month runway for a career change |
Review this dashboard monthly for cash flow and quarterly for larger decisions. A yearly review can cover insurance, beneficiaries, account fees, tax withholding, family changes, and an updated FIRE number.
Your Path to FI: The Simple Version
If seven steps feel like a lot, the whole FIRE movement can be boiled down to five repeating habits. Print the infographic, stick it on the fridge, and work through one habit at a time.
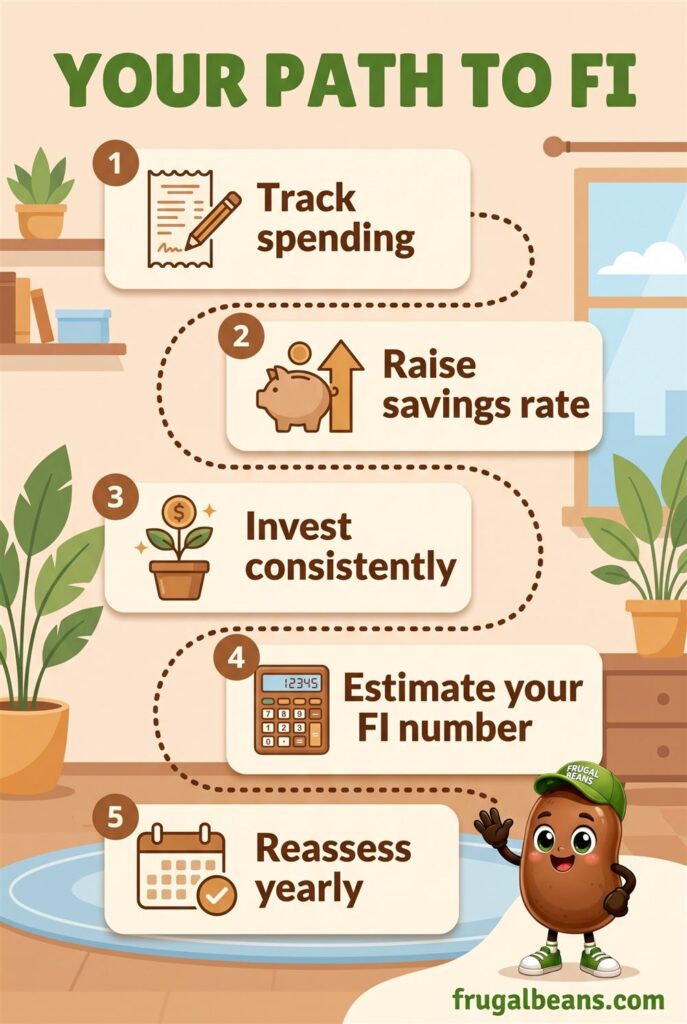
- Track spending. Know where the money actually goes before you try to change it.
- Raise your savings rate. Nudge it up after every raise, payoff, or canceled bill.
- Invest consistently. Automate contributions into simple, diversified investments.
- Estimate your FI number. Use yearly expenses times 25 as a rough starting point.
- Reassess yearly. Update your budget, your number, and your goals as life changes.
Practical Tips for Everyday Navigation
Give every irregular bill a runway. List annual costs and transfer one-twelfth of each amount into a separate sinking fund every month. When the bill arrives, the money is waiting.
Use a waiting period for nonessential purchases. For a costly item, wait a day or a week depending on the price. The pause separates a need from an emotional reaction and gives you time to compare.
Direct raises before they disappear. When income increases, assign part of the raise to investing or debt repayment before adjusting everyday spending. Keep some portion for enjoyment so progress does not feel like permanent deprivation.
Make convenience deliberate. Paying for delivery, prepared meals, or a closer home may be worthwhile if it buys time and fits the plan. Frugality is useful when it supports your values, not when it turns every decision into punishment. Our frugal living tips focus on that balance.
Measure progress with several gauges. Track savings, debt reduction, emergency-fund months, and the choices your money can support. Net worth may move unpredictably while your behavior steadily improves.
Schedule a calm money meeting. Partners can meet for thirty minutes with the same agenda each time: upcoming bills, account balances, one decision, and one positive result. Avoid meetings during arguments or right after stressful purchases.
Protect the downside first. Before seeking a higher return, ask what could force you to sell at the worst moment. Reserves, insurance, a diversified portfolio, and manageable fixed costs make the plan more durable.
Common Turbulence on the Way to Financial Independence
Job loss, illness, a new child, caregiving, divorce, relocation, or a major repair can require a temporary reduction in investing. Pausing contributions is not failure if it protects the household. Resume the previous rate when conditions stabilize.
Beware of extremes. Cutting every enjoyable activity can create burnout and make the plan impossible to sustain—a real risk for anyone chasing lean FIRE too hard. Chasing a very high return can expose essential money to unacceptable risk. Assuming expenses will fall dramatically in later life can create a misleading target. Model several futures, including higher health costs, a longer life, and a period of lower investment returns.
Taxes and account rules can influence the best order for saving, but complexity has a cost. If a strategy requires constant monitoring or creates anxiety, simplify it. For complicated situations, understand how a professional is paid before agreeing to advice.
The Many Resources in the Pilot’s Kit
A good financial plan is supported by a collection of resources rather than one perfect trick. Your kit can include a one-page net-worth statement, a spending tracker, a debt list, account statements, a short written investment plan, an insurance summary, and a calendar of annual bills. Keep the documents secure and tell a trusted household member where important information is stored.
Learning resources matter too. Read plain-language explanations of taxes, retirement accounts, investing, insurance, and consumer protections. Government sites such as Investor.gov are a good neutral starting point. Compare advice, especially when someone is selling a product. A useful resource explains costs, risks, trade-offs, and bad scenarios rather than promising certainty.
Blogs and podcasts from people pursuing financial independence and early retirement can be motivating. One example is the Captain FI blog and podcast mentioned at the top of this post, where an Australian pilot shares his own journey and interviews guests about investing and early retirement. Just remember that its account, tax, and pension details are written for Australians.
A community can provide encouragement, but never outsource judgment. Another household’s income, costs, health needs, and responsibilities may differ completely from yours. Use outside ideas as prompts, not instructions to copy.
FIRE Movement FAQ
What is the FIRE movement?
The FIRE movement is a personal finance approach built around financial independence, retire early. Followers spend deliberately, save a large share of their income, and invest it so that, eventually, investments and other income can cover their essential costs. “Retire early” is optional; many people use independence to work less or change careers rather than stop working.
How do you calculate your FIRE number?
A common rough method is to multiply your expected yearly expenses by 25, which reflects the 4% rule of thumb. For example, $40,000 a year times 25 is $1,000,000. Treat it as an estimate: longer retirements, taxes, health costs, and other income such as Social Security can all change the figure.
What is lean FIRE?
Lean FIRE means reaching financial independence on a modest, essentials-focused budget. Because spending is lower, the FIRE number is lower and can be reached sooner, but there is less margin for surprises such as medical bills or long market downturns.
Is the FIRE movement realistic on an average income?
Full early retirement is harder on an average income, but the habits still pay off. Tracking spending, raising your savings rate, and investing consistently can build an emergency fund, reduce debt, and create more choices over time, even if your timeline is longer than the headline stories.
The Bottom Line
The FIRE movement is not about never spending, never worrying, or predicting the market perfectly. It is about a household that knows its essential costs, protects against serious setbacks, saves automatically, invests with a clear purpose, and reviews the route without panic.
Start with one cockpit check this week. Find your true monthly essentials, cancel one unused expense, set up one automatic transfer, or list your debts and interest rates. Then repeat the process next month. Financial independence grows from ordinary decisions made consistently, not from a dramatic leap.
The most valuable destination is not simply an early retirement date. It is the ability to choose work, rest, generosity, learning, and family time with less fear. When your money supports those choices, you are practicing financial freedom along the way.
Costs of Selling a House: 12 Essential Expenses to Budget For
The costs of selling a house add up to far more than most owners expect, because the sale price is not the amount you take home. Selling a house can turn years of mortgage payments and upkeep into a large amount of cash, but along the way you may pay for preparation, marketing, professional help, closing costs, taxes, a loan payoff, and the final move.
Some of those costs are easy to predict. Others appear only after a buyer’s inspection or in the last week before closing. Understanding the full picture helps you set a realistic asking price, compare offers fairly, and avoid being surprised by a much smaller check than you planned on.
This guide walks through the 12 essential expenses in plain language, shows a worked example of where the money goes, and ends with a seller’s checklist you can use before you list. It is general information, not legal or tax advice, so confirm the details for your own sale with the professionals handling it.
The Basic Math: Sale Price Is Not Net Proceeds
Your net proceeds are the money left after the sale price is reduced by every required and agreed expense. Before you look at any single fee, it helps to see the whole equation:
Estimated net proceeds = sale price − selling costs − loan payoff − other liens − moving and related costs
For example, imagine a house sells for $425,000. The seller pays $25,500 in agent compensation, $4,250 in other closing charges, $3,000 for repairs and preparation, and $6,000 to move. If the mortgage and other liens total $300,000, the seller’s approximate remaining cash is $86,250:
$425,000 − $25,500 − $4,250 − $3,000 − $6,000 − $300,000 = $86,250
That is still a meaningful sum, but it is about one-fifth of the sale price. Keeping this formula in front of you is the simplest way to keep the cost to sell a house from being a guess.
The 12 Costs of Selling a House at a Glance
Every sale is different, and not every seller will pay all of these. Still, it is smart to budget for each one until you know it does not apply to you:
- Agent compensation for the listing agent and, in some deals, money connected to the buyer’s agent.
- Pre-listing repairs such as fixing leaks, broken fixtures, or safety problems.
- Cleaning, paint, and yard work to make a strong first impression.
- Staging and temporary storage to make rooms look larger and easier to picture.
- Marketing and listing extras such as photography, floor plans, or video tours.
- A pre-listing inspection, if you choose to get one.
- Buyer-requested repairs or credits after the buyer’s inspection.
- Settlement, escrow, and attorney fees for handling the documents and money.
- Title, recording, and transfer charges tied to ownership changing hands.
- Prorated property taxes and association dues through the closing date.
- Mortgage payoff, liens, and possible taxes on the gain.
- Moving and carrying costs, including any overlap between two homes.
The sections below explain each group, what changes the amount, and where you have room to negotiate.
Agent Commissions: Often the Biggest Cost to Sell a House
For many households, the largest single cost to sell a house is compensation for real estate professionals. A listing agent usually helps price the property, prepares the marketing, arranges showings, communicates with buyers, and guides the transaction toward closing. In some transactions, a buyer’s agent may also receive compensation connected to the sale.
There is no single standard rate. The structure and amount of agent pay vary by market, by brokerage, and by contract, and they are negotiable. Practices for how buyer-agent pay is offered and agreed also differ, so ask your agent to explain in writing how it works in your area and who is expected to pay what.
Why every percentage point matters
When pay is quoted as a percentage of the sale price, small differences become large dollar amounts. On a $400,000 sale, every one percentage point equals $4,000. On a $300,000 sale, it equals $3,000. Run the numbers in dollars before you sign, not just in percentages.
Read the listing agreement carefully. It may include a cancellation fee, an administrative or transaction charge, or a different rate if the same agent represents both sides. Ask what is included in the fee, such as photography, staging advice, or open houses, and what will be billed separately.
Selling a house without a listing agent
Some owners choose to sell without a traditional listing agent. This can reduce agent compensation, but it does not make selling a house free. The owner may pay for photographs, listing exposure, signs, scheduling tools, legal help, and professional negotiation. The owner also spends time answering inquiries, showing the house, reviewing offers, and coordinating inspections.
Consider the value of that time and the risk of mistakes before assuming the savings are substantial. A buyer who is still working with an agent may also expect that agent to be paid by someone, which can become part of the negotiation.
Repair and Inspection Costs of Selling a House
Preparation is the part of the costs of selling a house you control most directly, and it can range from almost nothing to a major renovation. The most useful work usually improves cleanliness, safety, function, and first impressions rather than adding expensive personal features. Buyers notice deferred maintenance because it raises questions about what else may be wrong.
Pre-listing repairs and cleanup
Common preparation expenses include:
If the furnace, air conditioner or water heater needs work before you list, our free repair or replace calculator shows whether fixing it or replacing it makes more sense for a unit that age. That keeps one of the bigger costs of selling a house in proportion.
- Deep cleaning, carpet cleaning, and removal of excess belongings.
- Painting walls or touching up visible scuffs.
- Lawn care, trimming, seasonal planting, and exterior cleanup.
- Minor plumbing, electrical, roofing, heating, or cooling repairs.
- Replacing damaged fixtures, loose handles, broken screens, or burned-out lights.
Before spending, separate repairs that could stop a buyer from getting financing from improvements that are merely attractive. A leaking roof, unsafe wiring, or a failed heating system may deserve priority. A luxury countertop may not recover its cost. Ask for several estimates and decide whether each repair is needed for safety, disclosure, negotiation, or presentation.
If you are not sure what a fair repair price looks like, our free Homeowner Repair Cost Playbook lists typical lifespans and repair costs for the major systems in a house, which helps you judge quotes before you list.
Should you pay for a pre-listing inspection?
A pre-listing inspection is optional. It costs money up front, but it can reveal problems on your schedule rather than the buyer’s. You can then fix an issue, get a quote to share, or price the home with the problem in mind. The trade-off is that what you learn may need to be disclosed, so ask your agent or attorney how disclosure works where you live.
Repairs and credits after the buyer’s inspection
Most buyers order their own inspection, and the report often leads to a request. The buyer may ask you to complete repairs, lower the price, or give a credit at closing. Any of these choices reduces your proceeds, so it belongs in your budget even though you cannot know the exact amount in advance. A reserve for inspection surprises is one of the most practical lines on a seller’s worksheet.
Staging, Marketing, and Listing Extras
Marketing is a smaller part of the cost to sell a house, but it adds up. Some marketing expenses are included in an agent’s service, while others are separate. Confirm this rather than assuming. Possible charges include professional photography, measured floor plans, printed materials, online advertising, open-house supplies, signage, video tours, and virtual staging.
Professional staging or rented furniture can make rooms easier to understand, especially if the house is empty. Temporary storage can also help, because clutter makes rooms look smaller. These costs are flexible: you can often get much of the effect by decluttering, rearranging what you own, and borrowing a few pieces. The habits in our guide on how to save money at home apply here too, since every box you donate before the move is one you do not pay to store or haul.
Closing Costs Paid by the Seller
Closing is the final stage, when ownership changes and money is distributed. Seller closing costs are a group of transaction charges, and which party pays each one depends on local practice, the purchase contract, and negotiation. That is why closing costs vary so widely from one sale to the next.
|
Possible seller expense |
What it covers |
What can change the amount |
|
Settlement or escrow fee |
Administrative work to coordinate documents and money |
Company, location, and complexity of the sale |
|
Attorney or conveyance fee |
Legal review and preparation of required documents |
Local rules and attorney rates |
|
Title-related charge |
Research, insurance, or transfer work connected with ownership |
Property history and regional custom |
|
Recording or transfer charge |
Government filing or transfer of ownership |
Sale price and local rules |
|
Inspection-related credit |
Money offered to address issues found by the buyer |
Inspection results and negotiation |
|
Home warranty or service plan |
Optional coverage offered to reassure a buyer |
Coverage selected and contract terms |
|
Prorated property taxes or fees |
Seller’s share through the closing date |
Closing date and billing schedule |
Buyer credits and concessions
A seller may also agree to give the buyer a closing credit. This is an amount deducted from the seller’s proceeds to help the buyer pay certain approved closing costs or to address an issue. For example, a seller might offer a $5,000 credit instead of completing a repair. A credit can keep a transaction moving, but it reduces your net proceeds just as surely as a direct payment.
Prorated property taxes
At closing, property taxes are often prorated so that the seller pays the portion covering the days before the sale and the buyer pays the portion after it. This is an allocation of an existing bill, not an extra cost created by selling. It still shows up on the settlement statement, so expect to see it. Association dues and some utility charges may be handled the same way.
Mortgage Payoff, Liens, and Other Debts
Your mortgage lender must be paid from the sale proceeds. The payoff amount is not always the same as the balance on your monthly statement. It may include interest through a future date, a processing fee, or a prepayment charge. Request a formal payoff quote early enough for your closing team to use an accurate figure.
Other debts attached to the property can also reduce your proceeds. Examples include a second mortgage, a home-equity line of credit, an unpaid contractor claim, a judgment, an association balance, or a property-tax debt. These claims may be called liens, meaning a legal right connected to the property that must be resolved before clear ownership can transfer.
If the sale price may be close to what you owe, calculate the numbers before accepting an offer. A seller who owes $390,000 on a property that sells for $400,000 has only $10,000 of room, and could still need thousands more for commissions, closing costs, repairs, and the move. In some cases, the owner must bring money to closing or obtain lender approval for a short sale. Do not wait until the final week to learn that the proceeds are not enough.
Taxes When Selling a House
Selling a home can create tax questions, especially when the property was not your main residence the whole time. The result can depend on how long you owned and lived in the home, your purchase price, documented improvements, selling expenses, any past use as a rental, and state or local rules.
According to IRS Publication 523, Selling Your Home, many owners can exclude up to $250,000 of gain from the sale of a main home, or up to $500,000 for married couples filing jointly, if they meet ownership and use tests. In general, that means owning the home and living in it as your main home for at least 2 of the 5 years before the sale. The same publication explains that selling expenses, such as agent commissions, advertising, and legal fees, are subtracted from the sale price when figuring the amount realized.
That is one more reason to keep every receipt. Routine repairs and ordinary maintenance are not always treated like lasting improvements, so keep invoices and records rather than relying on memory. If your situation includes a rental, a home office, an inherited property, or a short ownership period, talk with a tax professional before you sign a contract.
Moving and Carrying Costs After Closing
Moving expenses are often left out of the costs of selling a house because they are paid after the transaction. Include them anyway. You may pay movers, packing help, boxes, storage, transportation, cleaning at the new home, utility connection fees, temporary lodging, or pet care.
The timing of two homes can create a larger cost. If you buy before the old house closes, you may carry two mortgages or two housing payments, plus insurance and utilities on both. If the sale closes before your next home is ready, you may need short-term storage or a hotel. Build a cash reserve for timing problems, even when the sale itself looks profitable.
Smaller moves cost less. Selling or donating furniture you will not use, collecting free boxes, and packing yourself are classic ways to save money on a tight budget, and they fit a move well.
Where the Sale Price Goes: A Worked Example of the Costs of Selling a House
Here is a worked example that pulls the costs of selling a house together. The numbers below are illustrative only, chosen to make the arithmetic easy to follow. They are not averages or typical rates, and your own figures could be higher or lower.
Suppose a household sells a home for $400,000 and estimates the following:
|
Item |
Illustrative amount |
|
Sale price |
$400,000 |
|
Agent compensation |
− $20,000 |
|
Pre-listing repairs, paint, and cleaning |
− $4,000 |
|
Staging, storage, and marketing extras |
− $1,500 |
|
Settlement, title, and recording charges |
− $3,500 |
|
Credit to the buyer after inspection |
− $3,000 |
|
Prorated property taxes |
− $2,000 |
|
Mortgage payoff |
− $260,000 |
|
Moving costs |
− $5,000 |
|
Estimated net proceeds |
$101,000 |
The selling costs alone, before the mortgage payoff and the move, come to $34,000 in this example. Add the $260,000 payoff and the $5,000 move, and $299,000 of the $400,000 sale price is spoken for. The household walks away with $101,000, about a quarter of the sale price.
Now picture the same household planning a $70,000 down payment and closing costs on its next home. The remaining cushion is $31,000, and an unplanned $10,000 repair request or a few months of carrying two homes could eat a large share of it. This is why the cost to sell a house deserves a written worksheet, not a rough guess.
Seller’s Checklist: How to Lower the Costs of Selling a House
Use this checklist before you list, and update it each time you receive an offer. Each step either lowers the cost to sell a house or keeps a surprise from shrinking your check:
- Write down a conservative expected sale price, not the best-case number.
- Get agent compensation and any extra fees in writing, in dollars.
- Request a mortgage payoff quote and check for liens or unpaid balances.
- List needed repairs and get at least two estimates for each.
- Decide whether a pre-listing inspection makes sense for your home.
- Declutter and donate early to cut staging, storage, and moving costs.
- Ask a settlement professional for a preliminary seller estimate of closing costs.
- Set aside a reserve for buyer-requested repairs or credits.
- Gather purchase records and improvement receipts for tax purposes.
- Price out the move, temporary housing, and any overlap between homes.
- Compare offers by estimated net proceeds, not by price alone.
- Review the settlement statement before closing day.
Get the numbers early
Request a mortgage payoff quote and a preliminary seller estimate before listing. Early information gives you time to clear a lien, find a missing document, or reconsider a sale that would leave too little cash.
Prioritize visible and important repairs
Fix safety problems and defects that can derail financing. Clean thoroughly and improve the entry, lighting, and basic function. Avoid remodeling just because a trend is popular unless local advice and comparable sales suggest it is worth it.
Read the estimated settlement statement
Do not wait for the closing table. Check the sale price, credits, payoff amounts, prorations, fees, and your expected proceeds. Ask for corrections in writing and make sure the final version matches the agreed terms.
Negotiate the whole offer
The highest offer is not always the strongest offer. Compare the price, financing, inspection terms, closing date, requested credits, included personal property, and the likelihood of closing. A slightly lower offer with fewer concessions may leave you with more money.
Once the sale closes, give the proceeds a plan before they disappear into the move. Our list of ways to save money can help you rebuild your cushion in the new home.
Costs of Selling a House: Frequently Asked Questions
What is usually the biggest cost of selling a house?
For most sellers who use an agent, agent compensation is the largest expense after the mortgage payoff. Because it is often figured as a percentage of the sale price, every point is worth $3,000 on a $300,000 sale, so negotiate it and get the terms in writing.
How much are closing costs for a seller?
There is no single answer. Seller closing costs depend on where you live, local custom about who pays what, the sale price, and what you negotiate with the buyer. Ask a settlement or escrow professional for a preliminary estimate before you list, then update it when you accept an offer.
Is it worth making repairs before selling a house?
Repairs that affect safety, financing, or obvious first impressions are often worth doing. Big cosmetic upgrades may not pay for themselves. Get estimates, ask your agent what local buyers expect, and compare the repair cost with offering a price reduction or credit instead.
What costs can I deduct when I sell my home?
IRS Publication 523 explains that selling expenses such as commissions, advertising, and legal fees reduce the amount realized from a home sale, which can lower any taxable gain. Many owners also qualify to exclude some or all of the gain. Rules depend on your situation, so check the publication or ask a tax professional.
The Bottom Line
The costs of selling a house include far more than the agent’s fee. Preparation, marketing, closing costs, buyer credits, loan payoffs, liens, taxes, moving, and the timing between homes can all shrink the amount you keep.
Start with a realistic sale price and subtract every likely expense, including the ones that show up after closing. Get written estimates, keep records, question unfamiliar fees, and leave room for surprises. If you are new to running a household budget this way, our guide to frugal living for beginners is a good next step. When you know the difference between the sale price and your net proceeds, you can choose repairs wisely, judge offers clearly, and move into your next home with confidence.
Get the free Homeowner Repair Cost Playbook
Which systems fail first, what they cost, the warning signs, and the repair-or-replace rule. 15 printable pages.
Free. No spam.
Free tool
Repair or replace?
Got a quote for your furnace, AC, water heater or an appliance? Check it in under a minute.
Free tool
What needs replacing next?
Enter the install years for your furnace, AC, water heater and appliances. See what is due first and what to save each month.