Barefoot Investor for Families Review: 7 Simple Lessons for Kids
This Barefoot Investor for Families review starts with a confession: an earlier version of this post mixed up two different books. Scott Pape’s first book, The Barefoot Investor, is about adult budgeting with “buckets” and bank accounts. The Barefoot Investor for Families is something else. It is a guide for parents on teaching children about money, built around jobs, pocket money and three simple jars. This rewrite fixes that and focuses on what the families book actually teaches.
Money is rarely just about money in a household. It is also about tired parents, children asking for treats at the checkout, and the quiet worry that kids are growing up without knowing what things cost. That is why a book about kids and money can be so appealing. It does not start with investment products or a lecture. It starts with a practical question: how can children learn the value of a dollar at home, one small habit at a time?
Below you’ll find the verified basics about the book, its seven key lessons in our own words, how a U.S. family might adapt them, a fair list of pros and cons, and who the book suits best. One thing to know up front: the book is Australian, so some details need translating for American readers.
Barefoot Investor for Families Review: What the Book Is
The Barefoot Investor for Families was written by Scott Pape, an Australian personal finance columnist best known for his 2016 bestseller The Barefoot Investor. The families book followed in 2018 and was published in Australia by HarperCollins. It is a paperback for parents (and grandparents), not a book for children to read on their own.
According to the author’s official books page, it covers ten things kids need to know about money before they leave home, and it presents a pocket money plan that is meant to take about three minutes a week. The same page lists an audiobook version. We could not find a newer revised edition of the families book; listings still point to the 2018 release.
Don’t confuse it with Pape’s later title, Barefoot Kids (2022). That one is written in a visual format for children themselves, with money stories from Australian kids. The 2018 families book is the parent’s playbook.
The Australian context
The book was written for Australian families. Its examples use Australian dollars, Australian banks, Australian schools and the Australian word “pocket money” where most American parents would say “allowance.” Some later lessons touch on superannuation, Australia’s compulsory workplace retirement savings system. The closest U.S. concept is an employer retirement plan such as a 401(k), although the rules are very different. Bank products mentioned in a 2018 book may also have changed since.
None of that makes the book less useful in the U.S. The core ideas are about behavior, not products. You just have to read it with a translator’s eye.
The Big Idea Behind the Barefoot Investor for Families
At its heart, the Barefoot Investor for Families argues that children learn about money by handling it, not by hearing about it. A child who earns a little money, divides it up, waits for something they want, and gives some away learns more than a child who is simply handed cash or told “we can’t afford that.”
The system has three working parts:
- Jobs: children do a few age-appropriate jobs around the house and are paid for them.
- Jars: the money goes into three physical jars, each with its own purpose.
- A weekly family money meal: a regular meal where parents check the jobs, pay the kids and talk about money.
The amount of pocket money is not the important part. The practice of earning, choosing and living with the result is the lesson. That idea carried over from the original version of this post, and it holds up well.
Barefoot Investor for Families Review: The 7 Simple Lessons
Here are the seven ideas that stood out most to us, summarized in our own words. They are not a list of the book’s chapters, and the book contains more detail, stories and age-by-age guidance than we cover here.
1. Pocket money should be earned
Pape’s position is that pocket money is pay for work, not a gift. Children are given a small number of age-appropriate jobs, and they are paid when the jobs are done. If a job is skipped, it isn’t paid. The point is to connect effort and money early, in a low-stakes setting where the “job” might be feeding the dog or unpacking the dishwasher.
2. Three jars give money a job
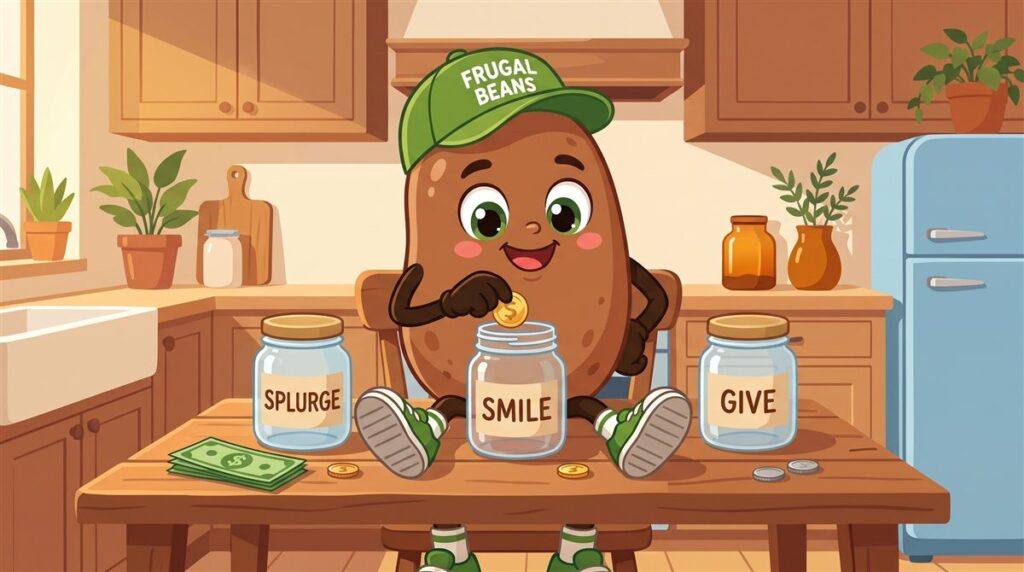
Each payday, children split their pocket money into three clear jars. The Splurge jar is for everyday spending. The Smile jar is for saving toward something bigger; Pape describes it as saving for “something that makes them smile.” The Give jar is for generosity toward people or causes in need.
This mirrors the adult idea of separating money by purpose. A child can see at a glance what is available to spend now and what is set aside for later.
3. Real cash comes before cards
The jars are physical for a reason. Watching coins and bills pile up, or disappear, makes money feel real in a way a balance on a screen does not. Moving to a bank account comes later, once the habit is in place.
4. Talk about money at a weekly family meal
The book’s routine centers on a weekly family meal where everyone sits down together. A few minutes go to checking jobs and paying the kids, and the rest of the time is simply family conversation, which naturally includes money stories and questions. Making money a normal dinner topic lowers the temperature. Children learn that money can be discussed calmly, not whispered about or argued over.
5. Waiting is a skill worth practicing
The Smile jar is really a lesson in delayed gratification. A child who wants a toy, a game or a day out has to save for it over weeks. That wait is the point. Kids learn to set a goal, track progress and decide whether the thing still matters by the time they can afford it.
6. Generosity is part of the plan
The Give jar builds kindness into the routine instead of leaving it to chance. Children choose where their giving goes, which turns generosity into something they own rather than something adults do on their behalf.
7. Aim for ten money milestones before kids leave home
The book frames the bigger goal as a set of ten milestones children should reach before adulthood. Reviewers’ summaries describe topics such as the value of hard work, opening a bank account, buying and selling second-hand items, cooking low-cost meals, volunteering and, for older teens, understanding Australian retirement savings. The milestones run from early childhood through the teen years, so the book grows with a family over time.
What the Book Does Especially Well
The first major strength is accessibility. The tone is direct, warm and energetic, and it is written for parents who may not feel financially confident themselves. You don’t need to understand compound interest to start; you need three jars and a few minutes a week.
The second strength is that it treats kids and money as a behavior problem rather than an information problem. A spreadsheet cannot teach a seven-year-old patience. Repeated small choices can. The jar system gives children those choices every single week.
The third strength is its permission to enjoy money. The Splurge jar exists on purpose. A child who never gets to spend anything learns that money is about guilt and restriction. A defined spending amount creates room for small pleasures without undermining the larger lessons.
Finally, the book treats financial capability as a family skill. Children participate in age-appropriate ways, and both parents can share responsibility. That makes money less mysterious at home and reduces the chance that one adult becomes the only person who understands it.
How U.S. Families Could Adapt the Barefoot Investor for Families
Important: this section is our Frugal Beans adaptation for American households. It is not advice from the book, and it is general information, not financial advice.
Most of the system translates easily. The jobs, the jars and the weekly meal work the same in Ohio as they do in Melbourne. The pieces that need adjusting are the Australian specifics: bank products, pocket money norms, and anything tied to superannuation or Australian tax rules.
Turn pocket money into a simple U.S. allowance
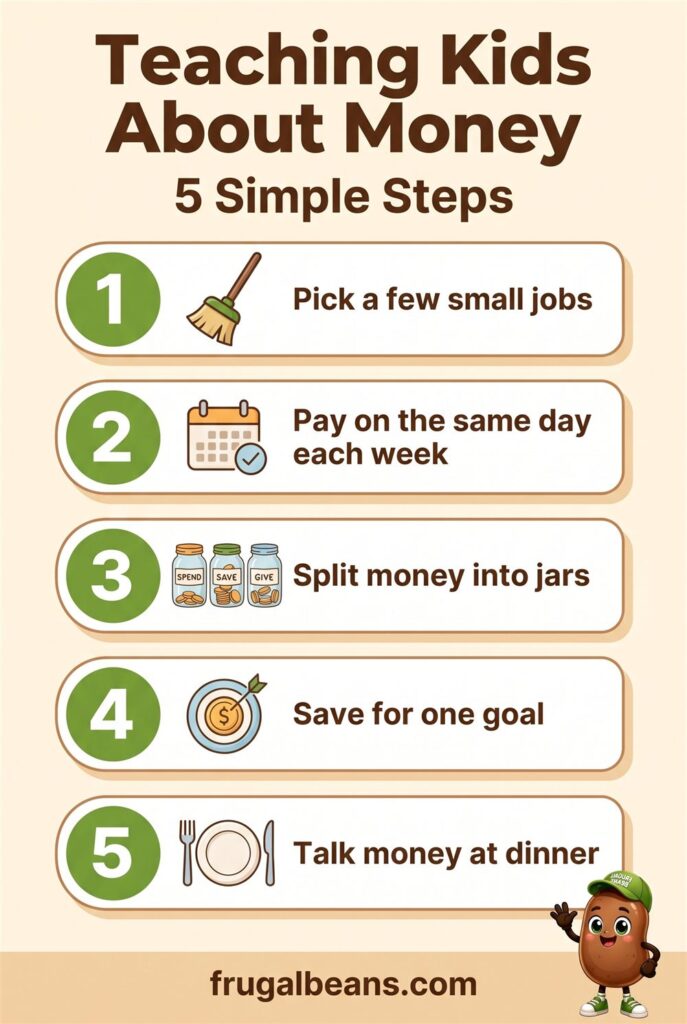
Call it an allowance, call it pocket money; what matters is consistency. Pick a fixed payday that matches your household rhythm, such as Sunday dinner or the day a parent gets paid. Keep the amount modest and predictable. A small, reliable amount teaches more than a large one that shows up only when a parent remembers.
Many American families also separate “helping because we live here” chores, like clearing your own plate, from paid jobs. That’s our suggestion, not a rule from the book, but it can stop kids from asking to be paid for every small task.
Choose your own jar labels
Some U.S. parents prefer plainer names such as Spend, Save and Give, especially with younger kids who may find “Splurge” confusing. The labels matter less than the separation. A clear jar, a strip of tape and a marker are all you need, which keeps this a genuinely frugal project.
Plan the step from jars to a bank account
When the jars are working, you can explore a youth savings account at a local bank or credit union. Look carefully at fees, minimum balances and who controls the account before opening anything. Product names and terms vary, so compare a few options rather than taking any one recommendation at face value.
Use a U.S. resource for age-by-age milestones
If you want an American companion to the book, the Consumer Financial Protection Bureau’s Money as You Grow program offers free money milestones, activities and conversation starters for parents, organized for young children, school-age kids and preteens, and teens to young adults. It pairs well with the jar system and is written for U.S. families.
Swap superannuation lessons for U.S. basics
When the book gets to Australian retirement savings, translate the idea rather than the details. For a U.S. teen, the closest equivalent conversation might be what a first paycheck stub shows, why taxes and payroll deductions appear on it, and what an employer retirement plan is. Keep it descriptive; the goal is understanding, not picking investments.
Kids and Money: Lessons Parents Can Use Too
One quiet benefit of the book is that it nudges parents to look at their own habits. If you ask a child to split pocket money three ways, you may start wondering how your own paycheck is divided. That is a good question to ask.
The original version of this post included several family budgeting habits that are worth keeping, as long as we’re clear they are ours, not the book’s:
- Hold a short weekly check-in. Ten minutes is enough to cover what has been paid, what is coming up and what needs a decision. Keep it neutral; it is not a courtroom.
- Create an irregular-expense fund. Divide annual costs by twelve and set aside that amount monthly. If school supplies and car registration together cost $1,200 a year, saving $100 a month turns a surprise into a planned bill.
- Build a starter emergency buffer. Even a few hundred dollars can stop a minor repair from becoming expensive debt.
- Give kids controlled choices. Let children compare prices and wait for a goal. Avoid rescuing them from every poor choice, while still protecting essentials such as food, safety and education.
- Adjust after real spending. Watch what actually happens for two or three months, then increase, rename or combine categories.
If you are just starting out, our guide to frugal living for beginners covers the household side, and our budgeting tips for a tight budget help you set realistic amounts. Children notice when a family’s money system actually works, and they copy it.
Barefoot Investor for Families Review: Pros and Cons
No book is perfect for every household. Here is a balanced view.
|
Pros |
Cons |
|
Simple, concrete system kids can see and touch |
Written for Australia; banks, pocket money norms and retirement rules don’t match the U.S. |
|
Warm, encouraging tone for parents who feel unsure about money |
Product references date from 2018 and may be out of date |
|
Builds generosity and patience, not just saving |
Paying for jobs may not fit families who see all chores as shared duties |
|
Very low cost to start: jars and a weekly routine |
Some parents find the jar names or the strong opinions take getting used to |
|
Grows with children through milestones up to the teen years |
Less useful for older teens who already earn and bank on their own |
Where readers should use judgment
The book works best as a framework, not a rigid formula. Every household has different income, schedules and values. A system that runs smoothly for a family with a steady paycheck may need loosening for a parent with irregular shifts or freelance income. If a fixed weekly payday is not realistic, pick a rhythm you can keep.
Parents should also apply their own judgment about chores. Some families are comfortable paying for jobs; others prefer that everyone helps without payment and that pocket money is given separately. Neither approach is wrong. The deeper lesson, that money is limited and choices have trade-offs, can be taught either way.
Who Should Read This Book?
The book is particularly suitable for:
- Parents of children from preschool through early teens who want a ready-made system.
- Couples who want a shared starting point for teaching kids and money.
- Grandparents and caregivers who want to support the same habits.
- Parents who feel overwhelmed by financial jargon and want something practical.
It may suit you less if your children are older teens who already have jobs and bank accounts, if you strongly prefer unpaid chores, or if you want a detailed U.S. guide to accounts and taxes. In that last case, the book is still a good source of habits, but pair it with U.S. resources. For more money-saving ideas for the whole household, browse our frugal living tips and our list of ways to save money.
Barefoot Investor for Families Review: FAQ
What is the Barefoot Investor for Families about?
It is a 2018 book by Australian author Scott Pape that shows parents how to teach children about money. The system uses paid, age-appropriate jobs, three jars (Splurge, Smile and Give) and a weekly family money meal, along with ten money milestones for kids to reach before leaving home.
What are the three jars in the Barefoot Investor for Families?
The jars are Splurge for everyday spending, Smile for saving toward a bigger goal, and Give for helping others. Children divide their pocket money between the three each time they are paid.
Is the Barefoot Investor for Families useful outside Australia?
Yes, for the habits. Jobs, jars and family money talks work anywhere. The Australian-specific parts, such as banks and superannuation, need translating; U.S. readers can pair the book with the CFPB’s free Money as You Grow resources.
How much pocket money should kids get?
There is no single right amount. What matters more is that pocket money is predictable, paid on a regular day and small enough that children have to make choices. Start modestly and adjust as your child takes on more responsibility.
The Bottom Line
Our Barefoot Investor for Families review comes down to this: the book succeeds because it makes kids and money a normal part of family life. Jobs connect work and pay, the three jars give every dollar a purpose, and a weekly meal keeps the conversation going.
Use it selectively. Keep the principles of earning, separating, waiting and giving. Translate the Australian details for your own country and bank. Treat the specifics as suggestions, not commandments. A good pocket money system won’t make every week easy, but it gives children something better than a lecture: practice.
Get the free Homeowner Repair Cost Playbook
Which systems fail first, what they cost, the warning signs, and the repair-or-replace rule. 15 printable pages.
Free. No spam.
Free tool
Repair or replace?
Got a quote for your furnace, AC, water heater or an appliance? Check it in under a minute.
Free tool
What needs replacing next?
Enter the install years for your furnace, AC, water heater and appliances. See what is due first and what to save each month.
Leave a Reply