Barista FIRE Calculator
Barista FIRE is a middle path to financial independence: you save and invest until your portfolio can cover part of your spending, then swap full-time work for a lower-stress part-time job that pays for the rest. This free barista FIRE calculator shows the age you could make that switch, your barista FIRE number, and how it compares with full FIRE, all in today’s dollars.
Loading the barista FIRE calculator… If it doesn’t appear, please make sure JavaScript is turned on.
How to Use the Barista FIRE Calculator
- Enter your age and what you’ve invested so far, counting retirement accounts and taxable investments, not your home or emergency cash.
- Enter how much you add each year while you’re still working full-time.
- Enter the yearly spending you want once you downshift, in today’s dollars. Include health insurance, which you may have to buy yourself.
- Enter your expected part-time take-home pay. This is the income that lets your portfolio do less of the work.
- Choose the age you’d stop working completely, and any other income you expect after that, such as Social Security or a pension.
- Check the return and withdrawal rate. The defaults are a 5% return after inflation and a 4% withdrawal rate. Lower them for a more cautious plan.
The barista FIRE calculator shows the earliest age you could switch to part-time work, how much you’d have invested by then, and a chart of your portfolio through three stages: saving full-time, barista years and full retirement. Your inputs are saved in your own browser, so you can come back and adjust them.
What Is Barista FIRE?
FIRE stands for financial independence, retire early. Traditional FIRE means saving enough that investments cover all of your spending, often estimated as 25 times your yearly expenses. Barista FIRE is a softer version: you reach financial independence for part of your spending and earn the rest from part-time or flexible work you actually enjoy.
The name comes from the idea of leaving a demanding career to work a few shifts at a coffee shop, partly for the paycheck and partly for the health insurance some employers offer part-time staff. In practice, barista FIRE can be any lighter work: tutoring, freelancing, seasonal jobs, consulting a few days a month or part-time hours in your old field.
How the Barista FIRE Number Is Calculated
The basic barista FIRE number covers only the gap between your spending and your part-time income:
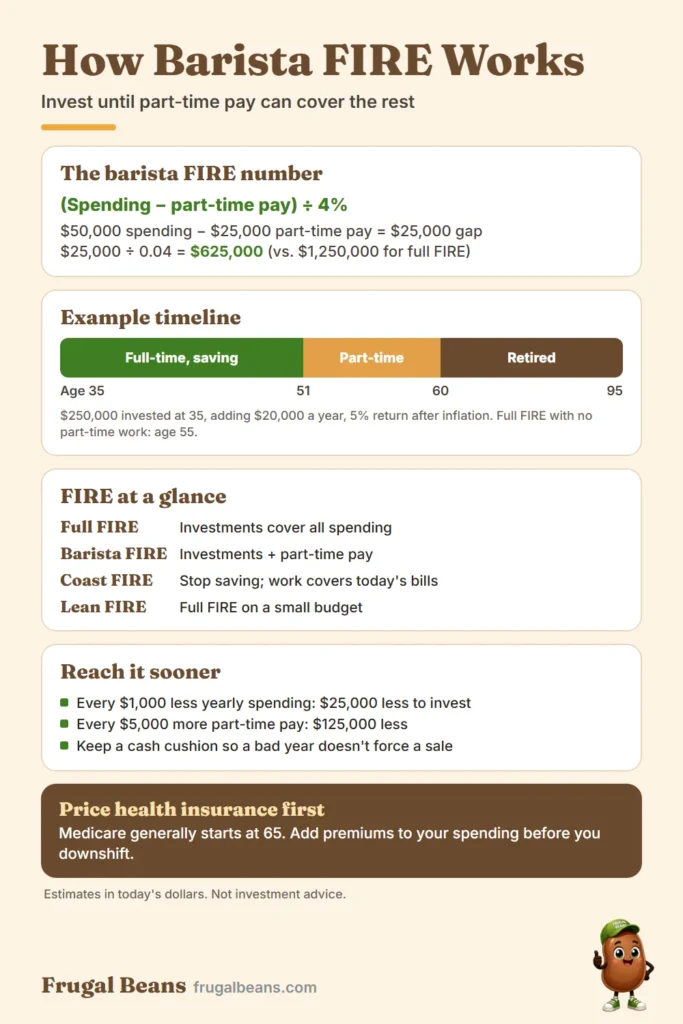
Barista FIRE number = (yearly spending − part-time income) ÷ withdrawal rate
For example, if you spend $50,000 a year and earn $25,000 part-time, your portfolio needs to cover $25,000. At a 4% withdrawal rate, that’s $25,000 ÷ 0.04 = $625,000, half the $1,250,000 you’d need for full FIRE.
That simple number assumes you’d keep working part-time indefinitely. Most people want to stop working completely someday, so the barista FIRE calculator also runs a timeline. It finds the earliest age when your portfolio, while covering the gap each year, would still grow into your full FIRE number by the age you plan to stop working. That is the age it shows as your downshift age.
Example: Downshifting at 51 Instead of Working to 55
Take a 35-year-old with $250,000 invested who adds $20,000 a year, wants to spend $50,000 a year and could earn $25,000 a year part-time. Assuming a 5% return after inflation and a 4% withdrawal rate:
| Plan | Age | Invested at that age |
| Switch to part-time (barista FIRE) | 51 | About $1,019,000 |
| Full FIRE with no part-time work | 55 | About $1,325,000 |
| Stop working completely (barista plan) | 60 | About $1,305,000 |
Barista FIRE trades four extra years of full-time work for nine years of part-time work. Whether that’s a good trade depends on how much you’d enjoy the lighter job and how much the extra free time is worth to you. Change any number in the calculator to see your own version.
Barista FIRE vs. Coast FIRE vs. Lean FIRE
- Full FIRE: your investments cover all of your spending. No job needed.
- Barista FIRE: your investments cover part of your spending, and part-time work covers the rest. You may still draw on the portfolio.
- Coast FIRE: you’ve saved enough that, with no more contributions, growth alone will reach your full FIRE number by retirement age. You still work to pay today’s bills, but you stop saving for retirement. If your part-time pay covers all of your spending, barista FIRE becomes coast FIRE, and the calculator shows that case too.
- Lean FIRE: full FIRE on a small budget, usually by keeping spending well below average.
Barista FIRE vs. coast FIRE is mostly a question of whether you still need to withdraw from your investments. Barista FIRE usually lets you downshift sooner because the portfolio can carry part of the load.
Health Insurance and Barista FIRE
Health insurance is often the biggest cost to plan for. Medicare generally starts at 65, so anyone who leaves a full-time job earlier needs another source of coverage. Options include a part-time job that offers benefits, a spouse’s plan, COBRA for a limited time, or a plan from the Health Insurance Marketplace, where losing job-based coverage lets you enroll outside open enrollment (HealthCare.gov). Help with Marketplace premiums is based on income, so a lower part-time income can mean a lower premium. Add your expected premiums to the spending you enter in the barista FIRE calculator.
Social Security and Other Income
If you were born in 1960 or later, your full retirement age for Social Security is 67 (Social Security Administration). You can claim as early as 62, but the monthly benefit is permanently reduced. Fewer years of full-time earnings can also lower your future benefit, so check your estimate at ssa.gov before you count on it.
Enter any income you expect after you stop working, such as Social Security or a pension, in the “other income” box. The barista FIRE calculator subtracts it from your spending and lowers the amount you need invested by your final stop age. If it only starts years after you stop, leave it out or use a smaller amount to stay cautious.
Is the 4% Rule Safe for Barista FIRE?
The 4% rule is a rule of thumb from research on how much retirees could withdraw from a mix of stocks and bonds over about 30 years without running out. Early retirees may need their money to last 40 years or more, so many choose 3.5% or even 3% to be safer. Barista FIRE helps here: part-time pay reduces how much you withdraw in the early years, when a market drop would hurt most.
The calculator assumes a steady return every year. Real returns jump around, so treat the result as a planning estimate and rerun it every year or two with your actual balance.
How to Reach Barista FIRE Sooner
- Lower your planned spending. Every $1,000 a year you don’t need cuts your barista FIRE number by $25,000 at a 4% withdrawal rate. Our guide to how to budget and our frugal living tips are good places to find it.
- Raise your part-time income. Each extra $5,000 of part-time pay lowers the number by $125,000.
- Save more now. A raise or bonus invested before you downshift has the longest time to grow.
- Keep an emergency fund in cash. A cushion means you don’t have to sell investments in a bad year. Our emergency fund calculator shows how much is enough.
- Try it before you quit. Live on your planned barista budget for a few months, or test the lighter work on weekends, before you leave your full-time job.
Frequently Asked Questions
What is a barista FIRE number?
It’s the amount you need invested so that withdrawals cover the gap between your spending and your part-time income. With a $25,000 gap and a 4% withdrawal rate, it’s $625,000.
How much do you need for barista FIRE?
Less than for full FIRE, and how much less depends on your part-time income. If part-time work covers half of your spending, the basic barista FIRE number is half your full FIRE number.
Does the barista FIRE calculator account for inflation?
Yes. Enter everything in today’s dollars and use a return after inflation. A 5% real return is roughly a 7% to 8% return before 2% to 3% inflation.
Do I have to work at a coffee shop?
No. Barista FIRE means any part-time or flexible work that covers part of your spending. Many people consult, freelance or work fewer hours in their own field.
What’s the difference between barista FIRE and coast FIRE?
With coast FIRE you stop saving but still earn enough to cover all of your spending, so your investments are untouched. With barista FIRE your part-time income covers only part of your spending, and your investments cover the rest.
Is my information saved or shared?
Your inputs are saved only in your own browser. Nothing is sent to Frugal Beans.
The Bottom Line
Barista FIRE lets you trade some years of full-time work for part-time work you choose, while your investments keep growing toward full independence. Use the barista FIRE calculator to find your number and your downshift age, price health insurance carefully, keep a cash cushion, and rerun the plan as your savings grow. For the bigger picture, read our guide to how to retire early and explore all of our free tools.
Sources: Social Security full retirement age from the Social Security Administration. Coverage options before Medicare from HealthCare.gov. Results assume a steady return after inflation and constant spending; they are estimates, not investment advice.
Get the free Homeowner Repair Cost Playbook
Which systems fail first, what they cost, the warning signs, and the repair-or-replace rule. 15 printable pages.
Free. No spam.
Free tools
Got a quote? Check it in under a minute.
Ballpark a new furnace before the contractor visits.
Price a tank, tankless or heat pump model.
Warm air, ice or noise? See the likely part and price.